













Buddhabhumi Nepal Hydropower Co. Ltd. – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
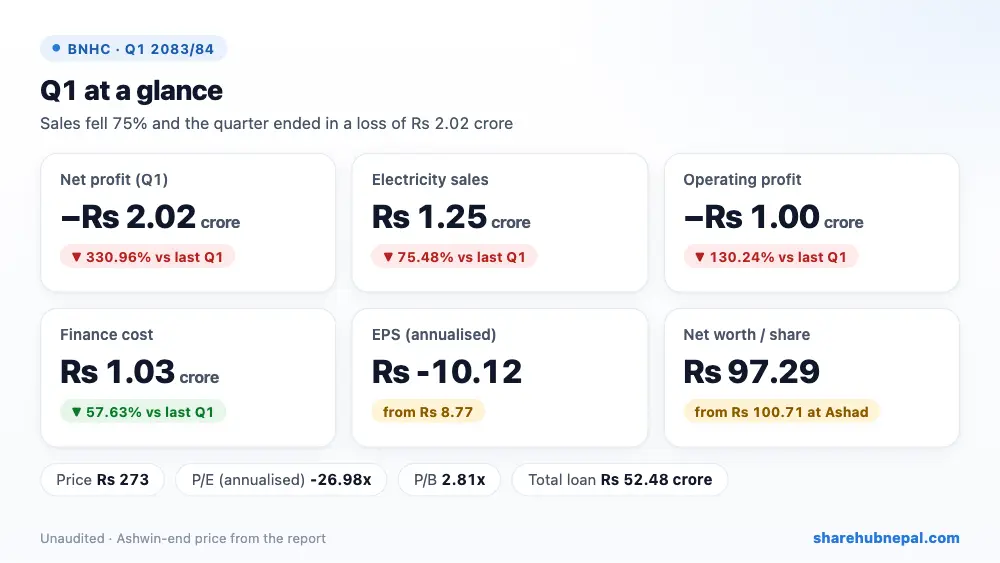
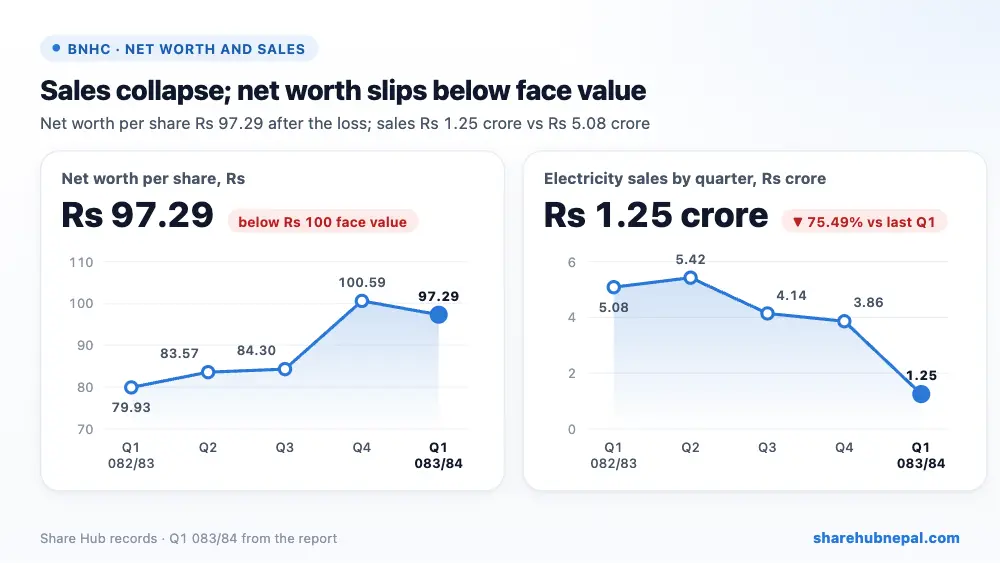
Buddhabhumi Nepal Hydropower (Tallo Tadi Khola, 4.993 MW) posted a net loss of Rs 2.02 crore in the first quarter of FY 2083/84, against a profit of Rs 87.68 lakh a year ago. Electricity sales fell 75.49% to Rs 1.25 crore from Rs 5.08 crore, even though Q1 is normally the strongest monsoon quarter. The report does not explain the drop in generation. Annualised EPS is Rs -10.12 and net worth per share fell to Rs 97.29, below the Rs 100 face value.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Revenue from sales | Rs 12,458,520 | Rs 50,819,910 | −75.48% |
| Cost of sales | Rs 1,422,392 | Rs 1,424,471 | −0.15% |
| Other income | Rs 92,449 | Rs 96,254 | −3.95% |
| Operating profit | −Rs 10,002,934 | Rs 33,073,775 | Turned to loss |
| Finance cost | Rs 10,339,284 | Rs 24,402,517 | −57.63% |
| Income tax | Rs 0 | Rs 0 | – |
| Net profit | −Rs 20,249,769 | Rs 8,767,513 | Turned to loss |
| EPS (annualised) | -10.12 | 8.77 | – |
| Net worth per share | 97.29 | 79.93 | – |
1. Where the profit came from
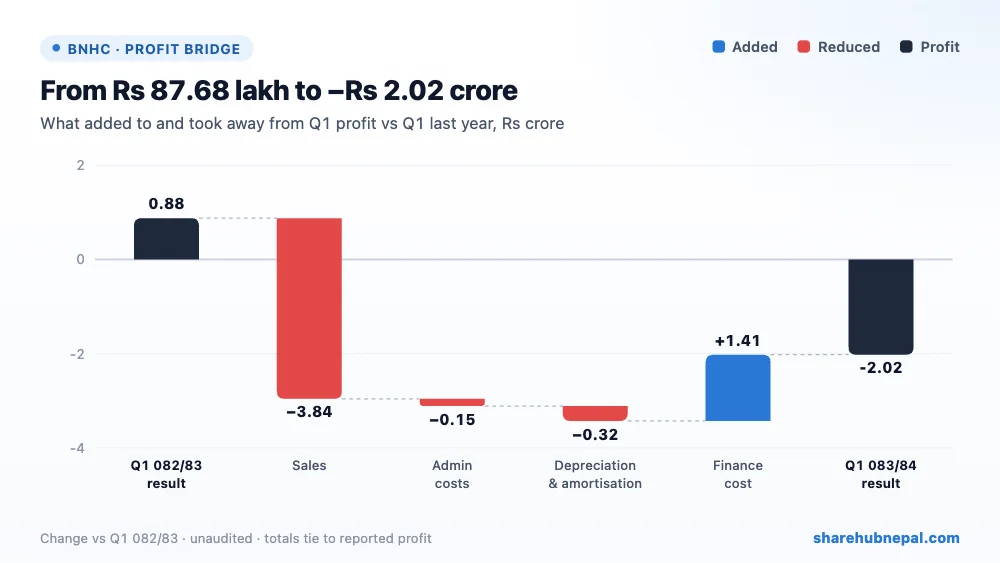
Lower electricity sales took away Rs 3.84 crore. Depreciation and amortisation rose by Rs 31.75 lakh to Rs 1.47 crore (mostly amortisation of the project asset) and admin cost by Rs 15.42 lakh. The big help was finance cost, which fell by Rs 1.41 crore (57.63%) to Rs 1.03 crore because the company used its right-share money to repay loans. Direct plant expenses stayed flat at Rs 14.22 lakh, so almost all of the fall came from lower generation.
2. Profit through the year
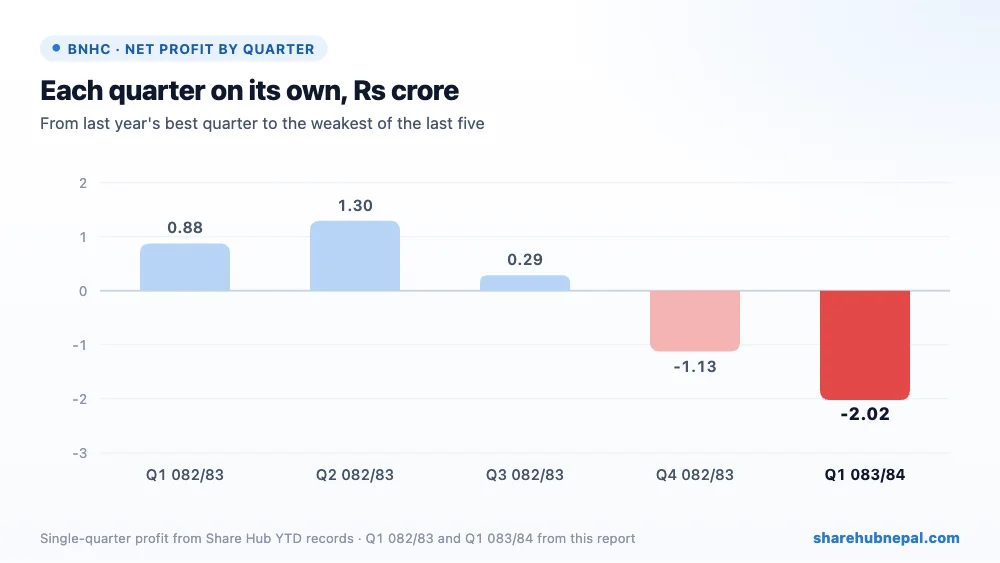
Profit by quarter (Share Hub records): Q1 082/83: Rs 87.68 lakh, Q2 082/83: Rs 1.30 crore, Q3 082/83: Rs 28.61 lakh, Q4 082/83: −Rs 1.13 crore, Q1 083/84: −Rs 2.02 crore. Q4 082/83 was already a loss as sales slowed, and FY 2082/83 ended with a profit of Rs 1.21 crore (Rs 1.29 crore as shown in this report). Q1 082/83 is taken from this report (Rs 87.68 lakh; the Share Hub record has Rs 75.18 lakh).
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Total assets | Rs 1,306,311,877 | Rs 1,591,255,439 | −17.91% |
| Total equity | Rs 778,315,084 | Rs 805,688,915 | −3.40% |
| Long-term borrowings | Rs 524,750,134 | Rs 713,207,310 | −26.42% |
| Current borrowings | Rs 81,033 | Rs 33,433,405 | −99.76% |
| Cash and equivalents | Rs 37,808,833 | Rs 292,880,859 | −87.09% |
The company doubled its paid-up capital to Rs 80 crore with a right share in FY 2082/83 and is now using that money to cut debt. In Q1, long-term loans fell from Rs 71.32 crore to Rs 52.48 crore and short-term loans from Rs 3.34 crore to almost nil, while cash fell from Rs 29.29 crore to Rs 3.78 crore. Total loans are now 0.67 times equity, against about 3.1 times a year ago. Current assets of Rs 6.50 crore are about 24 times current liabilities. Other equity moved from Rs 39.99 lakh to Rs -2.23 crore, Rs 60.34 lakh more than the quarter's loss; the report does not explain this.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised) | Rs -10.12 |
| Net worth per share | Rs 97.29 |
| Market price (Ashwin end) | Rs 273 |
| P/E (annualised) | -26.98x |
| P/B | 2.81x |
At the Ashwin-end price of Rs 273, the share trades at -26.98 times annualised EPS and 2.81 times net worth per share. With a loss this quarter, P/E is negative (the report prints -26.96). The price is 2.81 times net worth per share for a small plant whose sales have just collapsed, so the share looks expensive until generation recovers.
Conclusion
Positives: loans cut by Rs 22.18 crore in one quarter, finance cost down 57.63%, strong liquidity, low debt after the right share.
Watch: sales down 75% in the peak season with no explanation, a quarterly loss, net worth below face value, a heavy amortisation charge, and an unexplained Rs 60.34 lakh extra fall in other equity.
The next reports must show whether generation at Tallo Tadi Khola recovers. Lower interest cost will help, but with only 4.993 MW and a large yearly amortisation charge, BNHC's profit depends on the plant running at full capacity.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

