













I.M.E. Life Insurance Company Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
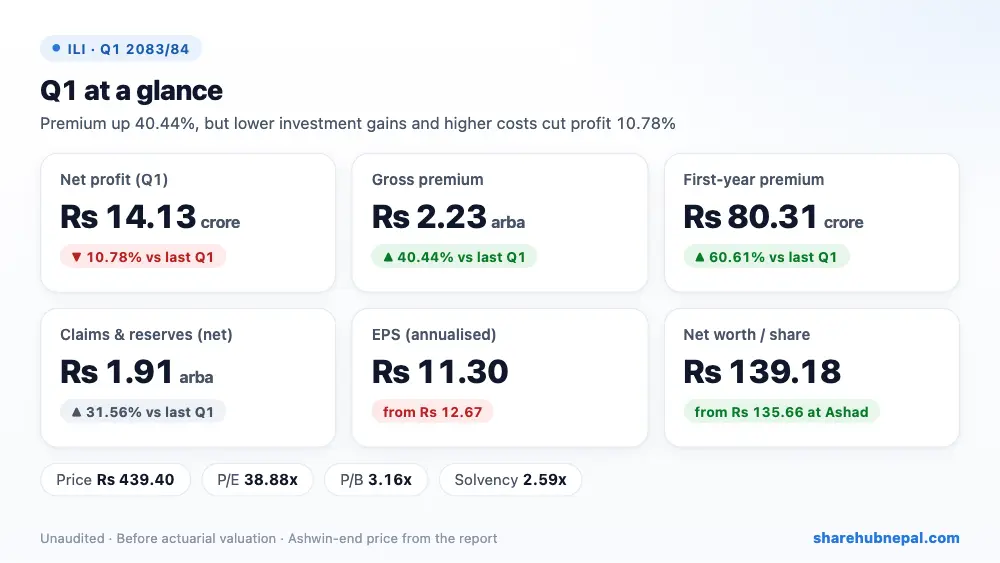
Summary
IME Life earned Rs 14.13 crore in the first quarter of FY 2083/84, down 10.78% from Rs 15.83 crore a year ago. Business grew fast: gross earned premium rose 40.44% to Rs 2.23 arba, first-year premium jumped 60.61% to Rs 80.31 crore and renewal premium rose 31.19%. But income from investments fell 12.90% to Rs 33.18 crore and realised gains dropped from Rs 3.19 crore to Rs 46.79 lakh, while commission (+41.28%) and other operating expenses (+51.76%) rose with the new business. Annualised EPS is Rs 11.30 (Rs 12.67 a year ago) and net worth per share Rs 139.18. Figures are before the actuarial valuation.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Gross earned premium | Rs 2,233,729,500 | Rs 1,590,570,926 | +40.44% |
| Net earned premium | Rs 2,188,581,986 | Rs 1,536,342,500 | +42.45% |
| Income from investments and loans | Rs 331,831,237 | Rs 380,991,597 | −12.90% |
| Realised gains | Rs 4,679,237 | Rs 31,919,559 | −85.34% |
| Net benefits, claims and reserve change | Rs 1,913,133,854 | Rs 1,454,143,879 | +31.56% |
| Commission expenses | Rs 185,640,640 | Rs 131,401,179 | +41.28% |
| Employee benefits | Rs 129,535,659 | Rs 114,090,754 | +13.54% |
| Other operating expenses | Rs 155,099,713 | Rs 102,200,032 | +51.76% |
| Net profit | Rs 141,254,588 | Rs 158,314,060 | −10.78% |
| EPS (annualised) | 11.3 | 12.67 | – |
| Net worth per share | 139.18 | 137.41 | – |
1. Where the profit came from
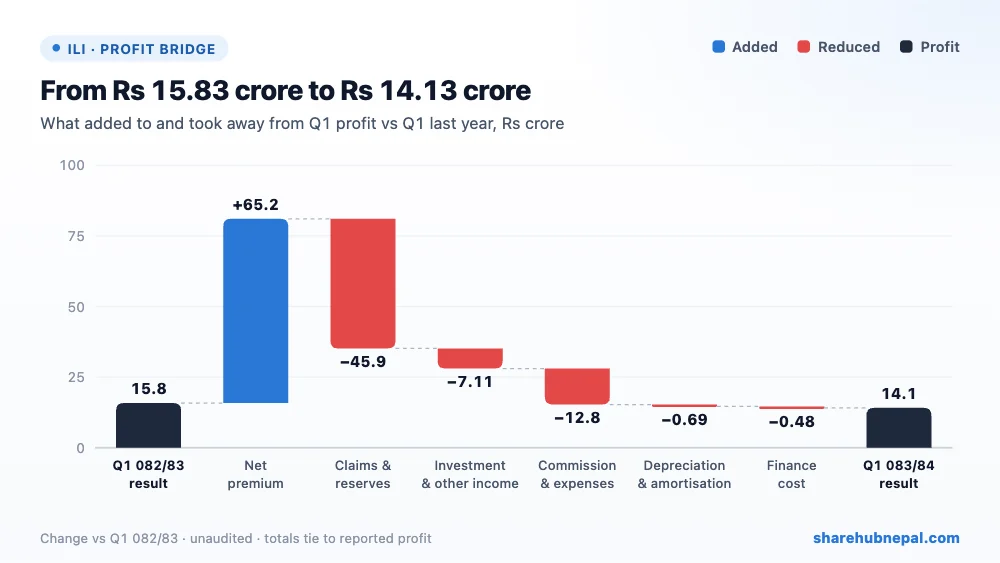
Higher net premium added Rs 65.22 crore, but claims and the addition to policy reserves took Rs 45.90 crore more. Investment and other income was Rs 7.11 crore lower (investment income −Rs 4.92 crore, realised gains −Rs 2.72 crore), and commission, staff and other costs took Rs 12.75 crore more. Depreciation (+Rs 69.02 lakh) and a new finance cost of Rs 47.95 lakh took the rest. No income tax was charged in either quarter.
2. Profit through the year
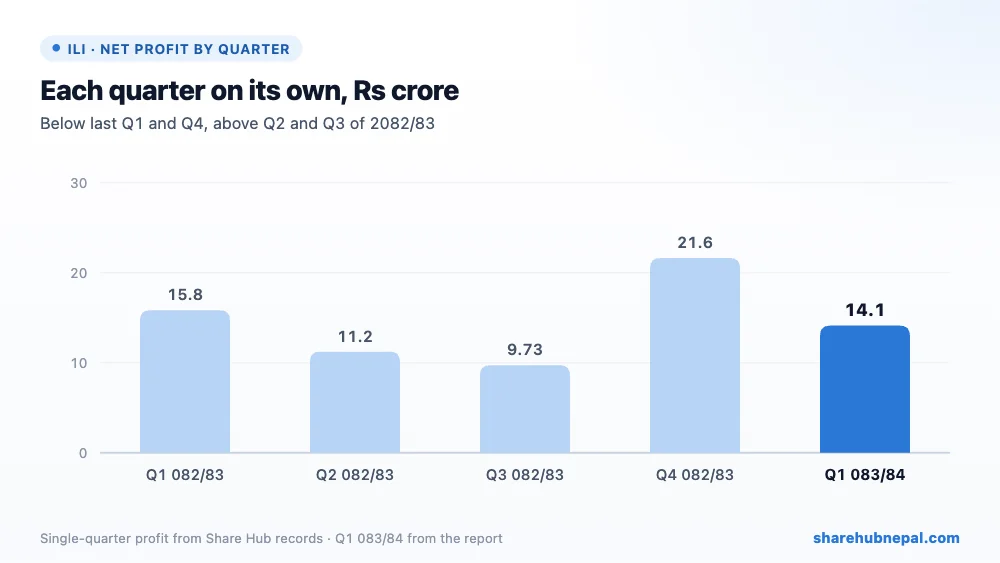
Profit by quarter (Share Hub records): Q1 082/83: Rs 15.83 crore, Q2 082/83: Rs 11.23 crore, Q3 082/83: Rs 9.73 crore, Q4 082/83: Rs 21.63 crore, Q1 083/84: Rs 14.13 crore. Share Hub quarter figures are worked out from year-to-date records. FY 2082/83 profit was Rs 58.42 crore (EPS Rs 11.68); this quarter is about a quarter of that.
3. Debt and balance sheet
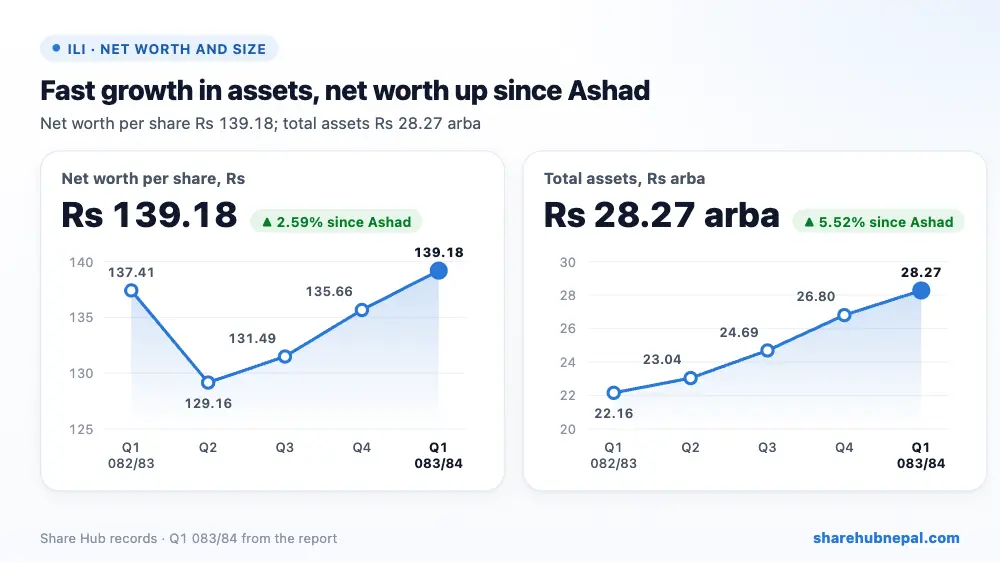
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Total assets | Rs 28,273,748,799 | Rs 26,795,615,857 | +5.52% |
| Investments | Rs 22,135,124,953 | Rs 23,287,691,492 | −4.95% |
| Loans to policyholders | Rs 1,459,855,988 | Rs 1,306,514,083 | +11.74% |
| Gross insurance contract liabilities | Rs 20,635,147,460 | Rs 18,932,051,690 | +9.00% |
| Total equity | Rs 6,958,807,487 | Rs 6,783,098,806 | +2.59% |
| Cash and equivalents | Rs 3,445,014,329 | Rs 936,290,652 | +267.94% |
Total assets rose 5.52% since Ashad to Rs 28.27 arba. Investments fell 4.95% to Rs 22.14 arba while cash jumped from Rs 93.63 crore to Rs 3.45 arba, so about Rs 2.51 arba is waiting to be reinvested (the report does not say why). The life insurance fund is Rs 19.98 arba, 40.83% more than a year ago. Equity rose to Rs 6.96 arba (Rs 139.18 per share), about Rs 3.08 crore less than the quarter's total comprehensive income of Rs 20.66 crore. There are no borrowings and the solvency ratio improved to 2.59 times (2.23 a year ago).
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised) | Rs 11.30 |
| Net worth per share | Rs 139.18 |
| Market price (Ashwin end) | Rs 439.4 |
| P/E (annualised) | 38.88x |
| P/B | 3.16x |
At the Ashwin-end price of Rs 439.4, the share trades at 38.88 times annualised EPS and 3.16 times net worth per share. That is lower than several other life insurers this quarter, but it relies on profit holding up after the actuarial valuation and on the new business turning profitable.
Conclusion
Positives: gross premium up 40.44%, first-year premium up 60.61%, 63,002 new policies, life fund up 40.83%, solvency up to 2.59 times, no borrowings, no income tax charged.
Watch: profit down 10.78%, investment income down 12.90% and realised gains almost gone, commission and other costs growing faster than premium, Rs 2.51 arba of cash not yet invested, low interest rates (named by the company), profit before actuarial valuation.
Strong premium growth but weaker investment returns; the key is putting the extra cash to work and keeping costs in line as the company grows.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

