













Khanikhola Hydropower Company Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
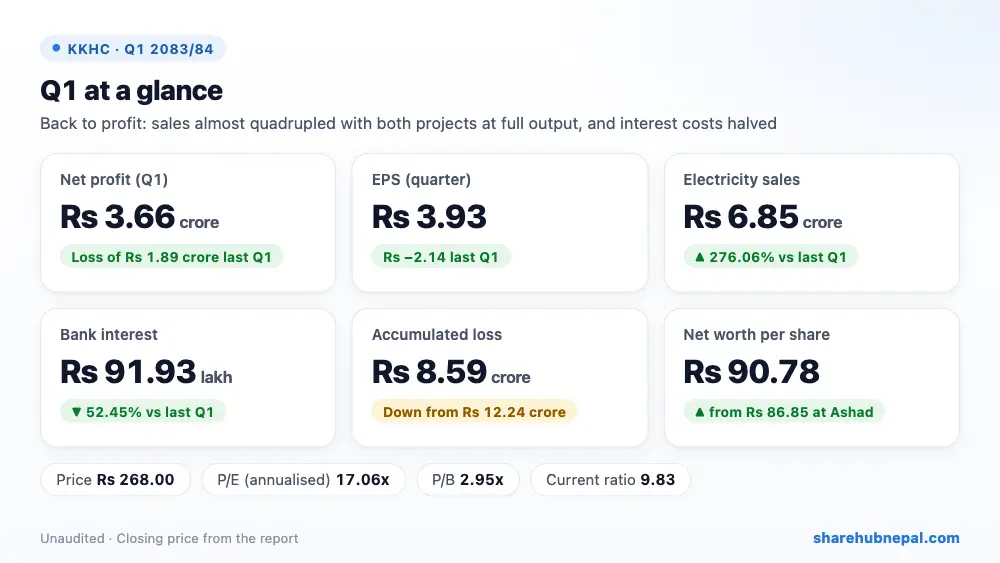
Khanikhola Hydropower earned a net profit of Rs 3.66 crore in the first quarter, against a loss of Rs 1.89 crore in the same quarter last year. EPS for the quarter is Rs 3.93 (about Rs 15.71 annualised).
Electricity sales almost quadrupled (+276.06%) to Rs 6.85 crore; the company says both its projects are now producing at full capacity. Bank interest also halved (−52.45%) to Rs 91.93 lakh as loans came down, while administrative expenses rose 66.48% to Rs 1.12 crore.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Electricity sales | Rs 68,522,145 | Rs 18,221,299 | +276.06% |
| Operating profit | Rs 57,359,625 | Rs 11,516,426 | +398.07% |
| Bank interest | Rs 9,193,245 | Rs 19,331,939 | −52.45% |
| Depreciation | Rs 11,586,680 | Rs 11,099,385 | +4.39% |
| Net profit | Rs 36,579,700 | −Rs 18,914,898 | Turned to profit |
| EPS (quarter) | 3.93 | -2.14 | – |
1. Where the profit came from
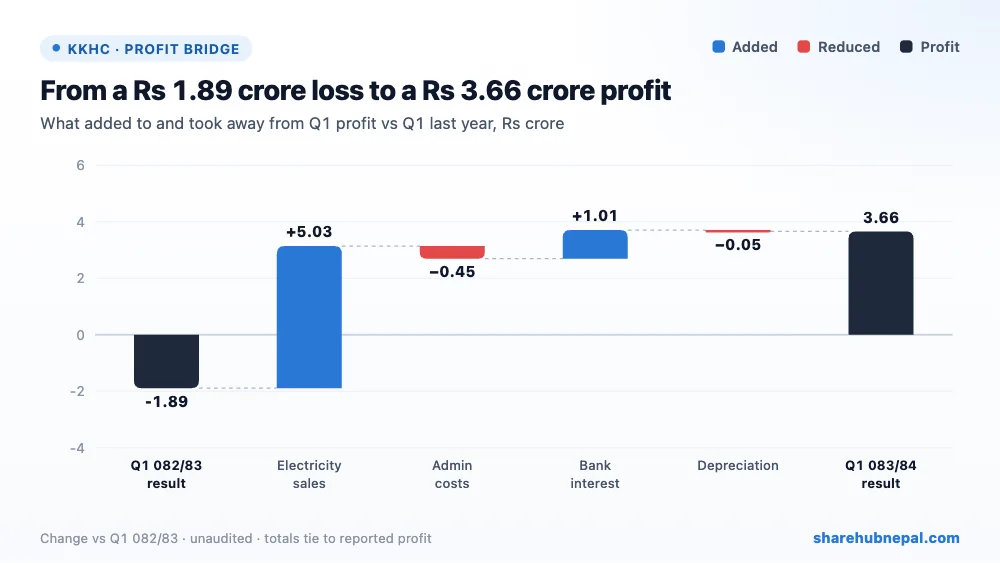
Compared with last year’s Q1, higher sales added Rs 5.03 crore and lower bank interest Rs 1.01 crore. Higher administrative expenses took away Rs 44.58 lakh and depreciation Rs 4.87 lakh. The report shows no tax or staff bonus charge.
2. Profit through the year
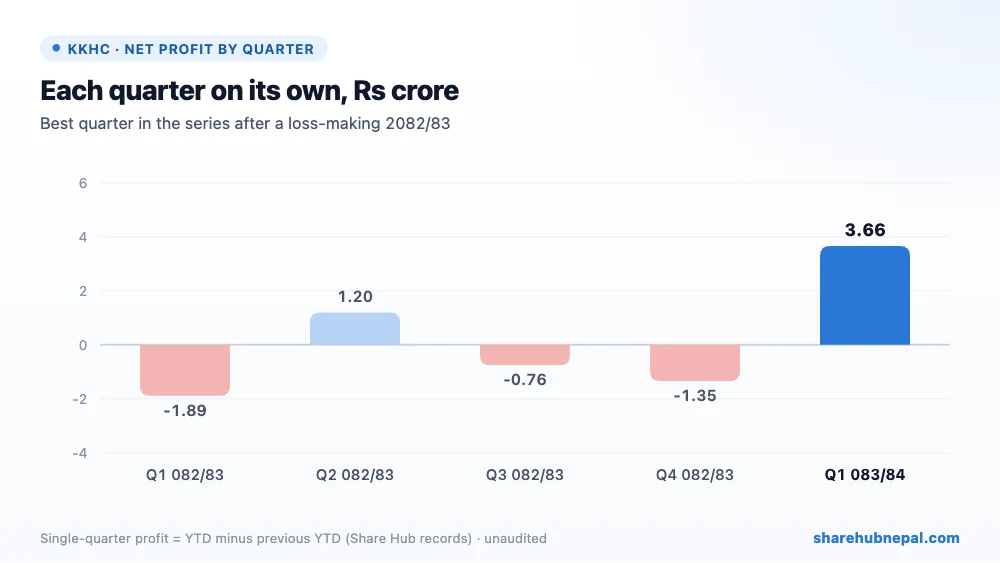
Based on Share Hub’s records (some corrected in this update), 2082/83 was a loss-making year: single-quarter results were a loss of Rs 1.89 crore in Q1, a profit of Rs 1.20 crore in Q2, and losses of Rs 76.22 lakh in Q3 and Rs 1.35 crore in Q4, for a full-year loss of Rs 2.80 crore. This Q1 profit of Rs 3.66 crore is the best quarter in the series, helped by the monsoon.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Long-term loans | Rs 594,535,382 | Rs 602,140,755 | −1.26% |
| Property, plant and equipment | Rs 986,453,695 | Rs 958,760,850 | +2.89% |
| Advances, deposits and receivables | Rs 455,931,972 | Rs 476,812,921 | −4.38% |
| Cash and cash equivalents | Rs 49,121,452 | Rs 26,804,232 | +83.26% |
| Total assets | Rs 1,491,515,118 | Rs 1,462,386,002 | +1.99% |
| Total equity | Rs 845,569,945 | Rs 808,990,245 | +4.52% |
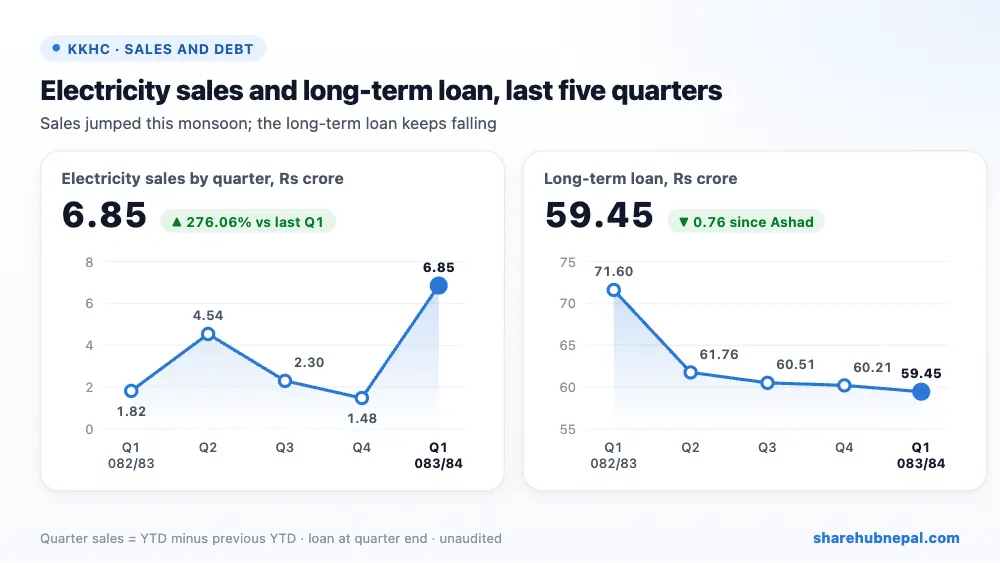
The long-term loan fell to Rs 59.45 crore from Rs 60.21 crore at Ashad end (Rs 71.60 crore a year ago), and short-term loans are almost nil. Cash nearly doubled to Rs 4.91 crore. Fixed assets rose by about Rs 2.77 crore despite depreciation, so the company invested in the plant during the quarter. Current assets are 9.83 times current liabilities. Reserves still show an accumulated loss of Rs 8.59 crore, so net worth per share (Rs 90.78) is below the Rs 100 face value.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (quarter) | Rs 3.93 |
| EPS (annualised) | Rs 15.71 |
| Net worth per share | Rs 90.78 |
| Closing price | Rs 268.00 |
| P/E on annualised EPS | 17.06x |
| P/B | 2.95x |
| Current ratio | 9.83 |
At Rs 268 the share trades at 17.06 times annualised Q1 EPS and 2.95 times net worth per share. The report’s own P/E of 68.24 uses the quarter’s EPS. Last year’s dry quarters made losses, so annualised Q1 earnings overstate what a full year may bring.
Conclusion
Positives: return to profit, sales up 276.06% with both projects at full output, bank interest halved, long-term loan falling, and strong liquidity (current ratio 9.83).
Watch: administrative expenses up 66.48%, dry-season losses last year, an accumulated loss of Rs 8.59 crore, and a large balance of advances and receivables (Rs 45.59 crore).
Khanikhola is back in profit with both projects running at full capacity and a lighter interest bill. The dry-season quarters will show whether it can stay profitable for the full year and keep shrinking its accumulated loss.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

