













Makar Jitumaya Suri Hydropower Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with the audited year end (Ashad end 2083).
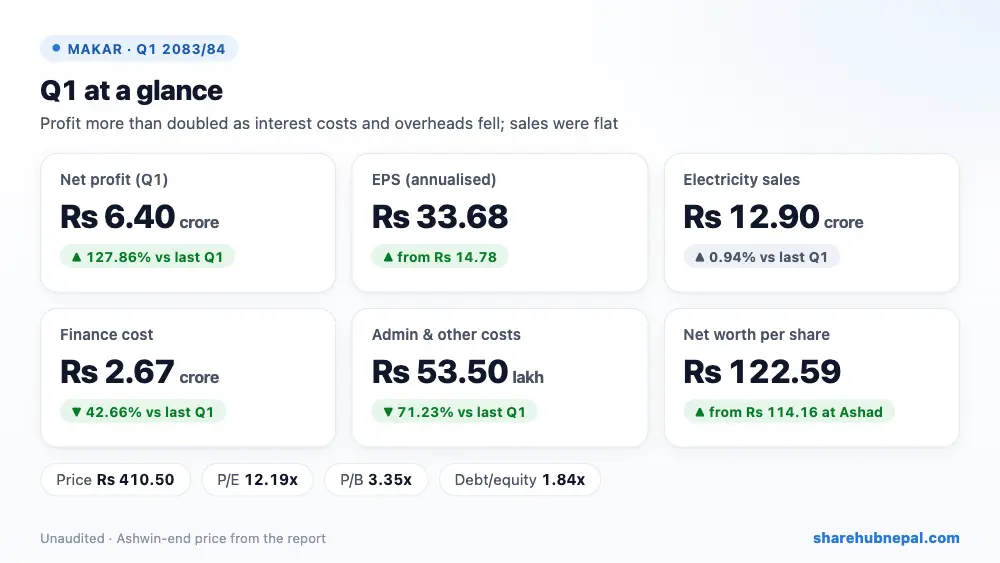
Summary
Makar Jitumaya Suri Hydropower earned a net profit of Rs 6.40 crore in the first quarter, up 127.86% from Rs 2.81 crore in the same quarter last year. Annualised EPS is Rs 33.68 (Rs 14.78 a year ago); EPS for the quarter alone is Rs 8.42.
Electricity sales were almost flat at Rs 12.90 crore (+0.94%), so the jump in profit came from lower costs, not more power sold. Finance cost fell 42.66% to Rs 2.67 crore and administrative and other expenses fell 71.23% to Rs 53.50 lakh. These two savings alone added about Rs 3.31 crore to profit.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Electricity sales | Rs 128,966,849 | Rs 127,764,239 | +0.94% |
| Gross profit | Rs 125,150,533 | Rs 123,511,165 | +1.33% |
| Profit from operation | Rs 90,659,596 | Rs 74,579,984 | +21.56% |
| Finance cost | Rs 26,659,289 | Rs 46,492,765 | −42.66% |
| Net profit | Rs 64,000,306 | Rs 28,087,219 | +127.86% |
| EPS (annualised) | Rs 33.68 | Rs 14.78 | – |
| Net worth per share | Rs 122.59 | Rs 108.02 | +13.49% |
| ROE (quarter, as reported) | 7.11% | 3.48% | +3.63 pts |
1. Where the profit came from
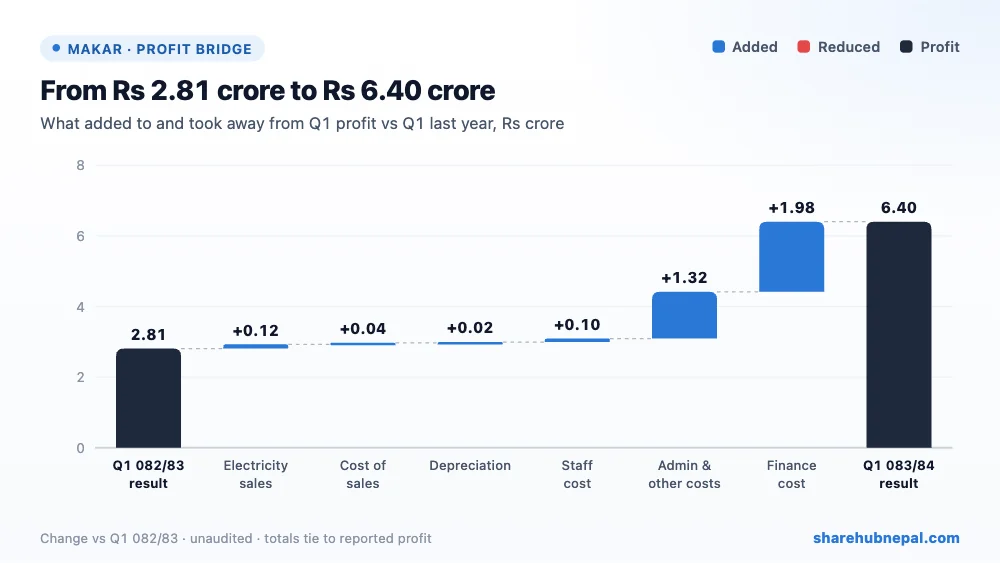
The bridge chart shows how Q1 profit moved from last year's Rs 2.81 crore to this year's Rs 6.40 crore. Every item helped:
- Finance cost (+Rs 1.98 crore): interest on the bank loan fell to Rs 2.67 crore from Rs 4.65 crore. The loan itself is 10.27% smaller than a year ago, so most of the saving comes from lower interest rates.
- Administrative and other costs (+Rs 1.32 crore): these fell to Rs 53.50 lakh from Rs 1.86 crore. Last year's figure looks unusually high, so this saving may not repeat every quarter.
- Electricity sales (+Rs 12.03 lakh): sales rose only 0.94%. Management credits a 3% rise in the selling rate, which suggests slightly less power was sold.
- Staff cost (+Rs 9.82 lakh): employee costs fell 18.41% to Rs 43.52 lakh.
- Cost of sales and depreciation (+Rs 6.48 lakh): both were a little lower than last year.
In plain terms: out of every Rs 100 of electricity sold, Rs 49.63 was left as net profit, against Rs 21.98 a year ago. Profit from operation now covers interest 3.40 times (1.60 times a year ago). The company paid no income tax (hydropower projects get a tax holiday) and booked no employee bonus provision this quarter; a bonus provision at year end would trim profit slightly.
2. Profit through the year
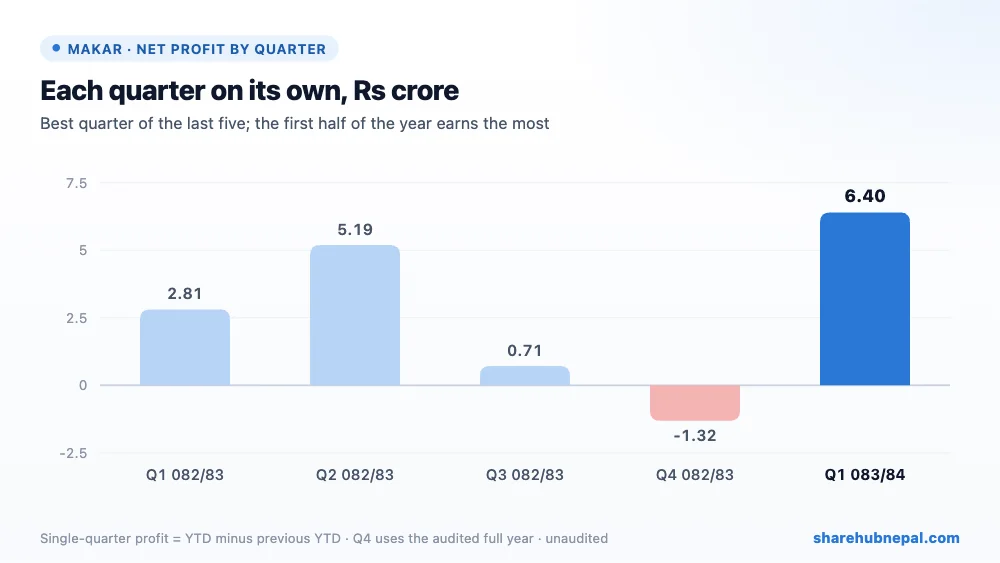
Looking at each quarter on its own (year-to-date profit minus the previous quarter's): Q1 2082/83: Rs 2.81 crore; Q2 2082/83: Rs 5.19 crore; Q3 2082/83: Rs 71.03 lakh; Q4 2082/83: −Rs 1.32 crore; Q1 2083/84: Rs 6.40 crore.
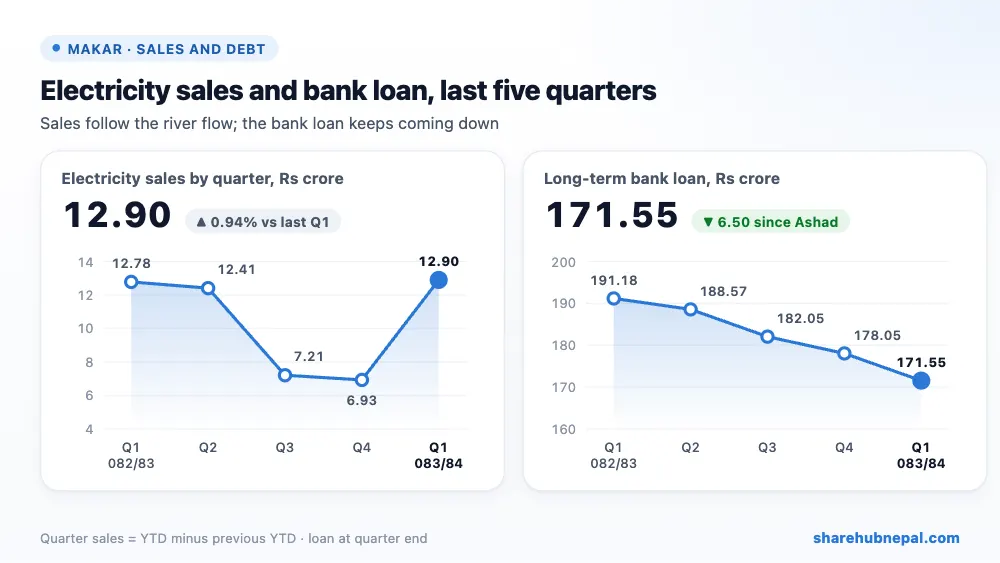
A run-of-river plant earns most in the wet months. Last year, quarterly sales were Rs 12.78 crore in Q1 and Rs 12.41 crore in Q2, but only Rs 7.21 crore in Q3 and Rs 6.93 crore in Q4 (dry season). That is why annualised EPS (Rs 33.68, simply Q1 x 4) overstates the full year: last year's annualised Q1 EPS was Rs 14.78, but the audited full-year EPS was Rs 9.73. Q4 2082/83 also uses the audited full-year figure, so it includes audit adjustments.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Long-term bank borrowing | Rs 1,715,473,983 | Rs 1,780,473,983 | −3.65% |
| Total equity | Rs 931,652,064 | Rs 867,651,757 | +7.38% |
| Total assets | Rs 2,664,491,497 | Rs 2,668,214,565 | −0.14% |
| Project asset (service concession) | Rs 2,518,272,315 | Rs 2,542,954,769 | −0.97% |
| Cash and cash equivalent | Rs 25,300,338 | Rs 29,088,894 | −13.02% |
| Other financial assets (mainly receivables) | Rs 111,224,175 | Rs 86,995,217 | +27.85% |
| Current liabilities | Rs 5,045,583 | Rs 7,159,710 | −29.53% |
The company repaid Rs 6.50 crore of its bank loan in the quarter, and the loan is down from Rs 1.91 arba a year ago. With equity growing from profit, debt to equity has fallen to 1.84 times from 2.05 at Ashad end and 2.33 a year ago. Almost all assets (94.5%) are the power plant itself, recorded as a service concession intangible asset and written off over the licence period. Short-term liquidity is comfortable: current assets of Rs 14.40 crore against current liabilities of only Rs 50.46 lakh though cash is modest and receivables (most likely from Nepal Electricity Authority) rose 27.85%.
4. Per-share figures and valuation
| Indicator | Value |
| EPS for the quarter | Rs 8.42 |
| EPS (annualised) | Rs 33.68 |
| EPS, FY 2082/83 (audited) | Rs 9.73 |
| Net worth per share | Rs 122.59 |
| Closing price, Ashwin end 2083 | Rs 410.50 |
| Price range during the quarter | Rs 390.20 – Rs 478.90 |
| P/E (annualised EPS) | 12.19x |
| P/E (FY 2082/83 EPS) | 42.19x |
| Price to book | 3.35x |
At Rs 410.50 the share looks cheap on annualised Q1 EPS (12.19 times), but that EPS comes from the best season of the year. On last year's full-year EPS the P/E is about 42 times, and the report's own P/E on quarterly EPS is 48.75. The price is 3.35 times net worth per share. Retained earnings of Rs 17.17 crore (about Rs 22.59 per share) give room for a dividend, subject to the board and the lenders.
Conclusion
Positives: profit up 127.86%, interest cost down 42.66%, overheads sharply lower, steady loan repayment with debt to equity down to 1.84x, net worth per share up to Rs 122.59, and healthy retained earnings.
Watch points: flat electricity sales, a strong season flattering annualised EPS, last year's weak dry-season quarters (including a Q4 loss after audit), rising receivables, no employee bonus provision yet, and a valuation that is high on full-year earnings.
Makar Jitumaya Suri is running efficiently and cutting its debt, which is lifting profit. Judge it on full-year earnings, not on the wet-season quarter alone.
Based on the company's unaudited first-quarter report. Figures may change after audit or regulator review. This is not investment advice.

