













Mandu Hydropower Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
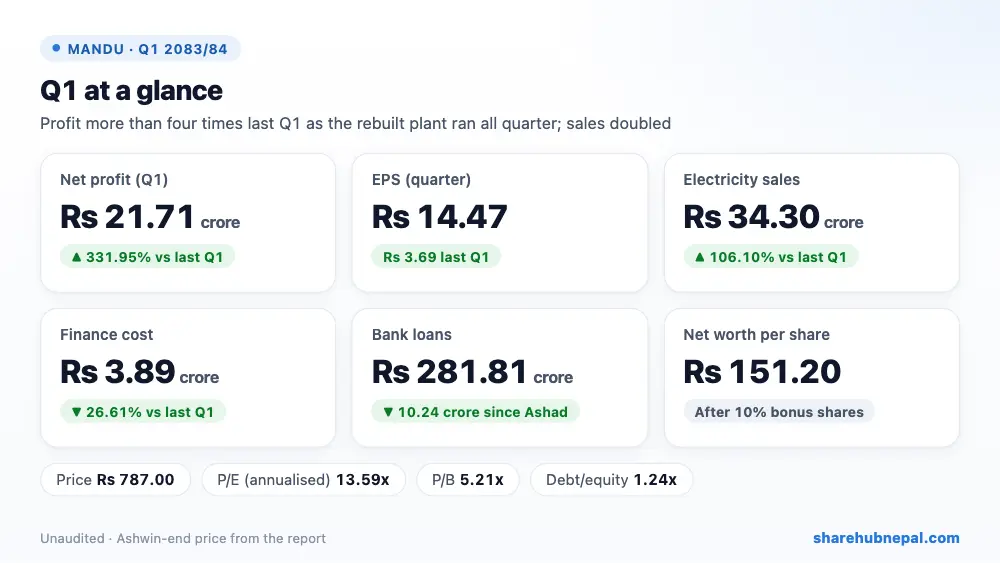
Mandu Hydropower earned a net profit of Rs 21.71 crore in the first quarter, more than four times the Rs 5.03 crore of the same quarter last year (+331.95%). EPS for the quarter is Rs 14.47; annualised it is Rs 57.89.
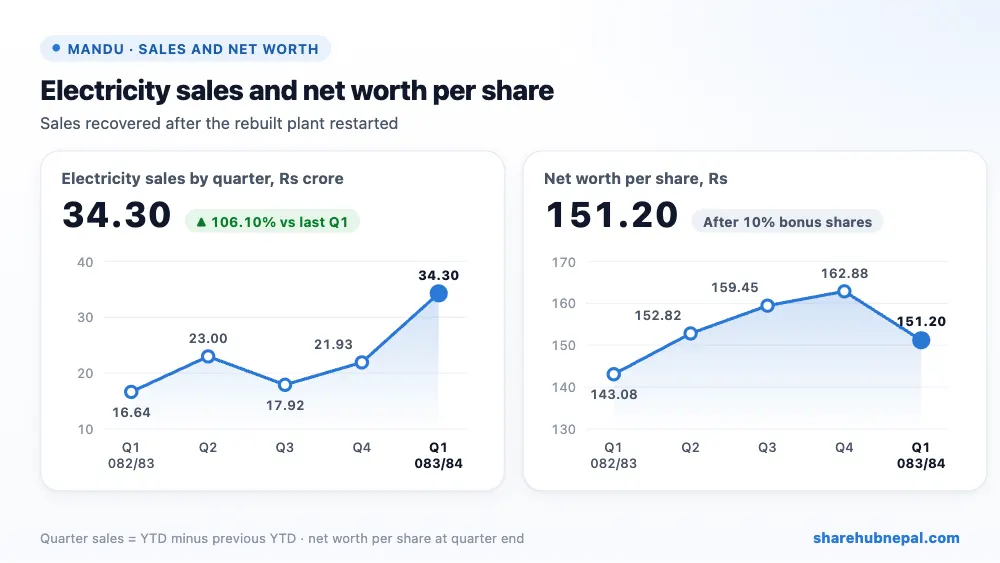
Last year’s Q1 was weak because the plant was still being rebuilt after the September 2024 flood: unit II restarted on 4 August 2025 and unit I on 27 September 2025. With both units running through this monsoon quarter, electricity sales doubled (+106.10%) to Rs 34.30 crore. The company is also adding 10 MW, which will take the project to 32 MW.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Electricity sales | Rs 342,994,605 | Rs 166,422,799 | +106.10% |
| Operating profit | Rs 313,933,229 | Rs 146,945,709 | +113.64% |
| Finance cost | Rs 38,865,929 | Rs 52,958,666 | −26.61% |
| Depreciation and amortisation | Rs 51,313,119 | Rs 42,186,175 | +21.63% |
| Net profit | Rs 217,086,305 | Rs 50,257,201 | +331.95% |
| EPS (quarter) | 14.47 | 3.69 | – |
| EPS (annualised) | 57.89 | 14.74 | – |
1. Where the profit came from
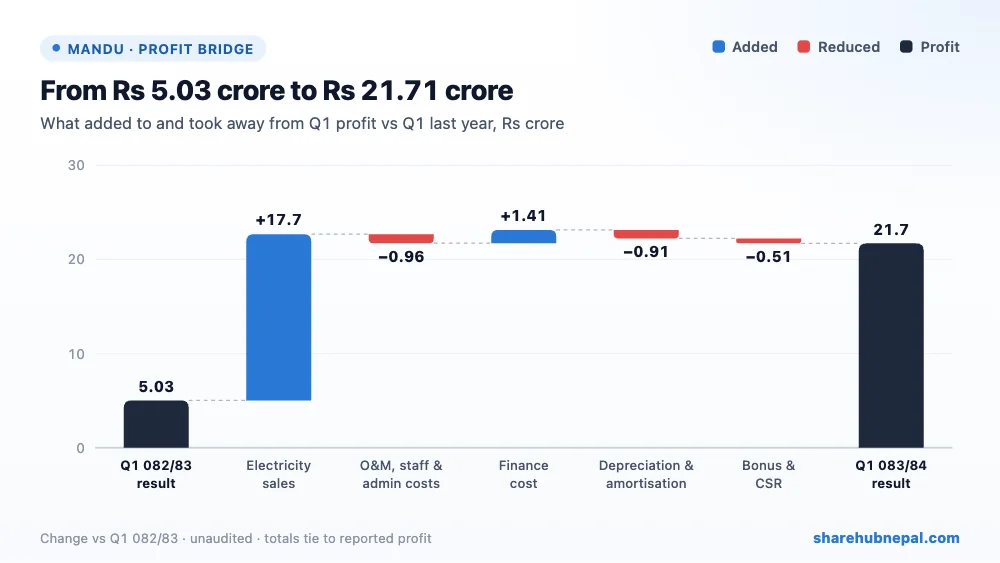
Compared with last year’s Q1, higher sales added Rs 17.66 crore and lower finance cost Rs 1.41 crore. Against this, depreciation and amortisation rose Rs 91.27 lakh as the rebuilt assets started to be written off, operation, staff and admin costs rose by a net Rs 95.84 lakh, and the staff bonus and CSR provisions, which are set as a share of profit, rose Rs 51.24 lakh.
2. Profit through the year
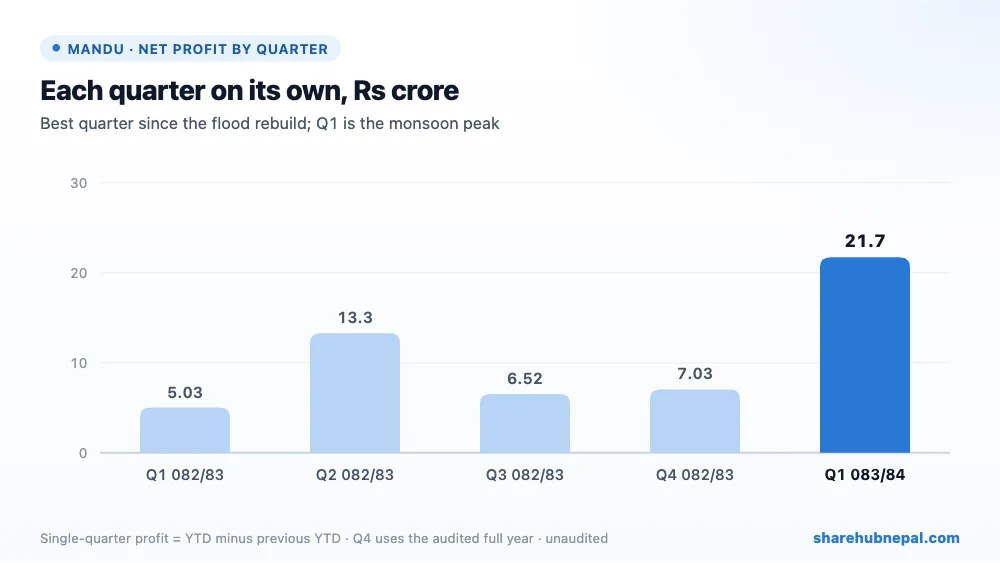
Based on Share Hub’s records, single-quarter profits in 2082/83 were Rs 5.03 crore in Q1 (plant restarting), Rs 13.28 crore in Q2, Rs 6.52 crore in Q3 and Rs 7.03 crore in Q4 (audited full year Rs 31.86 crore). This Q1 is the best quarter in the series. Q1 is the monsoon quarter, so later quarters usually earn less, and annualising Q1 (EPS Rs 57.89) overstates the full year.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Bank loans, long term | Rs 2,668,064,165 | Rs 2,400,504,165 | +11.15% |
| Bank loans, due within a year | Rs 150,000,000 | Rs 520,000,000 | −71.15% |
| Project (intangible) assets | Rs 4,570,157,920 | Rs 4,621,408,937 | −1.11% |
| Trade and other receivables | Rs 229,857,415 | Rs 166,085,918 | +38.40% |
| Total assets | Rs 5,259,361,579 | Rs 5,237,811,912 | +0.41% |
| Total equity | Rs 2,267,993,939 | Rs 2,221,108,321 | +2.11% |
Total bank loans fell Rs 10.24 crore in the quarter to Rs 281.81 crore. The loan due within a year fell from Rs 52 crore to Rs 15 crore while the long-term loan rose from Rs 240.05 crore to Rs 266.81 crore, so part of the short-term loan was moved to long term. Debt is 1.24 times equity. The 10% bonus shares (1,363,637 shares) approved by the AGM have been added to share capital (now Rs 150.00 crore); this is the main reason net worth per share is Rs 151.20, against Rs 162.88 at Ashad end. The current ratio is low at 0.82.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (quarter) | Rs 14.47 |
| EPS (annualised) | Rs 57.89 |
| Net worth per share | Rs 151.20 |
| Closing price, Ashwin end | Rs 787.00 |
| P/E on annualised EPS | 13.59x |
| P/E on FY 2082/83 EPS (23.36) | 33.69x |
| P/B | 5.21x |
| Current ratio | 0.82 |
At Rs 787 the share trades at 13.59 times annualised EPS and 5.21 times net worth per share. On last year’s full-year EPS (Rs 23.36) the P/E is 33.69, and the report’s own P/E of 54.38 uses the quarter’s EPS. The full-year picture will be clearer after the dry-season quarters and once the extra 10 MW is running.
Conclusion
Positives: profit up 331.95%, sales doubled with both units back after the flood rebuild, finance cost down 26.61%, bank loans down Rs 10.24 crore in the quarter, and 10 MW of extra capacity under way.
Watch: seasonal earnings (Q1 is the peak), a high price compared with book value (P/B 5.21), a low current ratio (0.82), and flood risk at the site, which has already stopped generation once.
Mandu Hydropower is back to full output after the flood and had an excellent monsoon quarter. The dry-season quarters and the progress of the 10 MW expansion will show how much of this it can sustain.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

