













Maikhola Hydropower Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
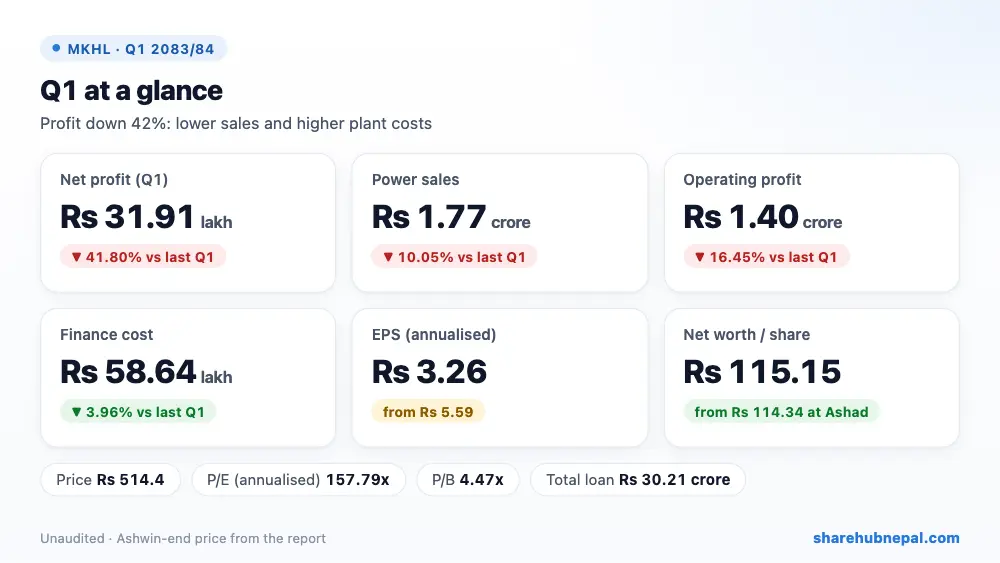
Summary
Maikhola Hydropower earned Rs 31.91 lakh in the first quarter, down 41.80% from Rs 54.83 lakh a year ago. Power sales fell 10.05% to Rs 1.77 crore while royalty and cost of sales rose 63.92% to Rs 31.17 lakh. Lower admin cost and slightly lower interest helped a little. The company says its Super Mai Cascade project is running. Annualised EPS is Rs 3.26 against Rs 5.59.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Revenue from sales | Rs 17,739,122 | Rs 19,721,015 | −10.05% |
| Cost of sales | Rs 3,116,510 | Rs 1,901,264 | +63.92% |
| Other income | Rs 6,745 | Rs 0 | – |
| Operating profit | Rs 13,953,735 | Rs 16,701,428 | −16.45% |
| Finance cost | Rs 5,864,247 | Rs 6,106,138 | −3.96% |
| Income tax | Rs 0 | Rs 0 | – |
| Net profit | Rs 3,191,461 | Rs 5,483,457 | −41.80% |
| EPS (annualised) | 3.26 | 5.59 | – |
| Net worth per share | 115.15 | 102.36 | – |
1. Where the profit came from
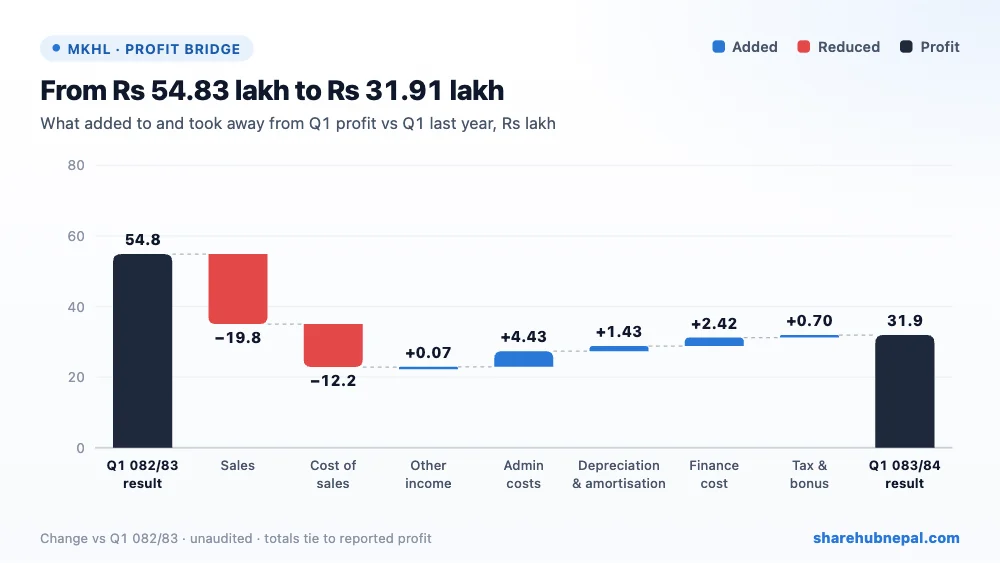
Lower sales took away Rs 19.82 lakh and higher plant costs Rs 12.15 lakh. Admin cost fell Rs 4.43 lakh, interest Rs 2.42 lakh and depreciation Rs 1.43 lakh. Interest and depreciation together still take more than 60% of sales.
2. Profit through the year
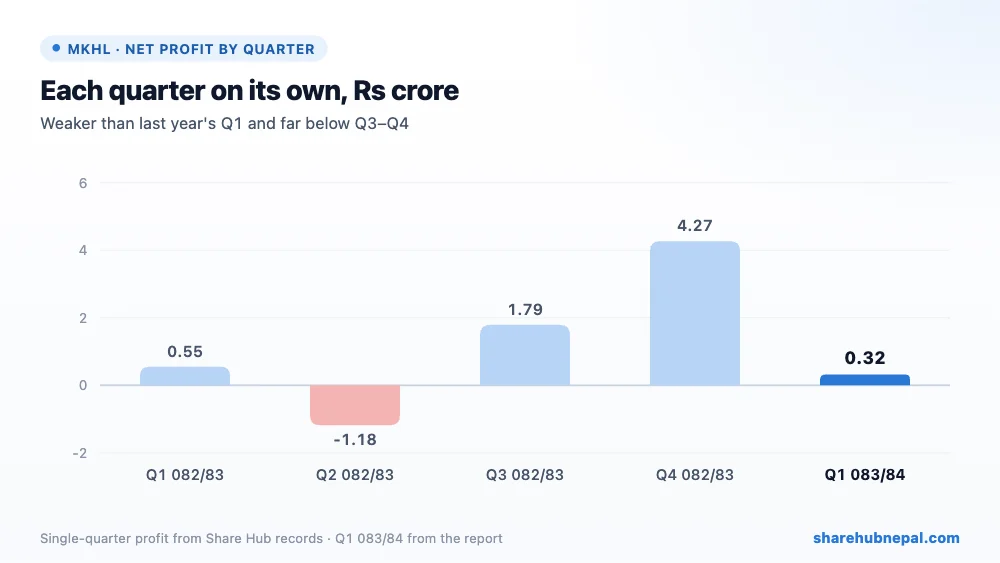
Profit by quarter (Share Hub records): Q1 082/83: Rs 54.83 lakh, Q2 082/83: −Rs 1.18 crore, Q3 082/83: Rs 1.79 crore, Q4 082/83: Rs 4.27 crore, Q1 083/84: Rs 31.91 lakh. Last year profit was lumpy: a loss in Q2 and a large Q4 profit helped by Rs 18.06 crore of non-operating income. FY 2082/83 EPS was Rs 13.83, mostly from that one-off income.
3. Debt and balance sheet
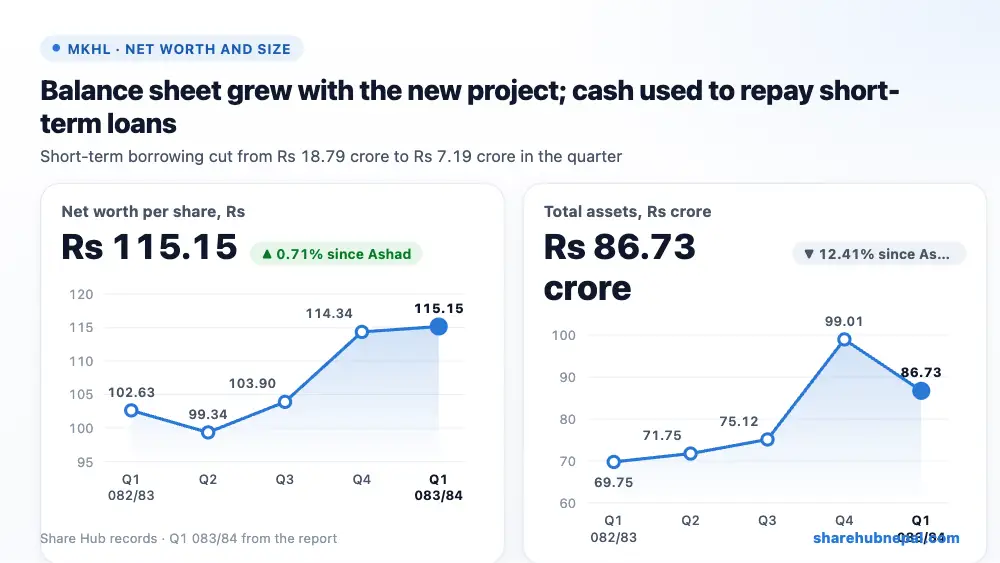
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Total assets | Rs 867,250,848 | Rs 990,144,055 | −12.41% |
| Total equity | Rs 451,573,046 | Rs 448,381,585 | +0.71% |
| Long-term borrowings | Rs 230,215,197 | Rs 230,215,197 | +0.00% |
| Current borrowings | Rs 71,880,400 | Rs 187,880,453 | −61.74% |
| Cash and equivalents | Rs 33,687,758 | Rs 152,661,370 | −77.93% |
Net fixed assets are Rs 67.28 crore against Rs 52.87 crore a year ago, as the Super Mai Cascade project was added. In the quarter the company used cash (down from Rs 15.27 crore to Rs 3.37 crore) to cut short-term borrowing from Rs 18.79 crore to Rs 7.19 crore. The long-term loan is Rs 23.02 crore. Payables of Rs 11.34 crore and short-term loans make current liabilities 3.4 times current assets (current ratio 0.29).
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised) | Rs 3.26 |
| Net worth per share | Rs 115.15 |
| Market price (Ashwin end) | Rs 514.4 |
| P/E (annualised) | 157.79x |
| P/B | 4.47x |
At the Ashwin-end price of Rs 514.4, the share trades at 157.79 times annualised EPS and 4.47 times net worth per share. The price is very high for current earnings; it is betting on the new project lifting profit.
Conclusion
Positives: short-term loan cut sharply, lower admin and interest cost, new project in operation, net worth per share up to Rs 115.15.
Watch: profit down 42% with lower sales in the peak season, very low current ratio, last year's profit depended on one-off income, and a P/E of 158x.
A weak quarter. The investment case rests on the Super Mai Cascade project adding meaningful sales, which this quarter does not yet show.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

