













National Hydro Power Co. Ltd – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
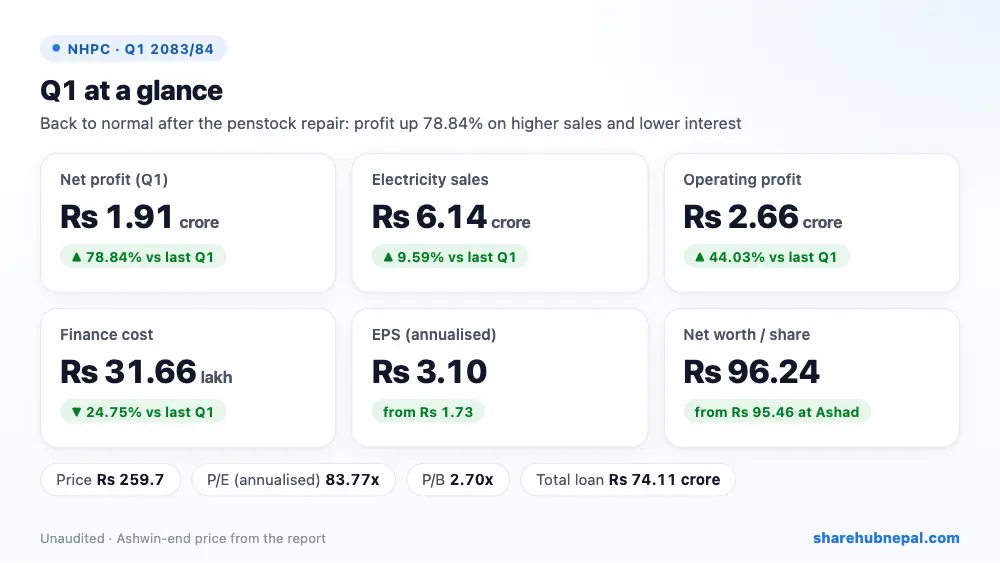
National Hydro Power earned a net profit of Rs 1.91 crore in the first quarter of FY 2083/84, up 78.84% from Rs 1.07 crore a year ago. Its Indrawati III plant, hit by a penstock burst in Chaitra 2082, has been generating normally since 29 Ashad 2083 after repairs, so sales rose 9.59% to Rs 6.14 crore. Lower cost of sales and a 24.75% drop in finance cost added to the gain. Annualised EPS is still small at Rs 3.10 and net worth per share is Rs 96.24, below the Rs 100 face value. The company has claimed Rs 3.97 crore for the damage and Rs 4.66 crore for loss of profit from its insurer.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Revenue from operation | Rs 61,355,013 | Rs 55,988,013 | +9.59% |
| Cost of sales | Rs 17,245,953 | Rs 19,334,959 | −10.80% |
| Staff and admin expenses | Rs 5,272,379 | Rs 5,493,762 | −4.03% |
| Depreciation and amortisation | Rs 12,209,693 | Rs 12,674,951 | −3.67% |
| Profit from operation | Rs 26,626,989 | Rs 18,486,762 | +44.03% |
| Loss on investments (FVTPL) and other income | −Rs 351,692 | −Rs 1,292,365 | +72.79% |
| Finance costs | Rs 3,165,601 | Rs 4,206,617 | −24.75% |
| Staff bonus and CSR | Rs 693,291 | Rs 367,562 | +88.62% |
| Income tax (net of deferred) | Rs 3,320,963 | Rs 1,940,193 | +71.17% |
| Net profit | Rs 19,095,442 | Rs 10,677,604 | +78.84% |
| EPS (annualised) | 3.1 | 1.73 | – |
| Net worth per share | 96.24 | 96.79 | – |
1. Where the profit came from
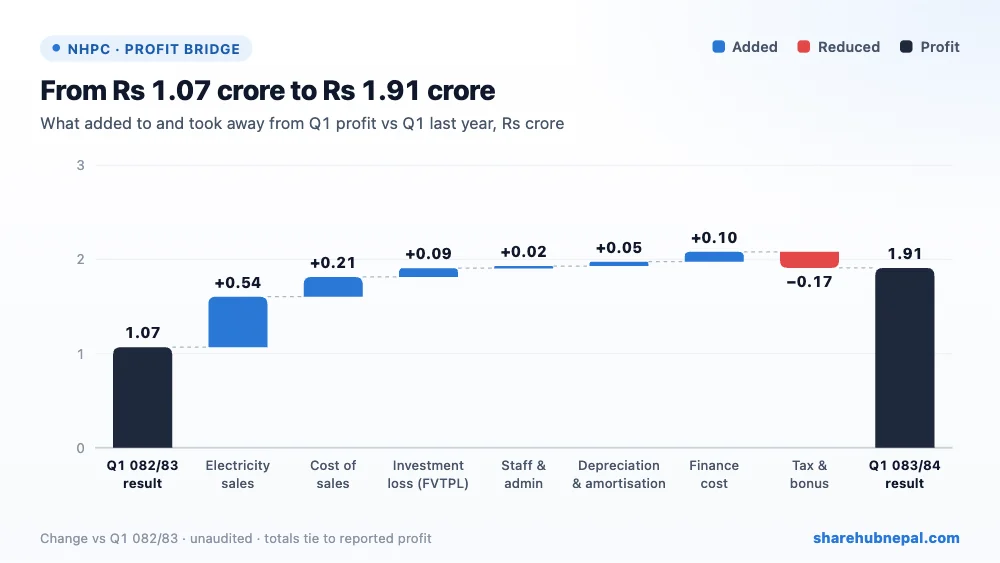
Sales of Rs 6.14 crore less cost of sales of Rs 1.72 crore gave a gross profit of Rs 4.41 crore (Rs 3.67 crore). Depreciation and amortisation were Rs 1.22 crore and staff and admin costs Rs 52.72 lakh, leaving operating profit of Rs 2.66 crore, up 44.03%. A Rs 3.52 lakh loss on share investments (Rs 12.95 lakh last year) and finance cost of Rs 31.66 lakh brought profit before bonus and tax to Rs 2.31 crore. After bonus and CSR of Rs 6.93 lakh and net tax of Rs 33.21 lakh, net profit was Rs 1.91 crore.
2. Profit through the year
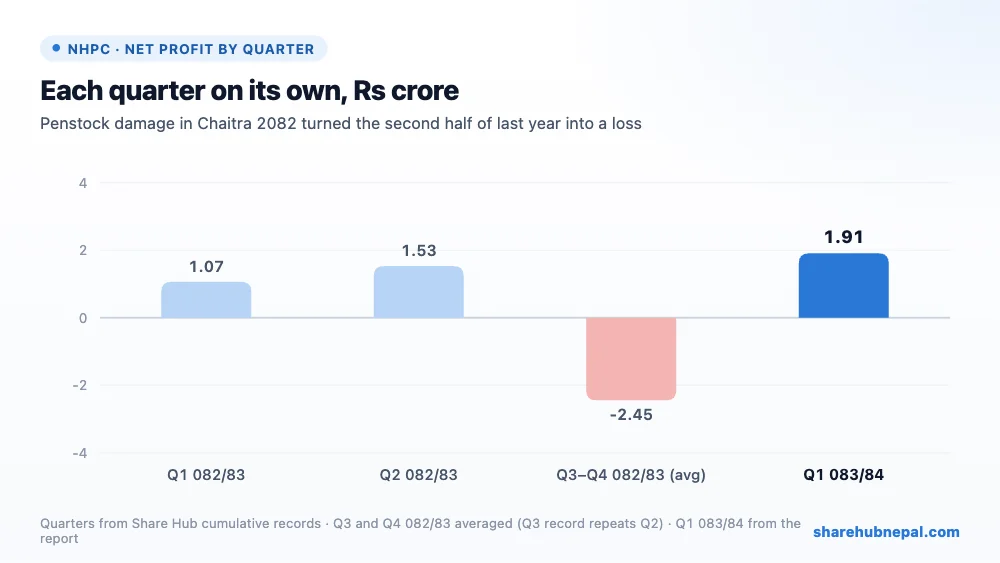
Profit by quarter (Share Hub cumulative records, split into quarters; Q3 record repeats Q2, so Q3–Q4 are averaged): Q1 082/83: Rs 1.07 crore, Q2 082/83: Rs 1.53 crore, Q3–Q4 082/83 (avg): −Rs 2.45 crore, Q1 083/84: Rs 1.91 crore. Last year the first half was profitable, but the penstock burst on 10 Chaitra 2082 stopped the plant and the year ended with a loss of Rs 2.29 crore (EPS Rs −0.93). Share Hub's Q3 record repeats the Q2 profit, so Q3 and Q4 are shown as an average.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Total assets | Rs 3,483,405,271 | Rs 3,483,288,151 | +0.00% |
| Total equity | Rs 2,374,367,645 | Rs 2,355,272,202 | +0.81% |
| Project under development (Lower Indrawati) | Rs 1,581,153,436 | Rs 1,565,701,758 | +0.99% |
| Investments (equity + property) | Rs 750,917,165 | Rs 751,268,857 | −0.05% |
| Long-term borrowings | Rs 610,670,826 | Rs 607,242,154 | +0.56% |
| Current borrowings | Rs 130,433,032 | Rs 135,111,176 | −3.46% |
| Cash and equivalents | Rs 1,126,692 | Rs 1,724,757 | −34.68% |
| Current liabilities | Rs 342,307,311 | Rs 362,982,367 | −5.70% |
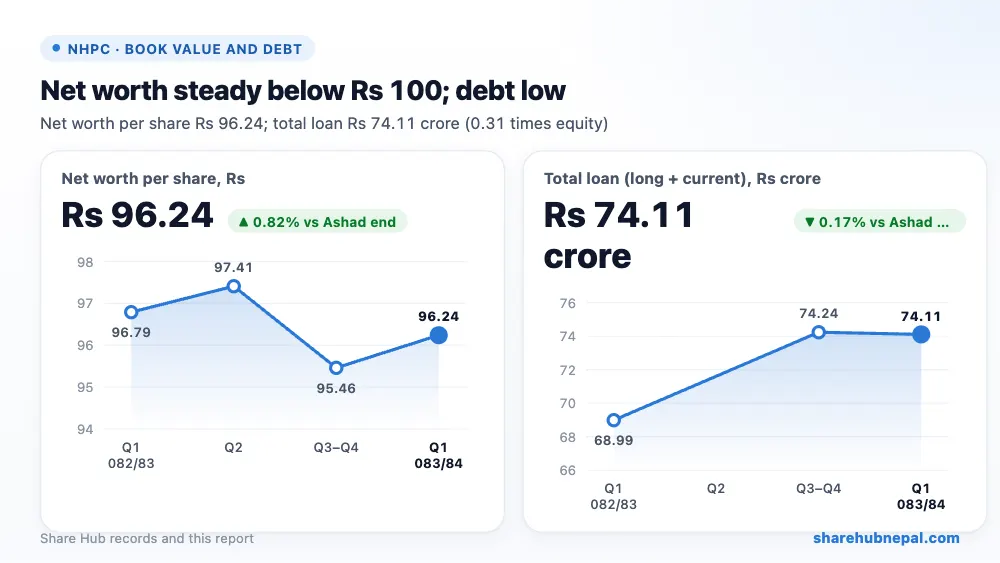
Debt is low: total borrowings are Rs 74.11 crore, only 0.31 times equity of Rs 2.37 arba. Much of the balance sheet is in new projects and investments: the 4.5 MW Lower Indrawati project under construction (Rs 1.58 arba, with a bank consortium loan) and Rs 68.31 crore of shares, mostly in its subsidiary Lower Irkhuwa Hydro Power, which started commercial operation in Chaitra 2082. The weak spot is liquidity: cash is only Rs 11.27 lakh and current liabilities of Rs 34.23 crore are far above current assets of Rs 12.79 crore.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised) | Rs 3.10 |
| Net worth per share | Rs 96.24 |
| Market price (Ashwin end) | Rs 259.7 |
| P/E (annualised) | 83.77x |
| P/B | 2.70x |
At the Ashwin-end price of Rs 259.7, the share trades at 83.77 times annualised EPS and 2.70 times net worth per share. The P/E is very high because earnings are small compared with the large capital base; the share trades at about 2.7 times net worth per share. The value depends heavily on the new projects and the subsidiary.
Conclusion
Positives: the plant is back to normal after repair, profit up 78.84%, low debt, insurance claims of Rs 8.63 crore lodged, a subsidiary plant already running, and a second project under construction.
Watch: earnings are small (EPS Rs 3.10 annualised), net worth per share is below Rs 100, cash is almost nil with current liabilities well above current assets, insurance claims are not yet settled, Rs 15.22 lakh of share calls are unpaid, and a case filed by the company is pending in the Kathmandu District Court.
Watch insurance claim settlement, progress on Lower Indrawati, and the subsidiary's results.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

