













Peoples Hydropower Company Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
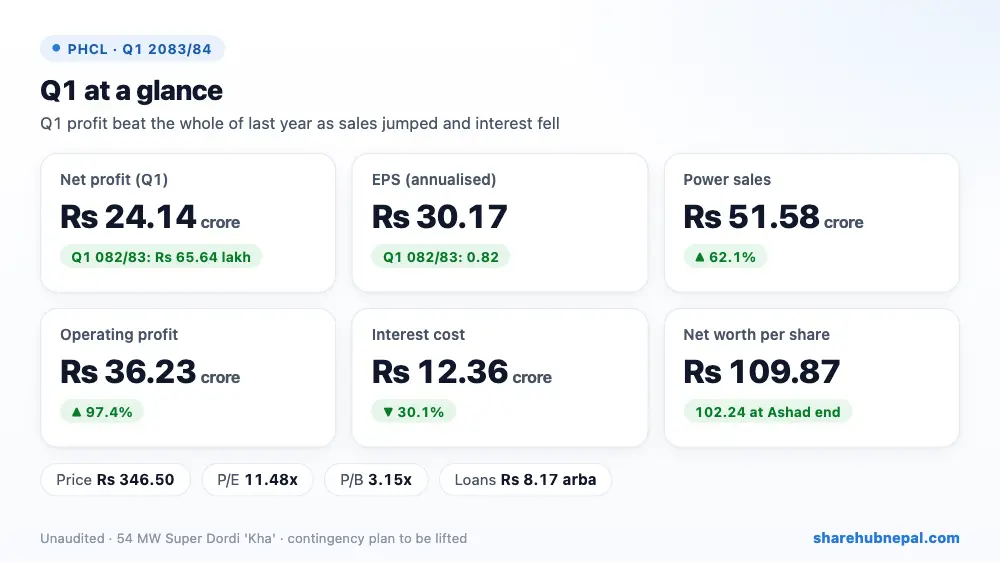
Summary
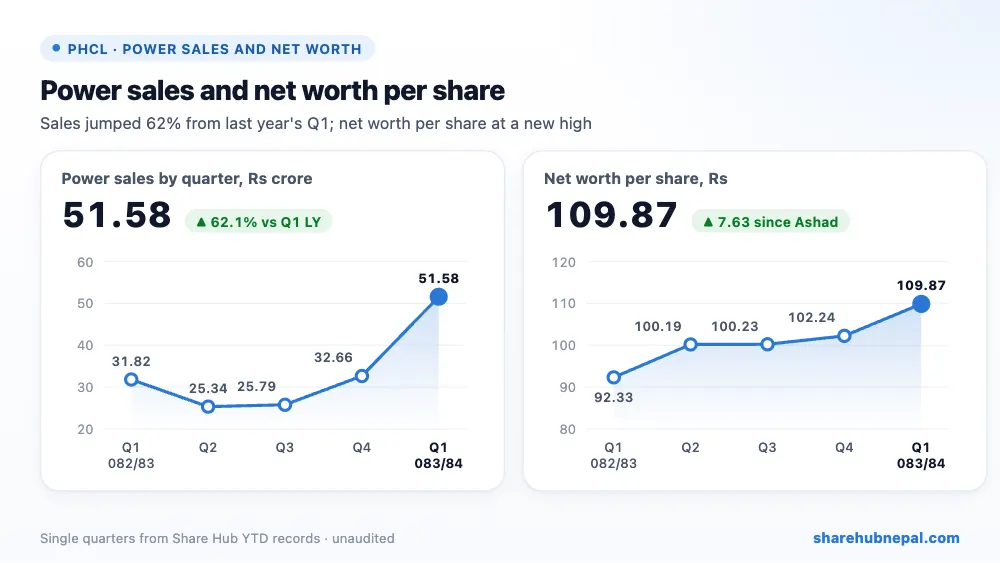
Peoples Hydropower earned a net profit of Rs 24.14 crore in the first quarter of 2083/84, against only Rs 65.64 lakh in the same quarter last year — and more than three times its profit for the whole of 2082/83 (Rs 7.14 crore). Annualised EPS is Rs 30.17 (0.82 a year ago) and net worth per share rose to Rs 109.87.
Electricity sales from the 54 MW Super Dordi 'Kha' plant rose 62.12% to Rs 51.58 crore, and finance cost fell 30.14% to Rs 12.36 crore. Until now the plant has sold power under an NEA 'contingency plan' because NEA's Marsyangdi corridor 220 kV line was late. The Bharatpur–Markichok line is now complete and connected to the national grid, and NEA has asked the Electricity Regulatory Commission to end the contingency arrangement; the company expects income to rise further once the PPA is amended.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Revenue from sale of electricity | Rs 515,848,725 | Rs 318,185,724 | +62.12% |
| Cost of sales | Rs 126,874,171 | Rs 115,969,719 | +9.40% |
| Administrative expenses | Rs 26,697,294 | Rs 18,674,164 | +42.96% |
| Operating profit | Rs 362,337,888 | Rs 183,576,657 | +97.38% |
| Finance cost | Rs 123,622,051 | Rs 176,961,407 | −30.14% |
| Other income (loss) | Rs 2,673,464 | −Rs 51,640 | Turned to profit |
| Net profit | Rs 241,389,301 | Rs 6,563,610 | +3577.69% |
1. Where the profit came from
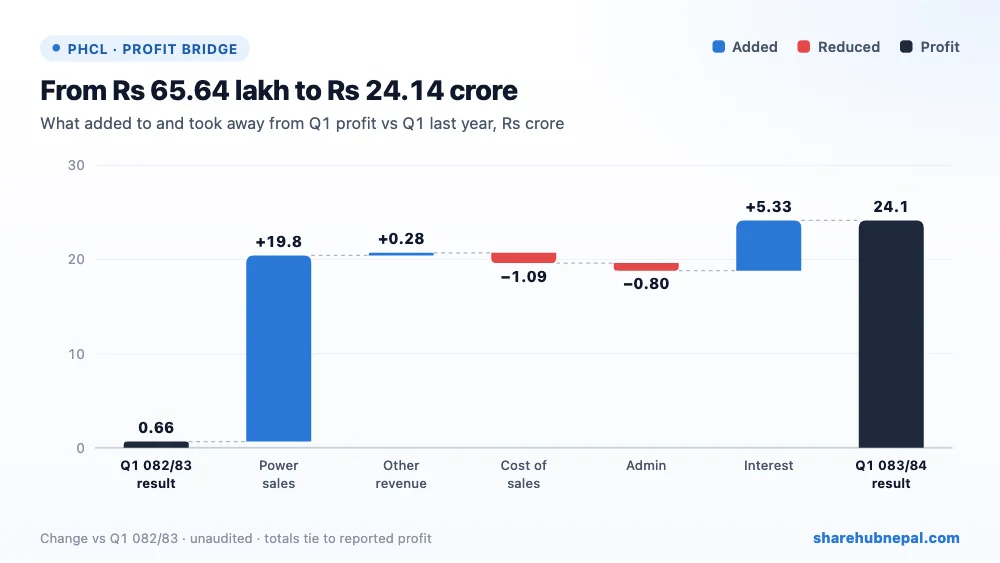
Against Q1 last year, higher power sales added Rs 19.77 crore and lower interest Rs 5.33 crore. Higher cost of sales took away Rs 1.09 crore and higher admin cost Rs 80.23 lakh. Net: profit up Rs 23.48 crore.
2. Profit through the year
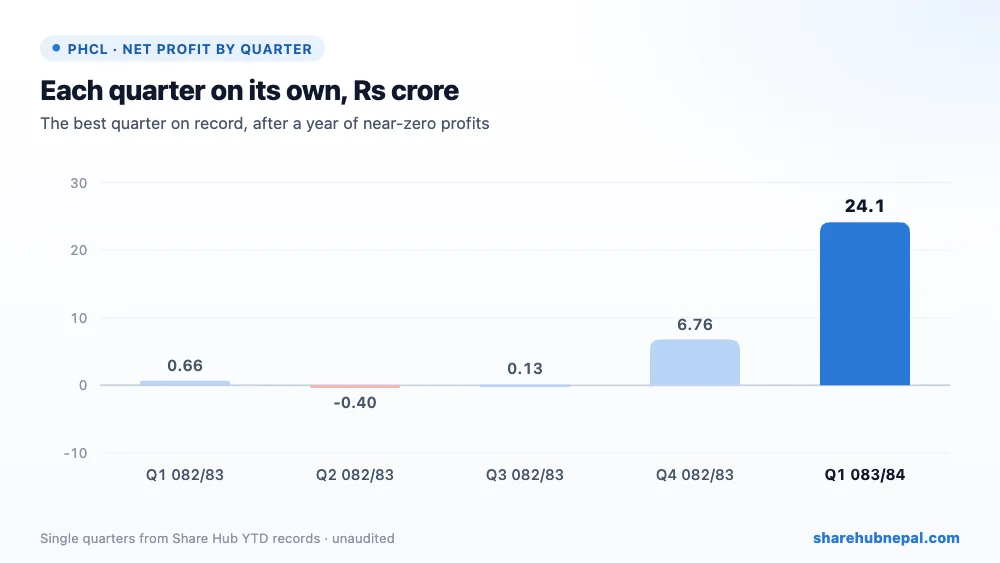
Last year PHCL earned almost nothing for three quarters (Rs 65.64 lakh in Q1, a small loss in Q2, Rs 12.78 lakh in Q3) before a better Q4 (Rs 6.76 crore). This Q1 is by far its best quarter. Part of the jump is the monsoon, so the annualised EPS of 30.17 overstates the year, but lower interest and the end of the contingency plan could keep later quarters well above last year's.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Project (intangible) assets | Rs 10,172,718,748 | Rs 10,262,427,987 | −0.87% |
| Non-current financial assets | Rs 555,576,164 | Rs 537,526,290 | +3.36% |
| Trade and other receivables | Rs 359,245,889 | Rs 248,358,776 | +44.65% |
| Cash and cash equivalents | Rs 449,137,172 | Rs 300,268,534 | +49.58% |
| Long-term loans | Rs 8,168,664,974 | Rs 8,169,108,954 | −0.01% |
| Total equity | Rs 3,515,863,618 | Rs 3,271,800,853 | +7.46% |
PHCL carries a big loan of Rs 8.17 arba, 2.32 times equity, against project assets of Rs 10.17 arba. Liquidity is very strong: cash rose to Rs 44.91 crore and the liquidity ratio is 20.16. NEA receivables rose to Rs 35.92 crore. The company is studying Ingkhu Khola (21.4 MW, 50% stake) and Middle Ingkhu (27.9 MW, 25%) in Solukhumbu, has invested in founder shares of North Summit Hydro (Nyadi Phidi, 21.4 MW) and Janata Agro and Forestry, and owns the 57 MW Himchuli Dordi project, which still has no PPA after years. A 1:1 right share (approved by the ERC on 2082/12/05) is waiting for SEBON approval and is meant to cut the loan.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised, report) | Rs 30.17 |
| EPS (quarter, derived) | Rs 7.54 |
| Net worth per share | Rs 109.87 |
| Market price (Q1 close) | Rs 346.50 |
| P/E (report) | 11.48x |
| P/B | 3.15x |
| Liquidity ratio | 20.16 |
| Debt to equity | 2.32x |
The Q1 closing price was Rs 346.50 (low Rs 292). The P/E is 11.48 on the annualised Q1 EPS — low for a hydro stock, but Q1 is the best season — and the price is 3.15 times net worth per share. On last year's EPS of 2.23 the P/E would be over 150, so the price depends on the new, higher earnings lasting.
Conclusion
Positives: a record quarter, sales up 62%, interest down 30%, the transmission line now complete, very strong liquidity, and new projects in the pipeline.
Watch: the large loan, when the ERC lifts the contingency plan and the PPA is amended, the 57 MW Himchuli Dordi project still without a PPA, the 1:1 right share (more shares), and rising maintenance costs from the stronger foreign currency.
PHCL has turned a corner: Q1 alone beat last year's full profit. If the contingency plan is lifted and interest keeps falling, 2083/84 could be its best year so far.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

