













Sagar Distillery Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
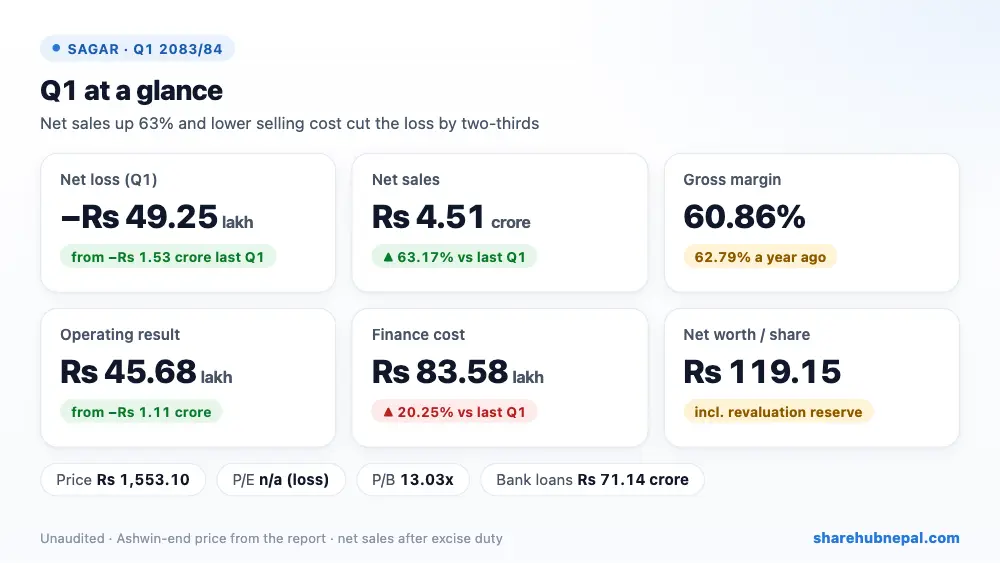
Summary
Sagar Distillery, a liquor maker, posted a net loss of Rs 49.25 lakh in the first quarter of FY 2083/84, much smaller than the loss of Rs 1.53 crore a year ago (−67.86%). Quarter EPS is Rs −0.68.,Gross revenue rose 85.07% to Rs 11.10 crore; after excise duty of Rs 6.59 crore, net sales were Rs 4.51 crore (+63.17%). Gross profit rose 58.17% to Rs 2.74 crore, though the gross margin dipped to 60.86% from 62.79%. Staff cost fell 15.74% and selling cost 22.87%, so the business made an operating profit of Rs 45.68 lakh before depreciation and interest, against a loss of Rs 1.11 crore last year. Finance cost of Rs 83.58 lakh (+20.25%) and depreciation pushed the quarter back into a loss.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Gross revenue | Rs 110,986,536 | Rs 59,970,840 | +85.07% |
| Excise duties | Rs 65,927,336 | Rs 32,356,530 | +103.75% |
| Net sales revenue | Rs 45,059,199 | Rs 27,614,310 | +63.17% |
| Cost of goods sold | Rs 17,635,764 | Rs 10,276,143 | +71.62% |
| Gross profit | Rs 27,423,435 | Rs 17,338,167 | +58.17% |
| Other operating income | Rs 3,862,604 | Rs 2,778,026 | +39.04% |
| Employee expenses | Rs 12,637,540 | Rs 14,998,363 | −15.74% |
| Administrative expenses | Rs 3,623,912 | Rs 2,676,571 | +35.39% |
| Selling and distribution | Rs 10,456,540 | Rs 13,556,806 | −22.87% |
| Operating result (before depreciation and interest) | Rs 4,568,046 | −Rs 11,115,547 | Turned to profit |
| Depreciation | Rs 2,820,570 | Rs 2,502,610 | +12.71% |
| Finance costs | Rs 8,358,340 | Rs 6,950,864 | +20.25% |
| Deferred tax (credit) | −Rs 1,685,770 | −Rs 5,245,100 | +67.86% |
| Net profit / (loss) | −Rs 4,925,093 | −Rs 15,323,920 | +67.86% |
| EPS (quarter) | -0.68 | -2.11 | – |
1. Where the profit came from
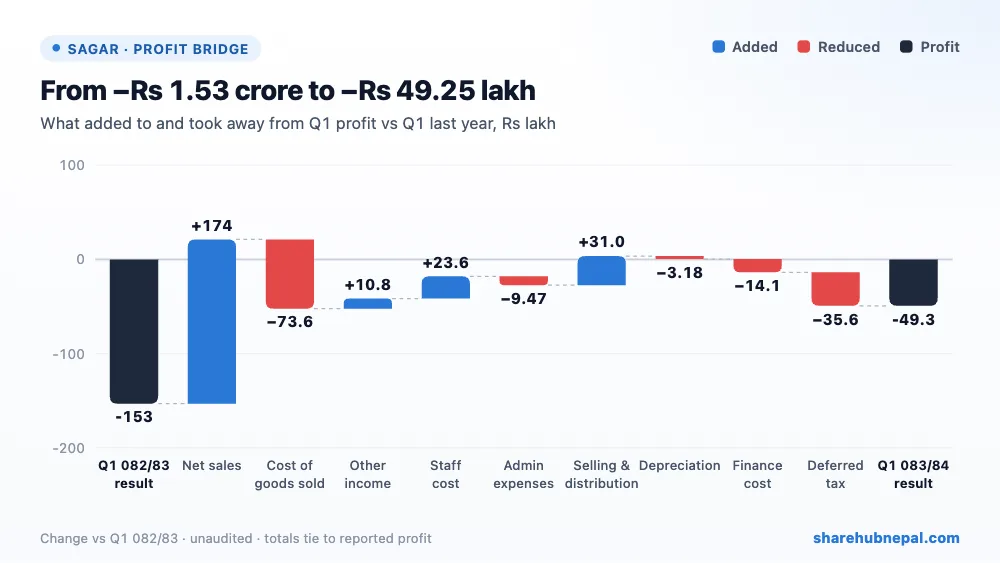
Higher net sales added Rs 1.74 crore and lower staff and selling costs saved Rs 54.61 lakh, while cost of goods sold took Rs 73.60 lakh more. Interest rose by Rs 14.07 lakh because of the new term loan for the malt spirit plant. The deferred tax credit was smaller (Rs 16.86 lakh vs Rs 52.45 lakh), which reduced the improvement.
2. Profit through the year
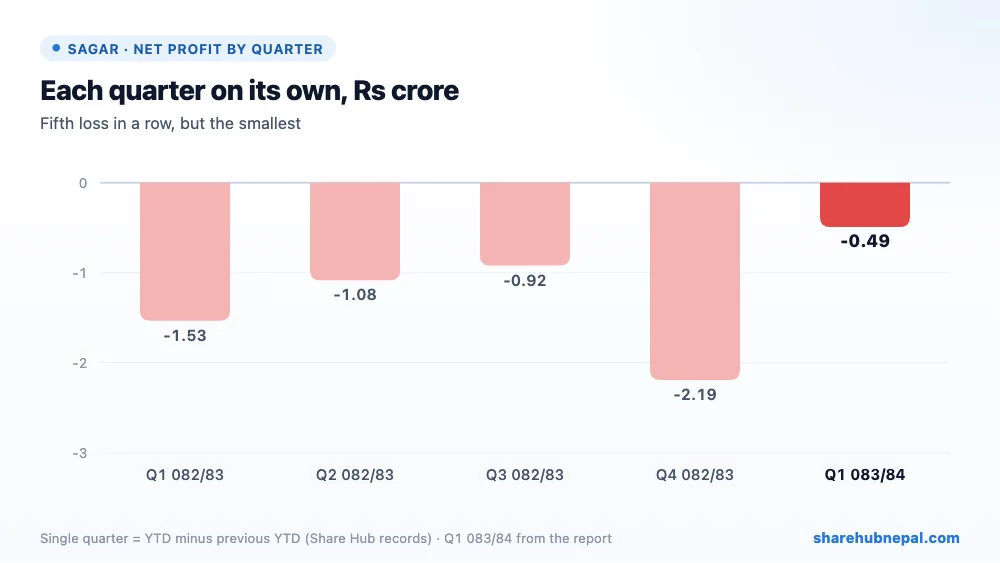
Sagar has made a loss in every quarter on record: last year Rs 1.53 crore in Q1, Rs 1.08 crore in Q2, Rs 91.99 lakh in Q3 and Rs 2.19 crore in Q4 (FY loss Rs 5.73 crore, EPS Rs −7.89). This quarter's loss is the smallest so far.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Property, plant and equipment | Rs 504,808,218 | Rs 496,469,998 | +1.68% |
| Capital work in progress | Rs 245,384,224 | Rs 201,474,815 | +21.79% |
| Trade receivables | Rs 583,907,614 | Rs 583,589,376 | +0.05% |
| Cash and cash equivalents | Rs 1,754,525 | Rs 26,537,230 | −93.39% |
| Bank borrowings (long + short) | Rs 711,373,599 | Rs 590,452,345 | +20.48% |
| Total equity | Rs 865,031,765 | Rs 870,931,138 | −0.68% |
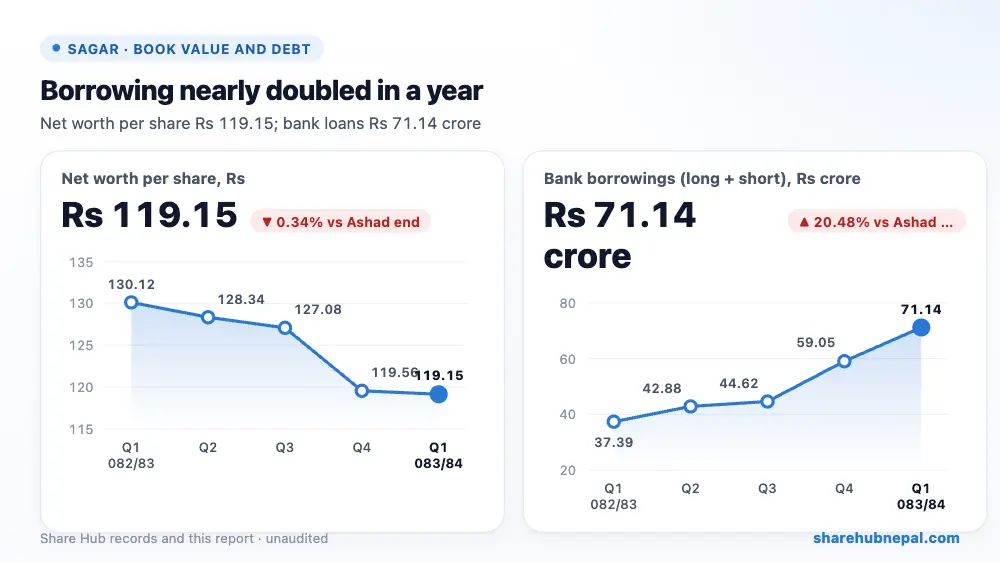
The company is building a malt spirit plant: capital work in progress rose to Rs 24.54 crore and long-term bank borrowing to Rs 41.15 crore, so total bank loans are Rs 71.14 crore, up from Rs 37.39 crore a year ago. Cash is very low at Rs 17.55 lakh, and trade receivables of Rs 58.39 crore are about 13 times quarterly net sales, so collecting from distributors is a key problem (the company says it is tightening credit control). Net worth per share of Rs 119.15 includes a Rs 19.35 crore revaluation reserve; without it, it would be about Rs 92.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (quarter, report) | Rs -0.68 |
| Net worth per share (incl. revaluation) | Rs 119.15 |
| Market price (Ashwin end) | Rs 1,553.10 |
| P/B (report) | 13.03x |
| Current ratio (report) | 2.18 |
At Rs 1,553.10 the share trades at 13.03 times net worth per share (report), with no profit to support it. The price reflects hopes for the new plant and brands, not current earnings.
Conclusion
Positives: net sales up 63.17%, loss cut by two-thirds, a positive operating result before depreciation and interest, lower staff and selling costs, a growing premium brand range, and no legal cases.
Watch: still loss-making, receivables of Rs 58.39 crore against very little cash, bank loans nearly doubled in a year, finance cost rising, net worth helped by a revaluation reserve, and a shrinking liquor market (outmigration, health awareness).
Watch whether sales growth continues, how fast receivables are collected, and when the malt spirit plant starts adding to profit.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

