













Sanima Mai Hydropower Ltd. – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
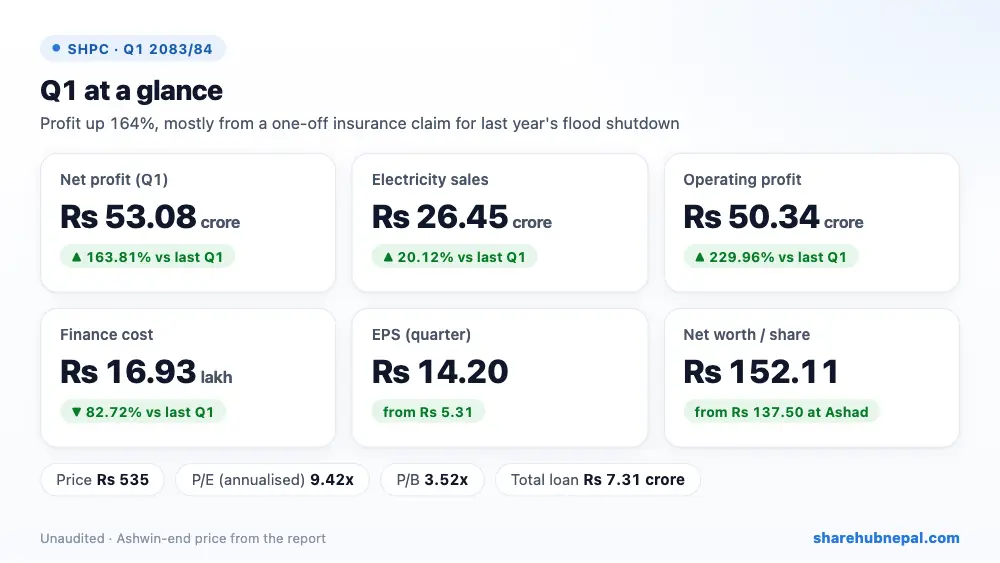
Sanima Mai Hydropower earned Rs 53.08 crore in the first quarter, up 163.81% from Rs 20.12 crore a year ago. Most of the jump is one-off: the company booked Rs 28.71 crore of insurance claim for the loss of profit and property when floods shut its plants from 18 Ashwin to 10 Falgun 2082, and a Rs 2.67 crore cash dividend from Sanima Middle Tamor. Electricity sales rose 20.12% to Rs 26.45 crore and its share of associates' profit rose 37.87% to Rs 10.32 crore. Taking out the insurance claim (after 12.5% tax), profit would be roughly Rs 27.96 crore, still about 39% higher than last year.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Revenue from sales | Rs 264,511,297 | Rs 220,207,497 | +20.12% |
| Cost of sales | Rs 27,233,511 | Rs 23,195,011 | +17.41% |
| Other income | Rs 313,844,515 | Rs 1,068,736 | +29265.95% |
| Operating profit | Rs 503,350,876 | Rs 152,547,616 | +229.96% |
| Finance cost | Rs 1,693,249 | Rs 9,796,986 | −82.72% |
| Share of associates' profit | Rs 103,156,078 | Rs 74,822,864 | +37.87% |
| Income tax | Rs 74,096,763 | Rs 17,426,691 | +325.19% |
| Net profit | Rs 530,828,981 | Rs 201,215,539 | +163.81% |
| EPS (quarter) | 14.2 | 5.31 | – |
| Net worth per share | 152.11 | 135.13 | – |
1. Where the profit came from
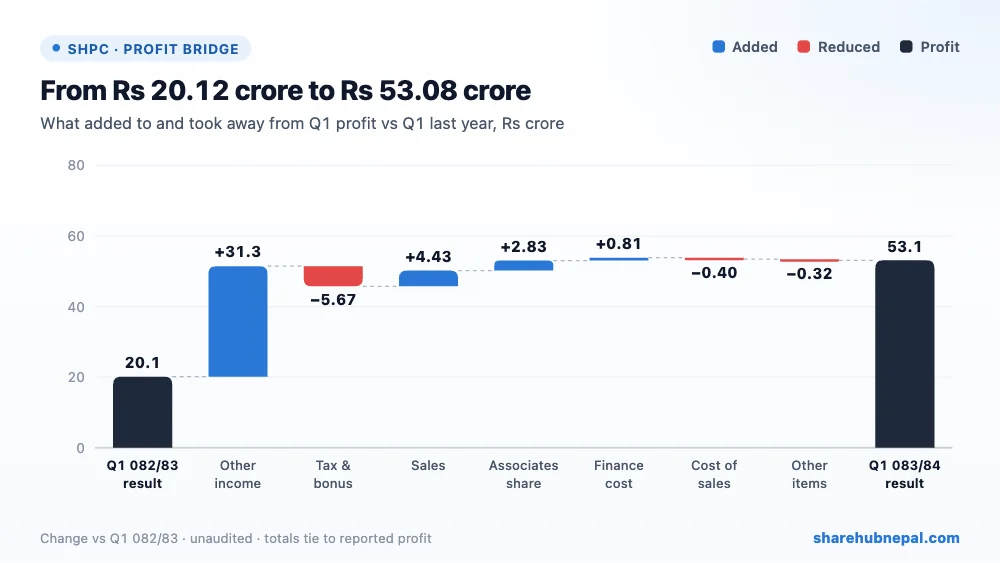
The profit bridge shows where the extra Rs 32.96 crore came from. Other income (insurance claim and dividend) added Rs 31.28 crore, higher electricity sales Rs 4.43 crore, the associates (SGHC, MMKJL, TAMOR and others) Rs 2.83 crore, and lower finance cost Rs 81.04 lakh, because the Mai (22 MW) loan was fully repaid. Against this, income tax rose by Rs 5.67 crore: the 10-year tax holiday of both plants has ended and profit is now taxed at the concessional 12.5% rate. Note that the insurance money (Rs 28.71 crore) and a Rs 28.60 crore posted-rate claim from NEA are still to be received.
2. Profit through the year
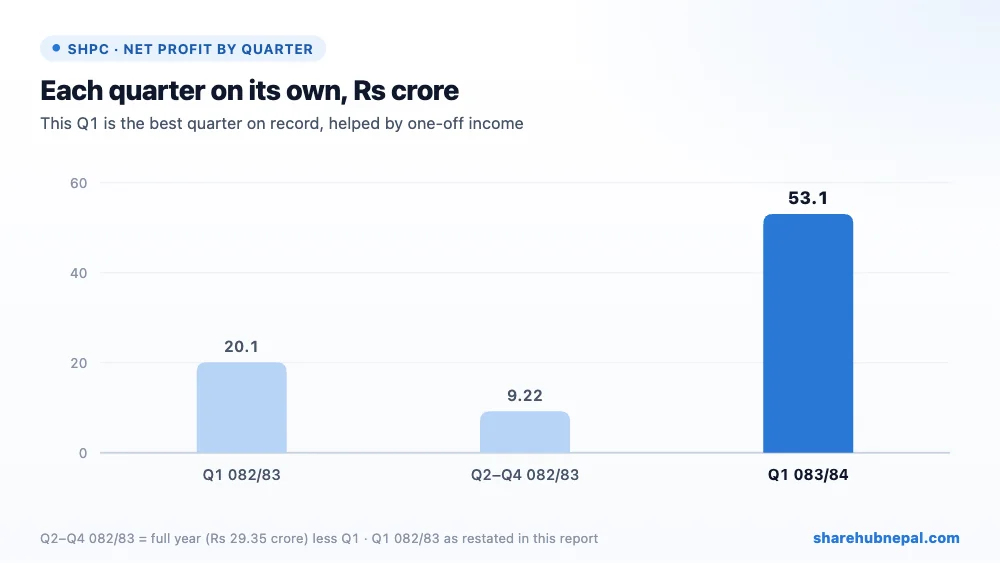
Profit by quarter (Share Hub records): Q1 082/83: Rs 20.12 crore, Q2–Q4 082/83: Rs 9.22 crore, Q1 083/84: Rs 53.08 crore. Last year was hit by the flood shutdown, so Q2–Q4 together earned only Rs 9.22 crore. This Q1 is boosted by the insurance claim, so it is not a normal run-rate.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Total assets | Rs 5,909,111,859 | Rs 5,454,505,271 | +8.33% |
| Total equity | Rs 5,685,919,992 | Rs 5,139,711,256 | +10.63% |
| Long-term borrowings | Rs 0 | Rs 0 | – |
| Current borrowings | Rs 73,123,458 | Rs 107,747,000 | −32.13% |
| Cash and equivalents | Rs 175,536,733 | Rs 23,702,921 | +640.57% |
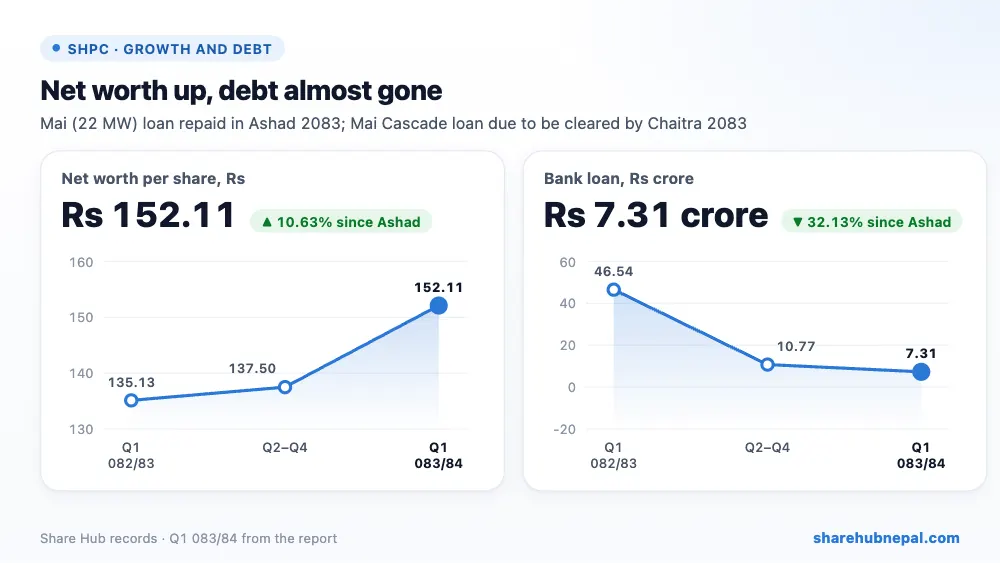
The balance sheet is strong. Equity rose 10.63% to Rs 568.59 crore and net worth per share to Rs 152.11. Total borrowing is only Rs 7.31 crore (the Mai Cascade loan, due to be cleared by Chaitra 2083), down from Rs 46.54 crore a year ago. Cash jumped to Rs 17.55 crore and other financial assets (including the insurance receivable) to Rs 71.11 crore. A third of the assets (Rs 197.75 crore) are investments in group hydropower companies.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised) | Rs 56.80 |
| Net worth per share | Rs 152.11 |
| Market price (Ashwin end) | Rs 535 |
| P/E (annualised) | 9.42x |
| P/B | 3.52x |
At the Ashwin-end price of Rs 535, the share trades at 9.42 times annualised EPS and 3.52 times net worth per share. This P/E uses a seasonal quarter that also includes the one-off insurance claim, so it looks cheaper than it is; on FY 2082/83 EPS of Rs 7.85 the P/E would be about 68x.
Conclusion
Positives: sales up 20%, associates' profit up 38%, almost debt-free, strong net worth growth and cash.
Watch: most of the profit is a one-off insurance claim not yet received; Rs 28.60 crore posted-rate claim with NEA still pending; tax holiday over (12.5% tax now); flood risk to the plants.
A strong quarter on paper, but investors should judge SHPC on its core earnings (about Rs 28 crore this quarter) and on whether the insurance and NEA money is actually collected.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

