













Shikhar Insurance Co. Ltd – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
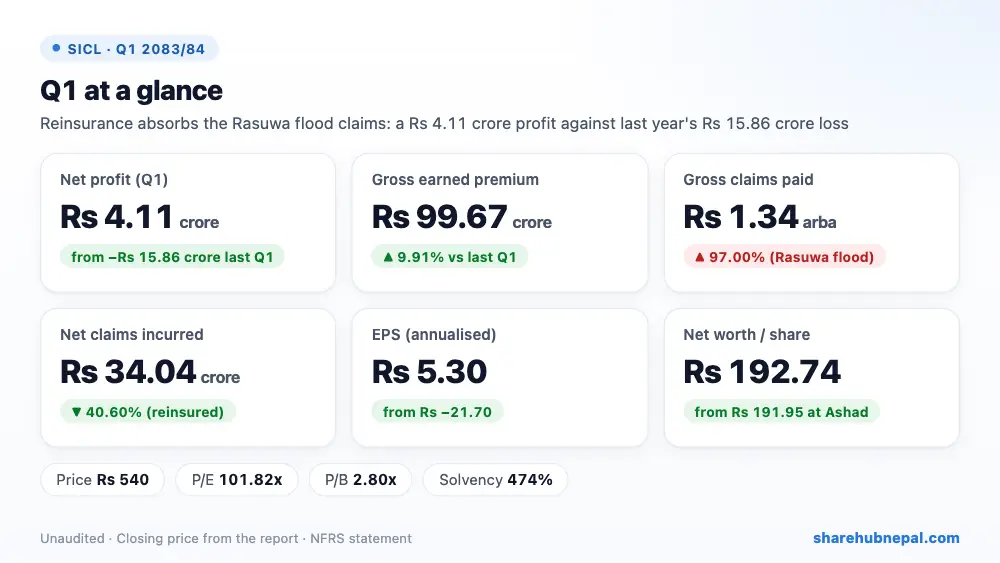
Shikhar Insurance earned a net profit of Rs 4.11 crore in the first quarter of FY 2083/84, against a loss of Rs 15.86 crore a year ago. Gross claims paid nearly doubled to Rs 1.34 arba because of the Rasuwa flash flood of Bhadra 10, 2083, but the company's reinsurance (which it says is the largest catastrophe programme in the industry) recovered most of it, so net claims actually fell 40.60% to Rs 34.04 crore. Net premium rose 13.79% and reinsurance commission 38.89%, while investment income fell 35.01% as bank interest rates dropped. Annualised EPS is Rs 5.30 and net worth per share is Rs 192.74.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Gross earned premium | Rs 996,738,028 | Rs 906,835,455 | +9.91% |
| Net earned premium | Rs 330,893,329 | Rs 290,786,003 | +13.79% |
| Reinsurance commission income | Rs 233,770,292 | Rs 168,312,186 | +38.89% |
| Income from investments and loans | Rs 42,897,368 | Rs 66,010,591 | −35.01% |
| Gross claims paid | Rs 1,340,031,211 | Rs 680,224,183 | +97.00% |
| Net claims incurred | Rs 340,438,546 | Rs 573,081,603 | −40.60% |
| Employee benefits | Rs 127,233,824 | Rs 109,459,631 | +16.24% |
| Other operating expenses | Rs 54,614,400 | Rs 35,654,144 | +53.18% |
| Profit before tax | Rs 58,744,936 | −Rs 226,552,027 | Turned to profit |
| Income tax | Rs 17,623,481 | −Rs 67,965,608 | Turned to profit |
| Net profit | Rs 41,121,455 | −Rs 158,586,419 | Turned to profit |
| EPS (annualised) | 5.3 | -21.7 | – |
| Net worth per share | 192.74 | 192.63 | – |
1. Where the profit came from
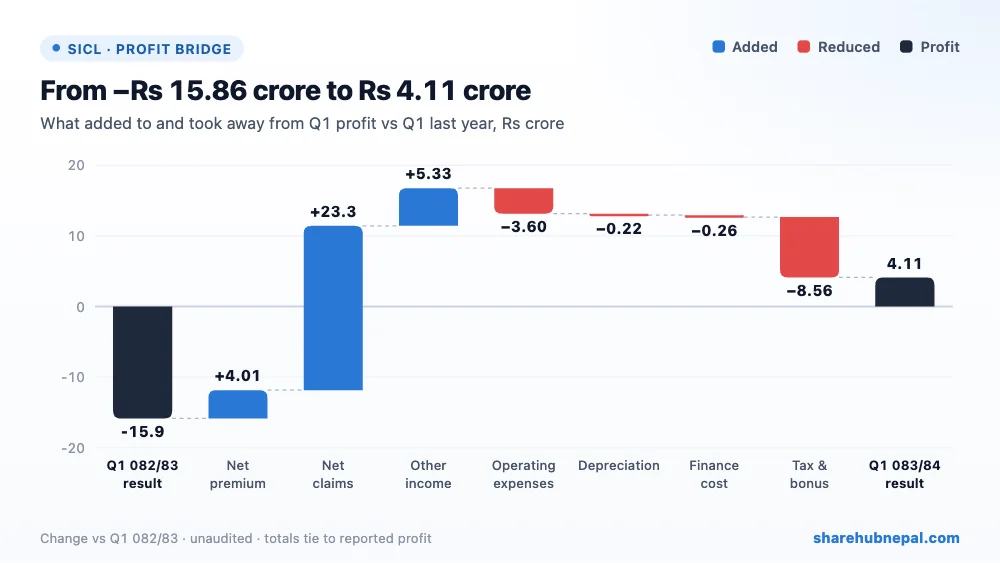
Compared with last year, lower net claims added Rs 23.26 crore and higher net premium Rs 4.01 crore. Commission, investment and other income together rose Rs 5.33 crore. Against this, staff costs rose 16.24% and other operating expenses 53.18%, adding Rs 3.60 crore of costs. Profit before tax was Rs 5.87 crore (a loss of Rs 22.66 crore last year); after tax of Rs 1.76 crore (a Rs 6.80 crore tax credit last year), net profit was Rs 4.11 crore. OCI added Rs 1.83 crore.
2. Profit through the year
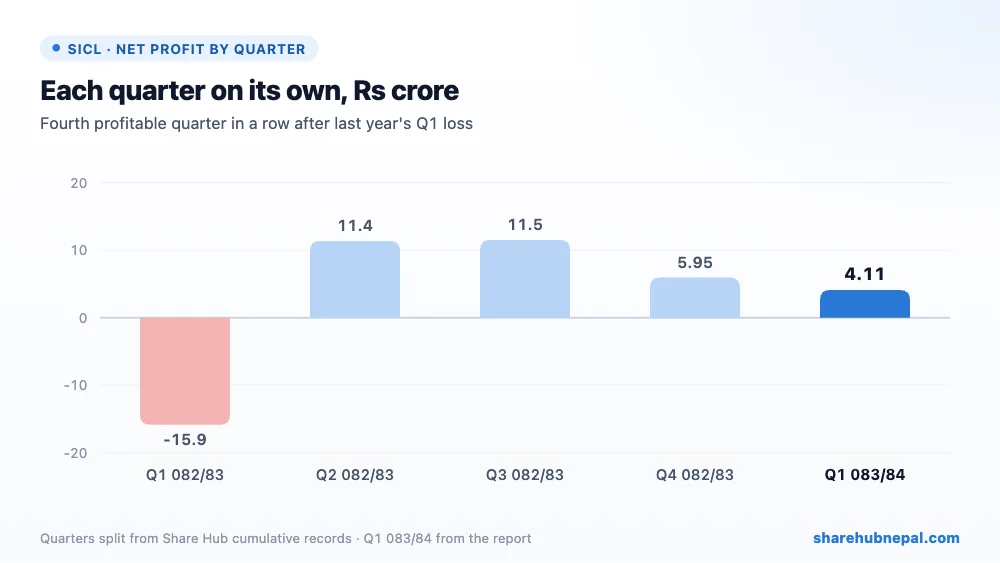
Profit by quarter (Share Hub cumulative records, split into quarters): Q1 082/83: −Rs 15.86 crore, Q2 082/83: Rs 11.39 crore, Q3 082/83: Rs 11.53 crore, Q4 082/83: Rs 5.95 crore, Q1 083/84: Rs 4.11 crore. Last year Shikhar lost Rs 15.86 crore in Q1 but earned about Rs 11 crore each in Q2 and Q3 and Rs 5.95 crore in Q4, ending with EPS of Rs 4.19. A profitable Q1 is a good start, though it rests heavily on reinsurance recoveries.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Total assets | Rs 20,535,432,637 | Rs 17,176,456,515 | +19.56% |
| Investments | Rs 4,519,282,310 | Rs 4,760,962,465 | −5.08% |
| Reinsurance assets | Rs 11,112,366,290 | Rs 8,172,435,126 | +35.97% |
| Gross insurance contract liabilities | Rs 13,129,718,278 | Rs 9,935,314,853 | +32.15% |
| Borrowings | Rs 475,500,000 | Rs 345,000,000 | +37.83% |
| Total equity | Rs 5,977,971,991 | Rs 5,918,572,000 | +1.00% |
| Cash and equivalents | Rs 66,052,773 | Rs 148,313,545 | −55.46% |
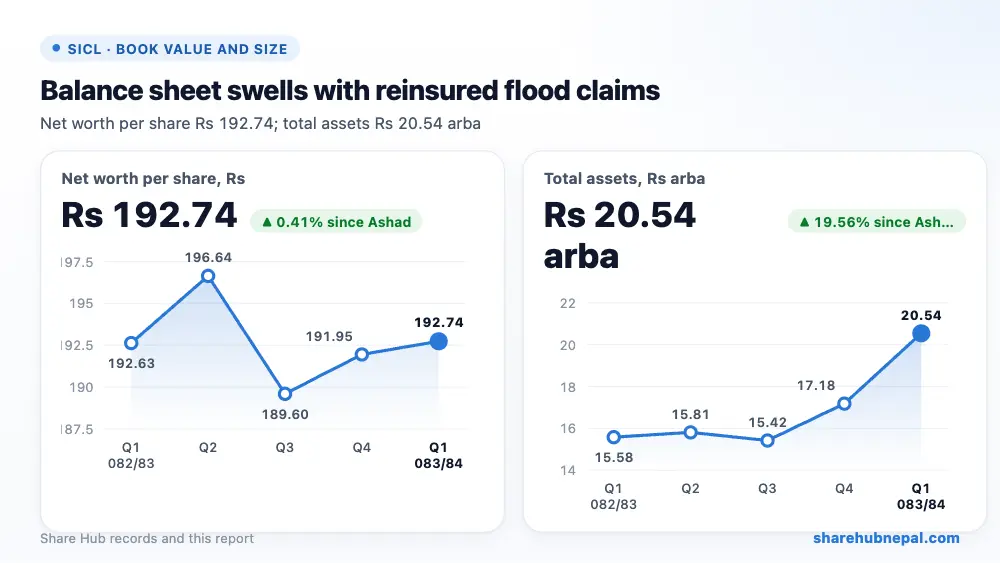
Total assets jumped 19.56% to Rs 20.54 arba, mostly because flood claims raised both insurance contract liabilities (Rs 13.13 arba, +32.15%) and reinsurance assets (Rs 11.11 arba). Gross outstanding claims including IBNR are Rs 6.92 arba, but net of reinsurance only Rs 61.63 crore. Borrowings rose to Rs 47.55 crore and cash fell to Rs 66.05 lakh. Equity rose 1% to Rs 5.98 arba. Solvency is 474%, far above the 130% minimum.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised) | Rs 5.30 |
| Net worth per share | Rs 192.74 |
| Market price (Ashwin end) | Rs 540 |
| P/E (annualised) | 101.89x |
| P/B | 2.80x |
At the Ashwin-end price of Rs 540, the share trades at 101.89 times annualised EPS and 2.80 times net worth per share. The report prints a P/E of 101.82. On last year's EPS of Rs 4.19 the P/E is about 129, so the price assumes earnings will rise strongly.
Conclusion
Positives: a profit against last year's loss, strong reinsurance protection against the flood, net premium up 13.79%, reinsurance commission up 38.89%, new policies up 28.79%, and solvency of 474%.
Watch: investment income down 35.01%, other operating expenses up 53.18%, rising borrowings and low cash, a P/E above 100, heavy dependence on reinsurers paying flood claims, and tax disputes with the Large Taxpayers Office.
Watch reinsurance recoveries on the flood claims, investment income as rates fall, and cost control.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

