













Super Khudi Hydropower Ltd – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
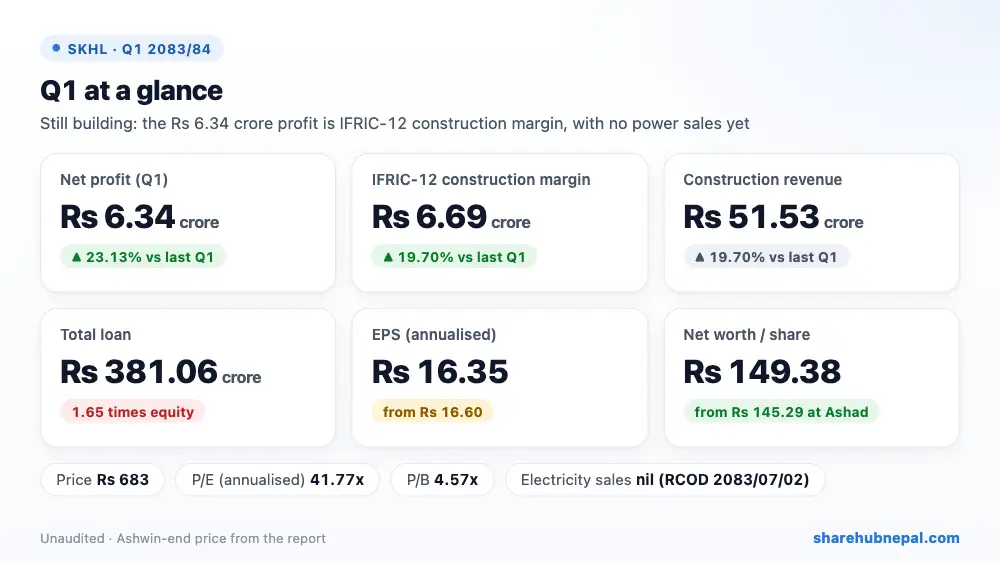
Super Khudi Hydropower reported a net profit of Rs 6.34 crore in the first quarter of FY 2083/84, up 23.13% from Rs 5.15 crore a year ago. But the plant is still under construction and has not sold any electricity yet. The whole profit is an accounting gain under IFRIC-12: the company books construction revenue of Rs 51.53 crore against construction cost of Rs 44.84 crore, leaving a margin of Rs 6.69 crore. The report itself says that without this, operations made a loss of Rs 34.91 lakh. The project's required commercial operation date is 2083/07/02, right after this quarter. Annualised EPS is Rs 16.35 and net worth per share is Rs 149.38.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Construction revenue (IFRIC-12) | Rs 515,346,109 | Rs 430,537,494 | +19.70% |
| Construction expenses (IFRIC-12) | Rs 448,439,009 | Rs 374,641,050 | +19.70% |
| Profit as per IFRIC-12 (construction margin) | Rs 66,907,100 | Rs 55,896,445 | +19.70% |
| Administrative expenses | Rs 2,239,768 | Rs 2,791,668 | −19.77% |
| Depreciation (incl. ROU) | Rs 1,251,524 | Rs 1,607,980 | −22.17% |
| Profit from operations | Rs 63,415,808 | Rs 51,496,797 | +23.15% |
| Finance charges | Rs 42,986 | Rs 26,527 | +62.05% |
| Income tax | Rs 0 | Rs 0 | – |
| Net profit | Rs 63,372,822 | Rs 51,470,270 | +23.13% |
| EPS (annualised) | 16.35 | 16.6 | – |
| Net worth per share | 149.38 | 137.23 | – |
1. Where the profit came from
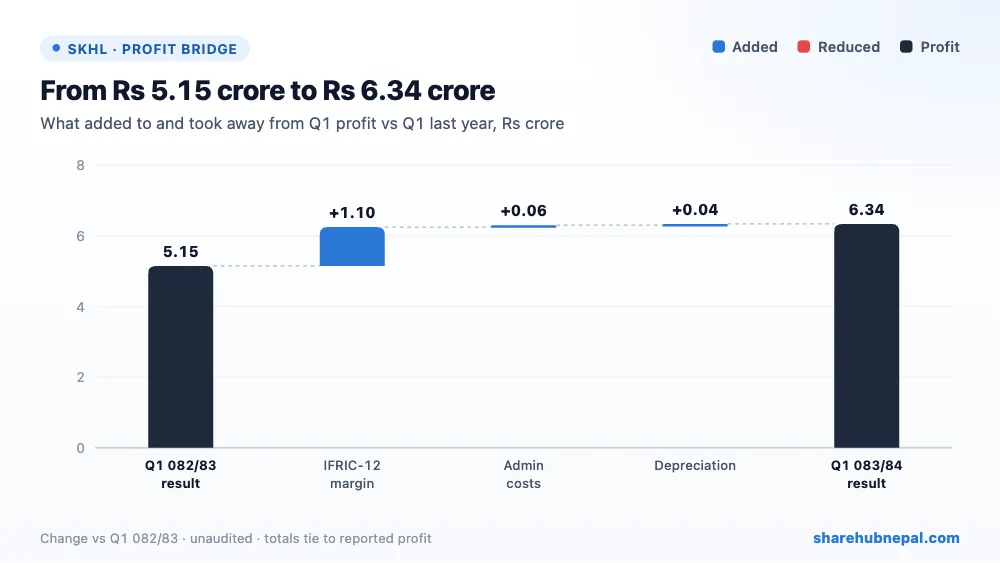
Construction revenue under IFRIC-12 rose 19.70% to Rs 51.53 crore because more was spent on the project, and the construction margin rose by the same rate to Rs 6.69 crore. Administrative expenses fell to Rs 22.40 lakh (Rs 27.92 lakh) and depreciation to Rs 12.52 lakh. Profit from operations was Rs 6.34 crore. Finance charges through profit were tiny (Rs 42,986) because interest on the project loan is still capitalised into the project cost. No tax was charged. Remember that this profit is not cash: it is the value added by construction, and it will stop once the plant starts running, when real electricity sales, depreciation and full interest cost take over.
2. Profit through the year
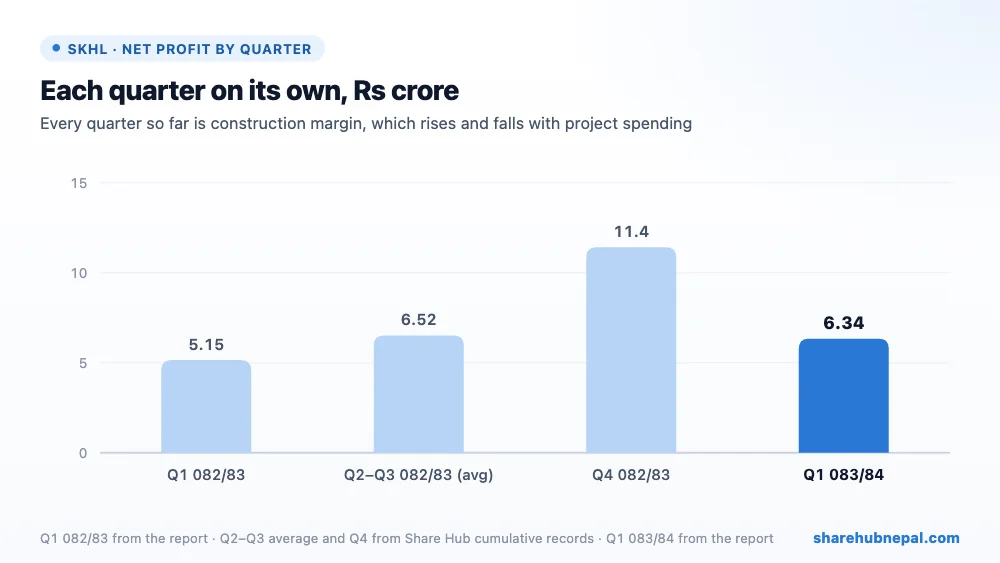
Profit by quarter (from this report and Share Hub records): Q1 082/83: Rs 5.15 crore, Q2–Q3 082/83 (avg): Rs 6.52 crore, Q4 082/83: Rs 11.42 crore, Q1 083/84: Rs 6.34 crore. The quarterly numbers follow project spending, not electricity output, so the big Q4 figure (Rs 11.42 crore) only reflects heavy construction in that quarter. FY 2082/83 EPS was Rs 19.10, all from construction margin.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Total assets | Rs 6,761,002,398 | Rs 6,397,469,228 | +5.68% |
| Project under construction (IAUD) | Rs 6,513,453,512 | Rs 5,998,107,403 | +8.59% |
| Total equity | Rs 2,315,342,911 | Rs 2,251,970,088 | +2.81% |
| Long-term borrowing | Rs 3,780,609,800 | Rs 3,006,828,383 | +25.73% |
| Short-term borrowing | Rs 30,000,000 | Rs 546,557,883 | −94.51% |
| Other current liabilities | Rs 629,174,084 | Rs 590,439,208 | +6.56% |
| Prepayments | Rs 70,598,684 | Rs 122,496,656 | −42.37% |
| Cash and equivalents | Rs 3,008,536 | Rs 30,569,977 | −90.16% |
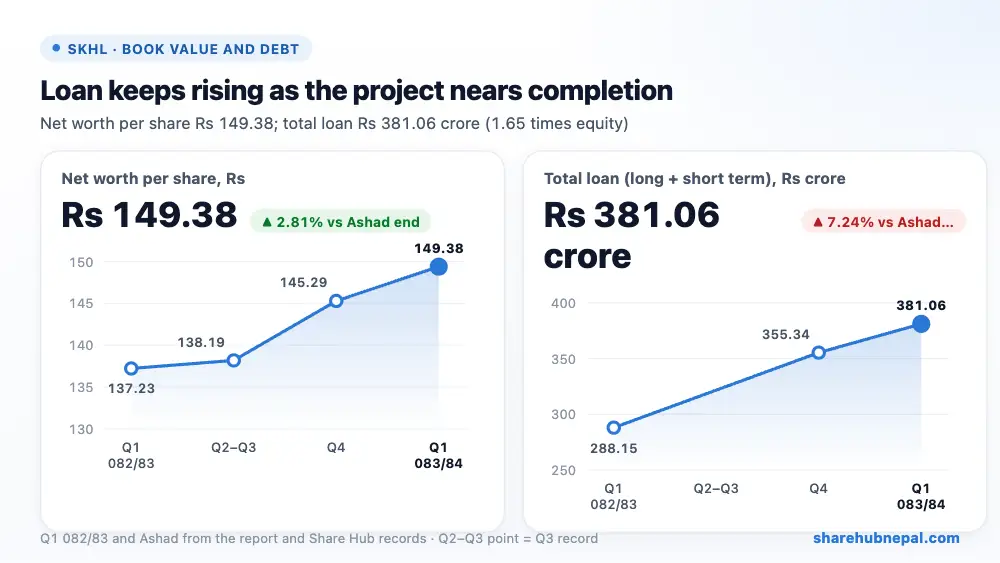
The project under construction is now valued at Rs 6.51 arba, up Rs 51.53 crore in the quarter. To pay for it, long-term borrowing rose to Rs 3.78 arba from Rs 3.01 arba, while short-term borrowing fell to Rs 3 crore from Rs 54.66 crore (refinanced into long-term loan). Total loan is Rs 3.81 arba, 1.65 times equity of Rs 2.32 arba. Cash is low at Rs 30.09 lakh and other current liabilities (likely contractor payables) are Rs 62.92 crore, much more than current assets of Rs 21.97 crore, so the company depends on its lenders until power sales start.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised) | Rs 16.35 |
| Net worth per share | Rs 149.38 |
| Market price (Ashwin end) | Rs 683 |
| P/E (annualised) | 41.77x |
| P/B | 4.57x |
At the Ashwin-end price of Rs 683, the share trades at 41.77 times annualised EPS and 4.57 times net worth per share. This earnings figure is construction margin, not profit from selling power, so the P/E says little. The report prints a P/E of 167.05 using the quarter EPS. The price really depends on how well the plant runs after it starts operating.
Conclusion
Positives: the project is close to its commercial operation date (2083/07/02), short-term loans were refinanced into long-term loans, equity and net worth per share keep rising, and there are no legal cases.
Watch: the profit is only IFRIC-12 construction margin (operations alone made a loss of Rs 34.91 lakh), debt is high at 1.65 times equity, cash is very low against Rs 62.92 crore of current liabilities, interest will hit profit fully once capitalisation stops, and the company itself names weak transmission lines and a lack of local equipment suppliers as risks.
Watch for the commercial operation announcement, the first quarter of real electricity sales, and how much interest the company pays once the loan cost stops being capitalised.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

