













Samudayik Laghubitta Bittiya Sanstha Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082).
Summary
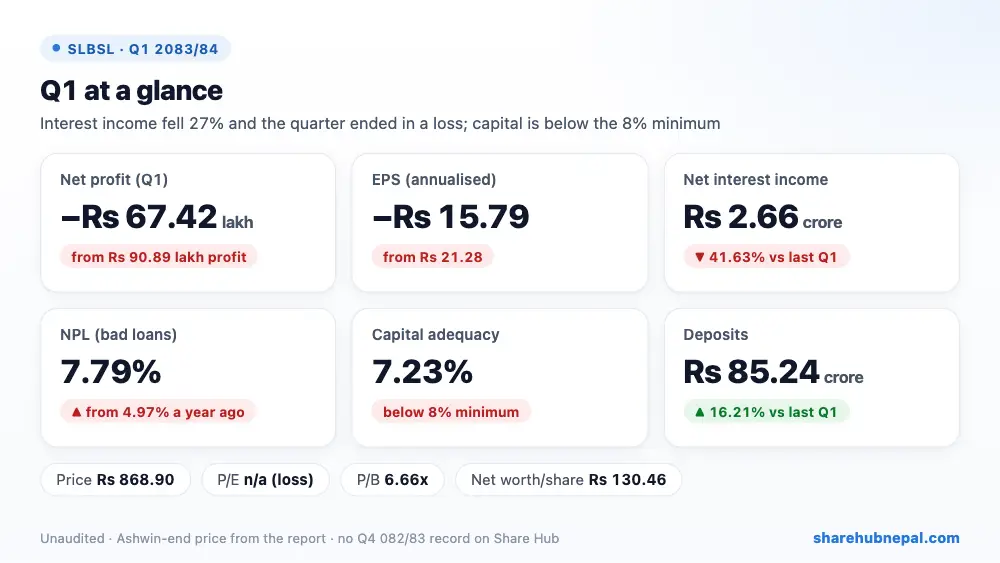
Samudayik Laghubitta posted a net loss of Rs 67.42 lakh in the first quarter, against a profit of Rs 90.89 lakh a year ago. EPS is Rs -15.79 against Rs 21.28.
Compared with last year, the biggest help came from impairment (+Rs 34.46 lakh) and fees & commission (+Rs 6.64 lakh), while the biggest drag was net interest income (−Rs 1.90 crore).
Samudayik Laghubitta posted a net loss of Rs 67.42 lakh in Q1 of FY 2083/84, against a profit of Rs 90.89 lakh a year ago. Interest income fell 26.96% to Rs 5.85 crore while interest cost fell only 7.55%, so net interest income dropped 41.63% to Rs 2.66 crore. The report says interest is now booked under NRB's Interest Recognition Guidelines, 2025. Staff and other costs stayed almost the same, so the company made an operating loss of Rs 65.35 lakh.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Net profit | −Rs 6,741,585 | Rs 9,088,559 | Turned to loss |
| Net interest income | Rs 26,617,846 | Rs 45,599,385 | −41.63% |
| Net fee and commission income | Rs 6,050,509 | Rs 5,386,291 | +12.33% |
| Impairment charge/(reversal) | −Rs 864,730 | Rs 2,581,068 | – |
| Operating profit | −Rs 6,535,130 | Rs 8,033,260 | Turned to loss |
| EPS | Rs -15.79 | Rs 21.28 | – |
| Net worth per share | Rs 130.46 | Rs 122.06 | +6.88% |
| NPL | 7.79% | 4.97% | +2.82 pts |
| Capital adequacy | 7.23% | 7.29% | −0.06 pts |
1. Where the profit came from
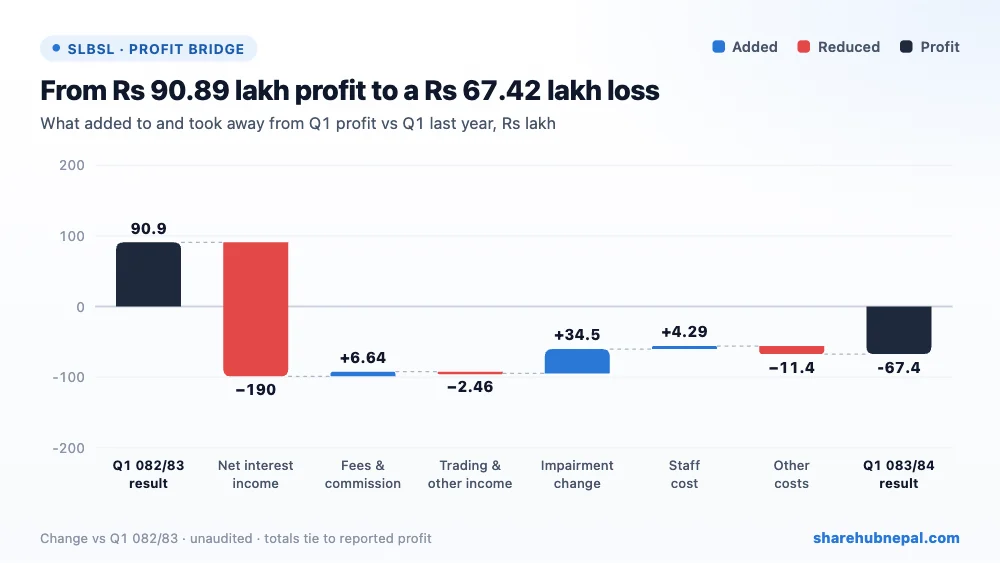
The bridge chart shows how Q1 profit moved from last year's Rs 90.89 lakh to this year's −Rs 67.42 lakh:
- Net interest income (−Rs 1.90 crore): interest income fell 26.96% while interest expense fell 7.55%.
- Impairment (+Rs 34.46 lakh): the bank wrote back (reversed) Rs 8.65 lakh of earlier loan-loss provisions, against a charge of Rs 25.81 lakh last year.
- Other costs (−Rs 11.41 lakh): other operating expenses, depreciation and non-operating items combined.
- Fees & commission (+Rs 6.64 lakh): net fee income was Rs 60.51 lakh against Rs 53.86 lakh.
- Staff cost (+Rs 4.29 lakh): personnel expenses fell 1.36% to Rs 3.12 crore.
- Trading & other income (−Rs 2.46 lakh): trading income and other operating income combined.
In plain terms: operating costs took 122.6% of operating income, against 79.3% a year ago.
2. Profit through the year
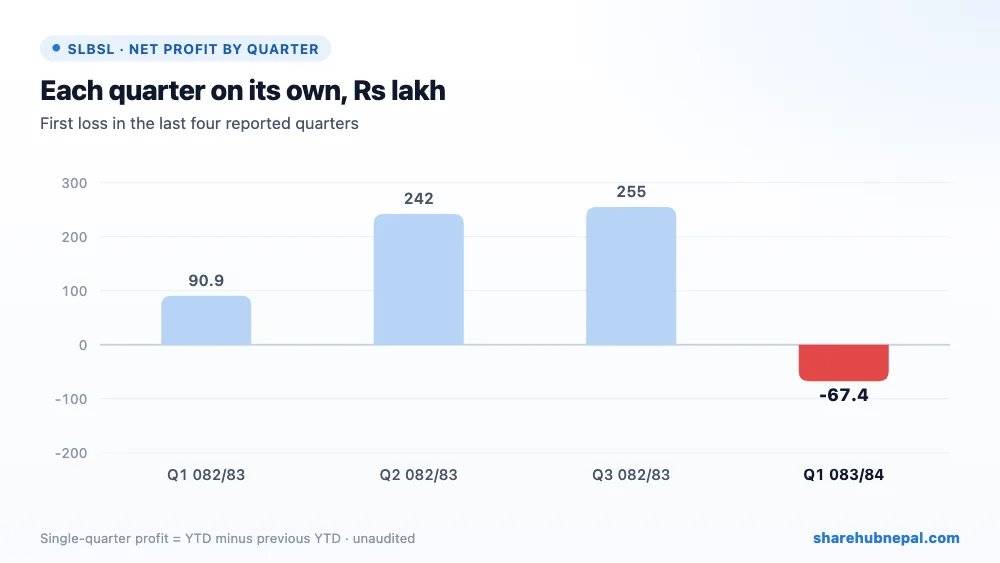
Looking at each quarter on its own (year-to-date profit minus the previous quarter's): Q1 082/83: Rs 90.89 lakh; Q2 082/83: Rs 2.42 crore; Q3 082/83: Rs 2.55 crore; Q1 083/84: −Rs 67.42 lakh.
Based on Share Hub records, single-quarter profit in 2082/83 was Rs 90.89 lakh in Q1, Rs 2.42 crore in Q2 and Rs 2.55 crore in Q3. Share Hub has no proper Q4 2082/83 record for SLBSL, so Q4 is left out. This Q1 loss of Rs 67.42 lakh is the first loss among the quarters shown.
3. Deposits, loans and liquidity
| Particulars | Ashwin 2083 | Ashwin 2082 | Change |
| Deposits from customers | Rs 852,367,551 | Rs 733,495,342 | +16.21% |
| Loans and advances to customers | Rs 2,083,295,178 | Rs 1,949,145,639 | +6.88% |
| Cash and cash equivalent | Rs 74,272,672 | Rs 94,405,479 | −21.33% |
| Balance with Nepal Rastra Bank | Rs 0 | Rs 0 | n/a |
| Investment securities | Rs 1,000,000 | Rs 1,000,000 | +0.00% |
| Total assets | Rs 2,241,245,699 | Rs 2,137,079,327 | +4.87% |
| Total equity | Rs 222,287,642 | Rs 208,480,657 | +6.62% |
In the quarter, deposits grew 16.21% and customer loans grew 6.88%. The credit-to-deposit ratio is 255.96% (280.30% a year ago).
Pricing: cost of funds 6.35% (from 7.40%), base rate 14.93% (from 14.09%), interest spread 8.18% (from 7.50%).
The balance sheet in the report is compared with the same quarter last year (the column matches Share Hub's Q1 2082/83 record). Over the year, loans grew 6.88% to Rs 2.08 arba and deposits 16.21% to Rs 85.24 crore while borrowings fell 4.31% to Rs 1.08 arba. Cash fell 21.33% to Rs 7.43 crore. Equity is Rs 22.23 crore (Rs 130.46 per share as printed; Rs 130.14 by plain math), but the accumulated distributable loss has reached Rs 7.61 crore.
4. Bad loans and capital
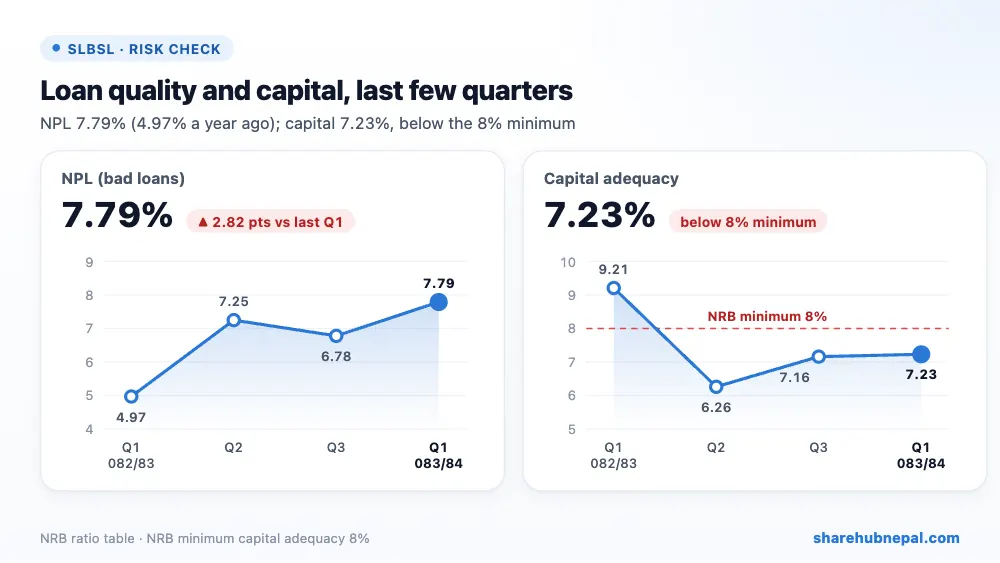
- NPL is 7.79% and 4.97% a year ago. Loan-loss provisions cover 91.13% of bad loans (119.78% a year ago).
- Capital adequacy is 7.23% and 7.29% a year ago. NRB's minimum is 8%, so the buffer is -0.77 points.
- Capital adequacy is 7.23%, below the 8% minimum NRB requires for microfinance (7.29% a year ago). NPL rose to 7.79% from 4.97% a year ago, though provisions still cover 91.13% of bad loans. The company has signed a preliminary merger agreement with Sanjiwani Laghubitta (Dang) and is waiting for NRB's in-principle approval. The report also mentions banking-offence cases filed against staff for financial irregularities at some branches.
5. Distributable profit
| Particulars (Rs) | Amount |
| Net loss for the quarter | (6,741,585) |
| Add: interest receivable adjustment | 542,653 |
| Q1 distributable profit (loss) | (6,198,932) |
| Opening distributable loss (Shrawan 1) | (69,943,114) |
| Total distributable loss | (76,142,046) |
The Q1 loss of Rs 67.42 lakh after a Rs 5.43 lakh interest-receivable adjustment, adds Rs 61.99 lakh to the accumulated loss. With Rs 6.99 crore brought forward, the total distributable loss is Rs 7.61 crore or Rs 44.58 per share. No dividend is possible until this loss is cleared.
6. Per-share figures and valuation
| Indicator | Value |
| EPS (as reported) | Rs -15.79 |
| Net worth per share | Rs 130.46 |
| Distributable EPS | Rs -44.58 |
| Closing price, Ashwin end 2083 | Rs 868.90 |
| Price range during the quarter | Rs 840.00 – Rs 1157.00 |
| Price to book | 6.66x |
With a loss, P/E is not meaningful. At Rs 868.90 the share trades at 6.66 times net worth per share, which is very expensive for a microfinance with a loss, capital below the minimum and a large accumulated loss. The price seems to rest on the merger.
Conclusion
Positives: deposits up 16.21%, borrowings down 4.31%, fee income up 12.33%, cost of funds down to 6.35% (7.40% a year ago), spread up to 8.18%, a small impairment write-back, provision cover still 91.13%.
Watch points: Q1 net loss, net interest income down 41.63%, capital adequacy 7.23% (below the 8% minimum), NPL 7.79%, accumulated distributable loss Rs 7.61 crore staff fraud cases, and a merger that still needs NRB approval.
Samudayik's core income has shrunk under the new interest-recognition rule, and with capital below the minimum and a large accumulated loss, the planned merger with Sanjiwani Laghubitta looks like the main way forward. Until the merger is approved and capital is restored, earnings and dividends look weak.
Based on the company's unaudited first-quarter report. Figures may change after audit or regulator review. This is not investment advice.

