













Synergy Power Development Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
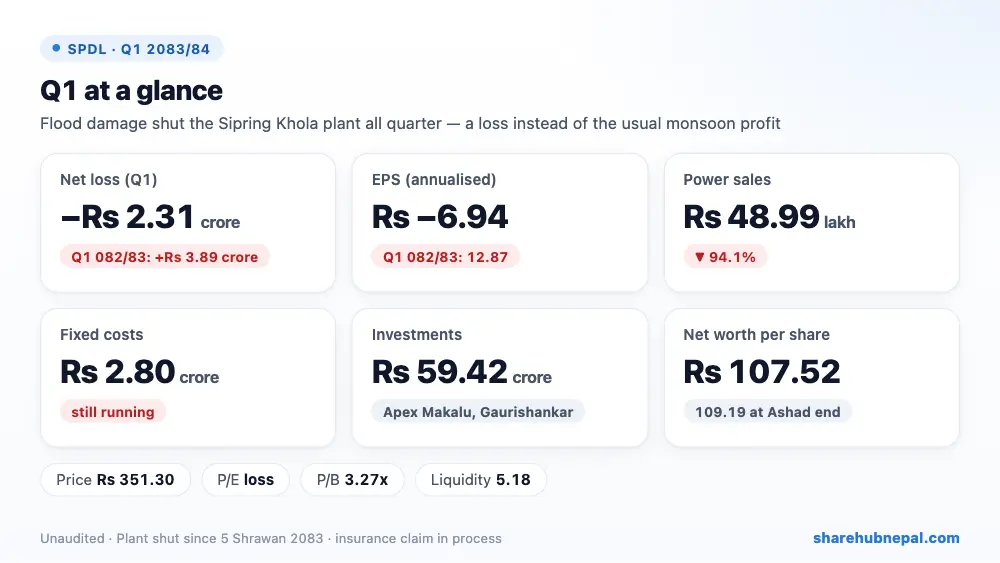
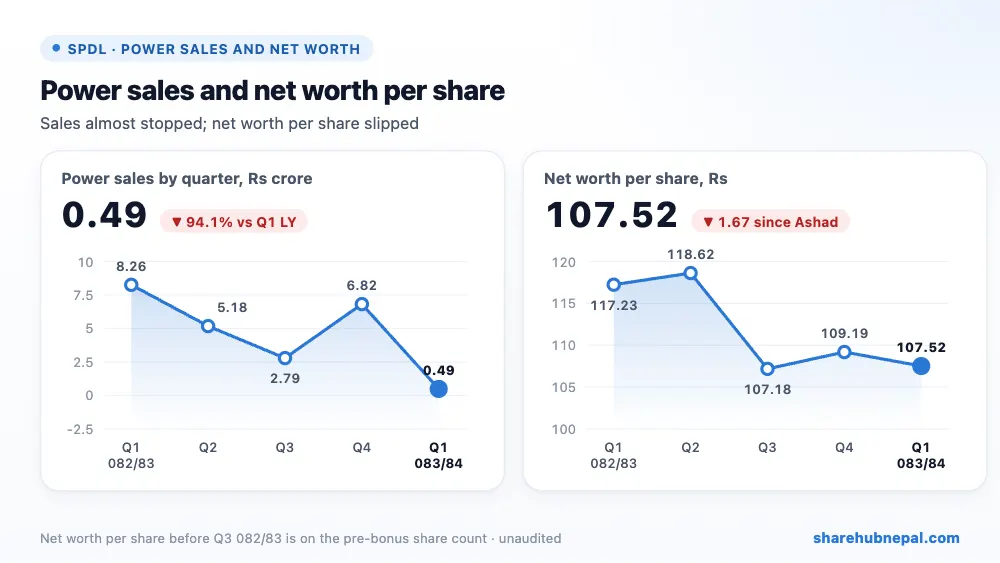
Synergy Power Development made a net loss of Rs 2.31 crore in the first quarter of 2083/84, against a profit of Rs 3.89 crore in the same quarter last year. Annualised EPS is Rs −6.94 (12.87 a year ago) and net worth per share fell to Rs 107.52.
The reason is simple: the flood damaged the headworks of the Sipring Khola project and the plant has been completely shut since 5 Shrawan 2083. Electricity sales fell 94% to only Rs 48.99 lakh, while depreciation, staff, admin and interest costs (Rs 2.80 crore) kept running. The company has filed an insurance claim for the physical damage and for loss of profit; rebuilding could not start during the monsoon because of the difficult location, and will start after the rains.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Electricity sales | Rs 4,898,791 | Rs 82,573,330 | −94.07% |
| Project expenses | Rs 1,961,853 | Rs 3,376,693 | −41.90% |
| Admin and personnel expenses | Rs 8,347,927 | Rs 10,109,031 | −17.42% |
| Depreciation and amortisation | Rs 12,935,637 | Rs 14,466,544 | −10.58% |
| Finance expenses | Rs 4,775,342 | Rs 6,305,718 | −24.27% |
| Income tax | Rs 0 | Rs 7,975,616 | −100.00% |
| Net profit (loss) | −Rs 23,086,060 | Rs 38,939,774 | Turned to loss |
1. Where the profit came from
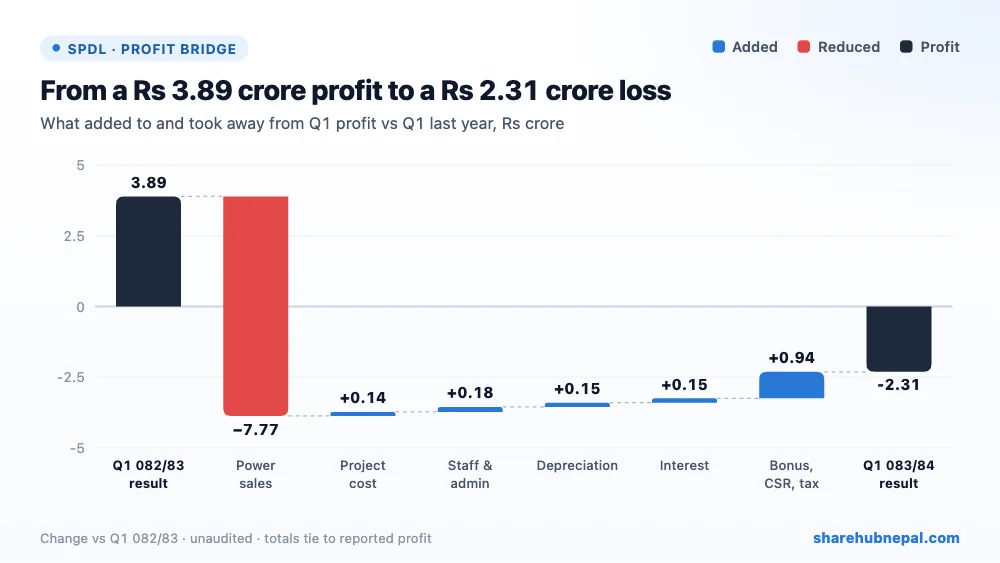
Against Q1 last year, lost power sales took away Rs 7.77 crore. Lower costs gave a little back: depreciation Rs 15.31 lakh, interest Rs 15.30 lakh, project cost Rs 14.15 lakh and staff/admin Rs 17.61 lakh; and there was no bonus, CSR or tax this time (Rs 93.83 lakh last year). Overall profit swung by Rs 6.20 crore.
2. Profit through the year
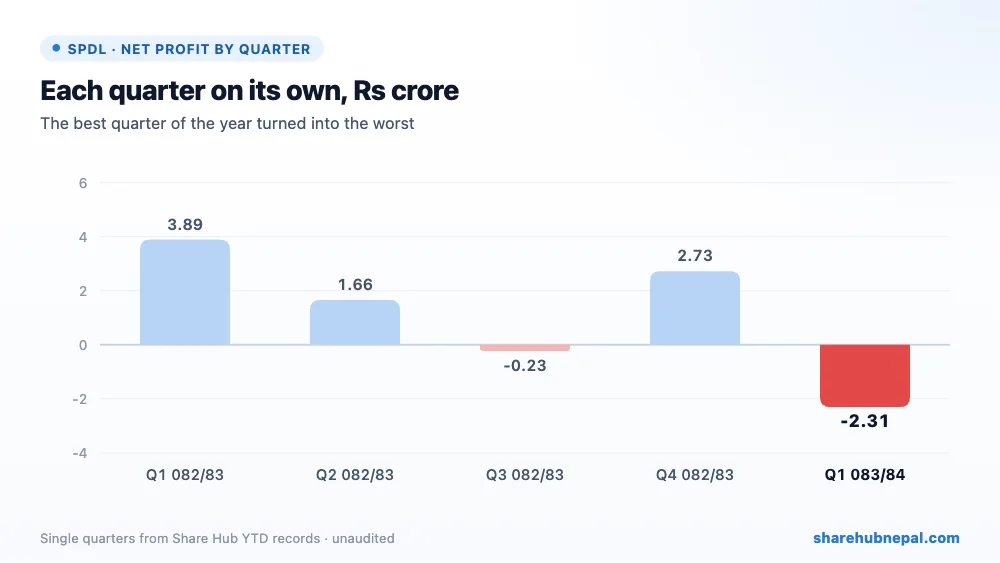
Last year Q1 was the best quarter (Rs 3.89 crore), followed by Rs 1.66 crore in Q2, a small loss in Q3 and Rs 2.73 crore in Q4, for a full-year profit of Rs 8.05 crore (EPS 6.05). This year the monsoon quarter, which normally carries the year, was lost. Until the headworks are rebuilt, each quarter is likely to show a loss of around Rs 2 crore unless the insurance claim is booked.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Plant, property and equipment | Rs 1,023,067,658 | Rs 1,032,977,217 | −0.96% |
| Investments | Rs 594,194,000 | Rs 594,194,000 | +0.00% |
| Trade and other receivables | Rs 52,124,271 | Rs 106,719,880 | −51.16% |
| Cash and bank | Rs 42,769,552 | Rs 35,571,313 | +20.24% |
| Secured loan | Rs 270,831,917 | Rs 304,225,601 | −10.98% |
| Total equity | Rs 1,430,988,536 | Rs 1,453,105,000 | −1.52% |
The balance sheet is still sound. The secured loan fell to Rs 27.08 crore (0.19 times equity), cash rose to Rs 4.28 crore as NEA paid old bills (receivables fell from Rs 10.67 crore to Rs 5.21 crore), and the liquidity ratio is 5.18. The company also holds Rs 59.42 crore of investments in Apex Makalu Hydropower and Gaurishankar Power Development. Equity fell Rs 2.21 crore, about Rs 9.70 lakh less than the loss (not explained).
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised, report) | Rs −6.94 |
| EPS (quarter, derived) | Rs −1.73 |
| Net worth per share | Rs 107.52 |
| Total assets per share (report) | Rs 129.40 |
| Market price (Q1 close) | Rs 351.30 |
| P/E | loss (report −50.63) |
| P/B | 3.27x |
| Liquidity ratio | 5.18 |
The Q1 closing price was Rs 351.30 (range Rs 326 to Rs 412.90). With a loss there is no meaningful P/E. The price is 3.27 times net worth per share — the market is looking past this quarter to the rebuild and the insurance money, which is a bet on how fast the plant comes back.
Conclusion
Positives: low debt that keeps falling, good liquidity (5.18), NEA paying old bills, a loss-of-profit insurance claim, and investments in two other hydro companies.
Watch: when the headworks rebuild starts and finishes, how much the insurer pays and when, losses each quarter while the plant is shut, and the small unexplained gap between the loss and the fall in equity.
SPDL's loss is caused by one event — flood damage that has shut its only plant. The company is not in financial stress, but this year's results depend almost entirely on how quickly Sipring Khola is repaired and how much the insurance covers.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

