













Shiva Shree Hydropower Ltd – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
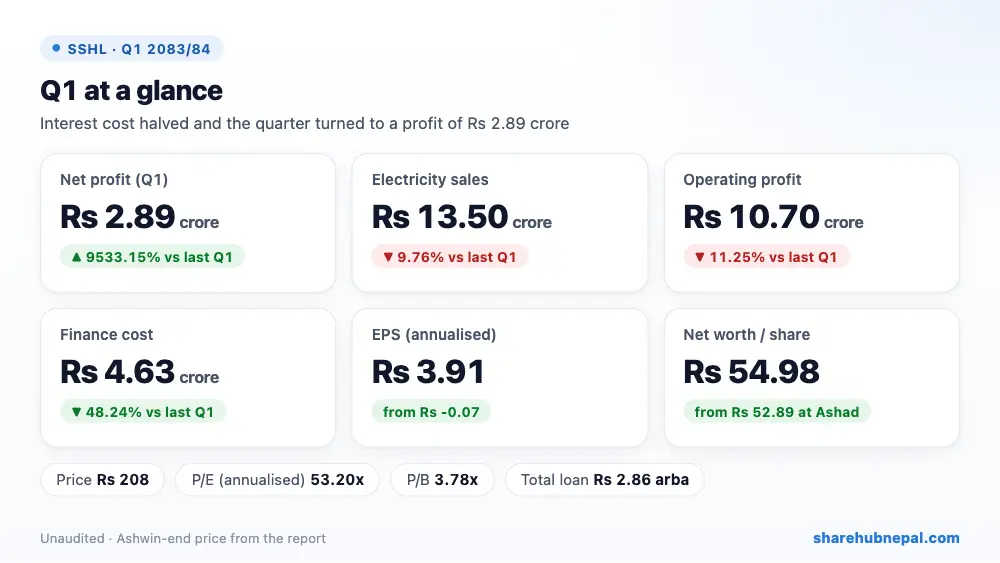
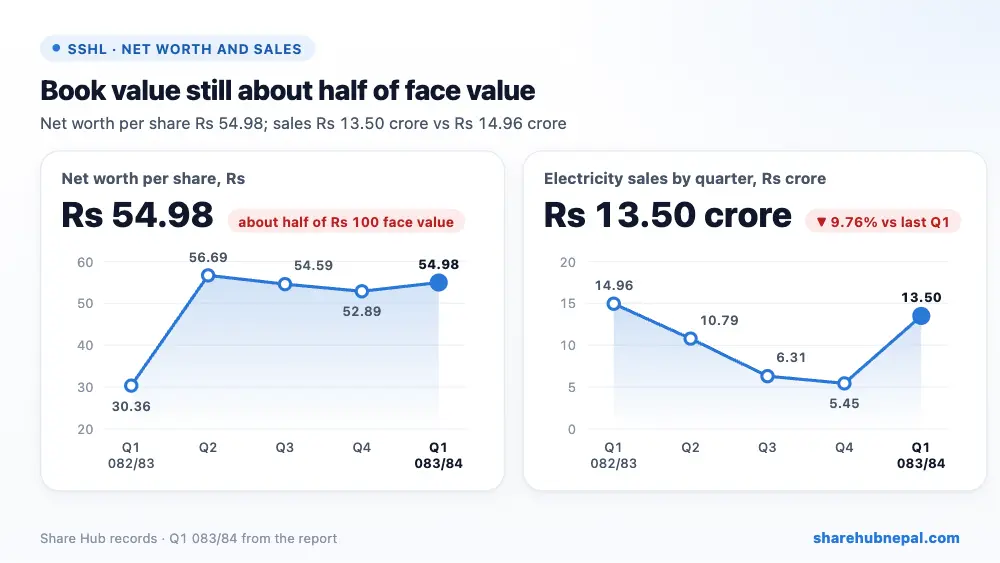
Shiva Shree Hydropower (Mathillo Chaku A, 22.2 MW, Sindhupalchok) earned a net profit of Rs 2.89 crore in the first quarter of FY 2083/84, against a small loss of Rs 3.06 lakh a year ago. Electricity sales actually fell 9.76% to Rs 13.50 crore, but finance cost almost halved (down 48.24% to Rs 4.63 crore) after the company used its right-share money to repay loans. Annualised EPS is Rs 3.91 and net worth per share is Rs 54.98, still far below the Rs 100 face value because of past losses.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Revenue from sales | Rs 134,998,012 | Rs 149,600,650 | −9.76% |
| Cost of sales | Rs 2,946,836 | Rs 3,123,386 | −5.65% |
| Other income | Rs 2,507,536 | Rs 90,000 | +2686.15% |
| Operating profit | Rs 107,041,323 | Rs 120,605,413 | −11.25% |
| Finance cost | Rs 46,275,038 | Rs 89,406,691 | −48.24% |
| Income tax | Rs 0 | Rs 0 | – |
| Net profit | Rs 28,870,522 | −Rs 306,054 | Turned to profit |
| EPS (annualised) | 3.91 | -0.07 | – |
| Net worth per share | 54.98 | 30.36 | – |
1. Where the profit came from
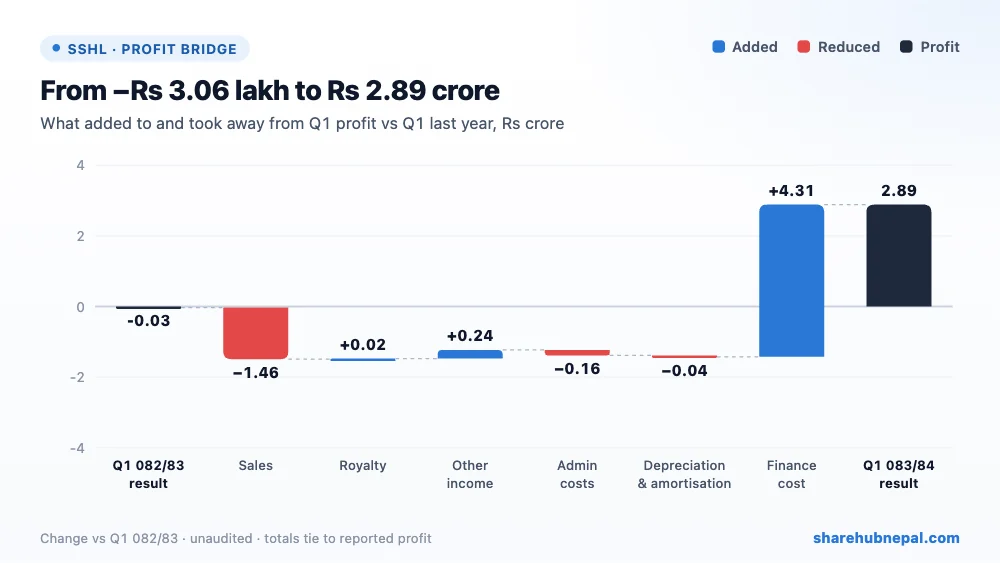
Lower electricity sales took away Rs 1.46 crore, and admin cost rose by Rs 15.56 lakh (5.99%) to Rs 2.75 crore. Depreciation was almost flat at Rs 3.19 crore. The big gain came from finance cost, which fell by Rs 4.31 crore to Rs 4.63 crore, and other income rose to Rs 25.08 lakh from Rs 90,000. Royalty fell slightly to Rs 29.47 lakh with lower sales. No tax was charged. Operating profit (before depreciation and interest, including other income) was Rs 10.70 crore, down 11.25%.
2. Profit through the year
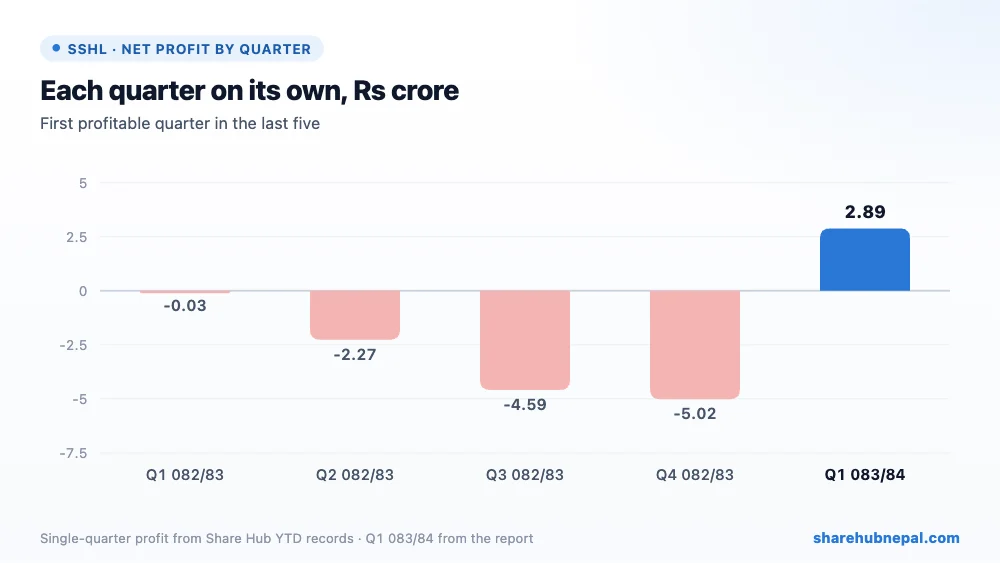
Profit by quarter (Share Hub records): Q1 082/83: −Rs 3.06 lakh, Q2 082/83: −Rs 2.27 crore, Q3 082/83: −Rs 4.59 crore, Q4 082/83: −Rs 5.02 crore, Q1 083/84: Rs 2.89 crore. FY 2082/83 ended with a loss of Rs 11.91 crore; every quarter was in loss as sales fell after the monsoon and interest cost stayed high. Q1 083/84 is the only profitable quarter of the last five.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Total assets | Rs 4,943,260,138 | Rs 4,917,861,503 | +0.52% |
| Total equity | Rs 1,623,506,861 | Rs 1,561,683,778 | +3.96% |
| Long-term borrowings | Rs 2,814,980,485 | Rs 2,891,748,442 | −2.65% |
| Current borrowings | Rs 48,700,000 | Rs 5,000,000 | +874.00% |
| Cash and equivalents | Rs 1,567,905 | Rs 741,544 | +111.44% |
A year ago the company carried Rs 3.51 arba of term loans and Rs 37.75 crore of short-term loans on only Rs 56.29 crore of equity. The right share lifted paid-up capital from Rs 1.85 arba to Rs 2.95 arba, and the money went into repaying debt. In Q1 the term loan fell from Rs 2.89 arba to Rs 2.81 arba, while the short-term loan rose from Rs 50 lakh to Rs 4.87 crore, so total loans moved only from Rs 2.90 arba to Rs 2.86 arba (1.76 times equity). Trade receivables and advances of Rs 43.88 crore make up about 99% of current assets (more than a full year of sales), cash is only Rs 15.68 lakh, and current assets cover 0.88 times current liabilities. Reserves improved by Rs 6.18 crore in the quarter, Rs 3.30 crore more than the Q1 profit; the report does not explain the difference. The accumulated loss is still Rs 1.33 arba.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised) | Rs 3.91 |
| Net worth per share | Rs 54.98 |
| Market price (Ashwin end) | Rs 208 |
| P/E (annualised) | 53.20x |
| P/B | 3.78x |
At the Ashwin-end price of Rs 208, the share trades at 53.20 times annualised EPS and 3.78 times net worth per share. Net worth per share is only Rs 54.98, so the price is 3.78 times book value. The P/E is based on the strongest (monsoon) quarter; the last full year was a loss, so the full-year EPS is likely to be much lower than Rs 3.91.
Conclusion
Positives: first profit in five quarters, finance cost down 48.24%, higher other income, right-share money used to cut debt.
Watch: electricity sales down 9.76% in the peak season, receivables of Rs 43.88 crore with very little cash, net worth per share about half of face value, an unexplained Rs 3.30 crore extra rise in reserves, and a full year of losses behind it.
The coming quarters will show whether the lower interest cost keeps SSHL profitable in the dry season, when sales usually drop. Collecting the large receivables and cutting the remaining Rs 2.86 arba of loans are the key things to watch.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

