













Sanima Middle Tamor Hydropower Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
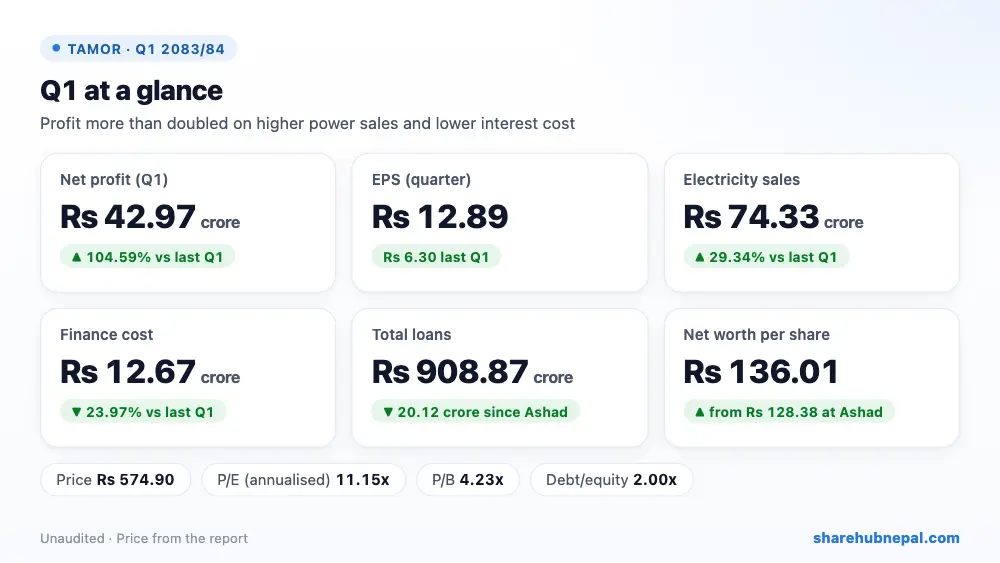
Summary
Sanima Middle Tamor Hydropower (73 MW Middle Tamor project) earned a net profit of Rs 42.97 crore in the first quarter, more than double the Rs 21.00 crore of a year ago (+104.59%). EPS for the quarter is Rs 12.89.
Electricity sales rose 29.34% to Rs 74.33 crore while plant costs rose only 3.47%. Finance cost fell 23.97% to Rs 12.67 crore as loans came down, and a foreign-exchange gain of Rs 46.66 lakh replaced last year's loss of Rs 79.86 lakh. The Ashad-end figures in this report are audited.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Electricity sales | Rs 743,276,247 | Rs 574,666,865 | +29.34% |
| Gross profit | Rs 685,038,686 | Rs 518,382,221 | +32.15% |
| Net operating profit (before interest) | Rs 550,466,433 | Rs 383,308,682 | +43.61% |
| Finance cost | Rs 126,679,773 | Rs 166,622,146 | −23.97% |
| Net profit | Rs 429,667,288 | Rs 210,016,407 | +104.59% |
| EPS (quarter) | 12.89 | 6.30 | – |
1. Where the profit came from
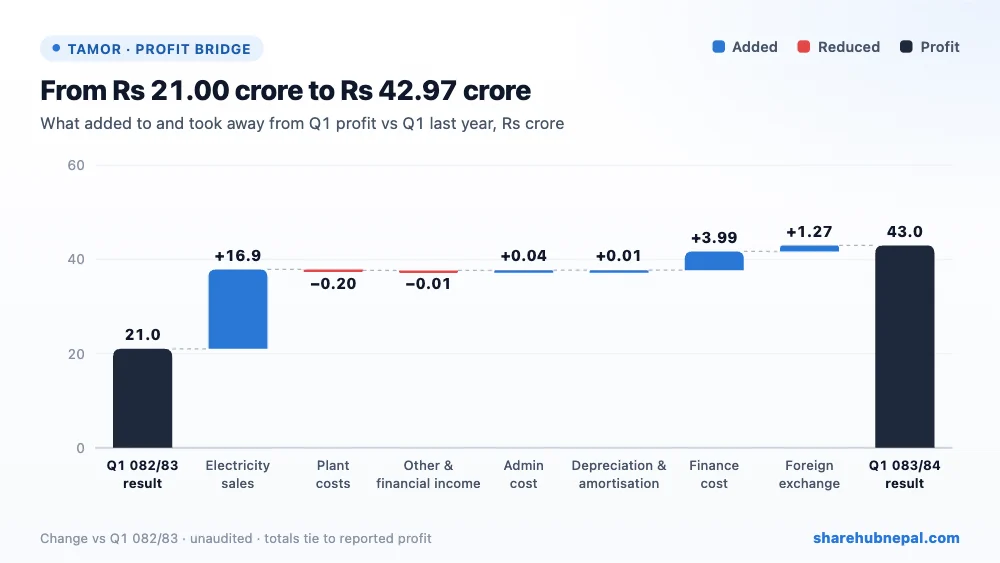
Compared with last year's Q1, higher electricity sales added Rs 16.86 crore, lower finance cost Rs 3.99 crore and the swing from a foreign-exchange loss to a gain Rs 1.27 crore. Lower administrative cost added Rs 4.32 lakh. Higher plant costs took away Rs 19.53 lakh and slightly lower financial income Rs 61,770.
2. Profit through the year
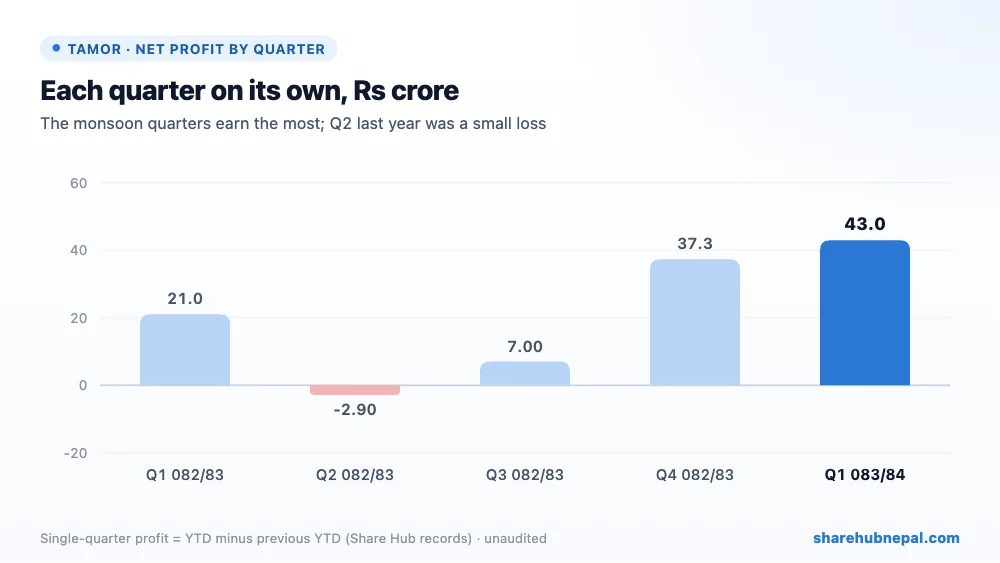
Based on Share Hub's records, single-quarter profits in 2082/83 were Rs 21.00 crore in Q1, a loss of Rs 2.90 crore in Q2, Rs 7.00 crore in Q3 and Rs 37.33 crore in Q4. The monsoon quarters (Q1 and Q4) earn most of the year's profit. The audited full-year 2082/83 profit in this report is Rs 62.12 crore, slightly below the Rs 62.43 crore in the Q4 report.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Long-term borrowings | Rs 8,655,533,549 | Rs 8,655,533,549 | +0.00% |
| Current borrowings | Rs 433,160,000 | Rs 634,324,800 | −31.71% |
| Intangible (project) assets | Rs 12,610,344,086 | Rs 12,729,750,184 | −0.94% |
| Cash and cash equivalents | Rs 70,061,689 | Rs 207,015,471 | −66.16% |
| Total assets | Rs 14,039,217,314 | Rs 14,333,093,620 | −2.05% |
| Total equity | Rs 4,541,546,241 | Rs 4,287,273,532 | +5.93% |
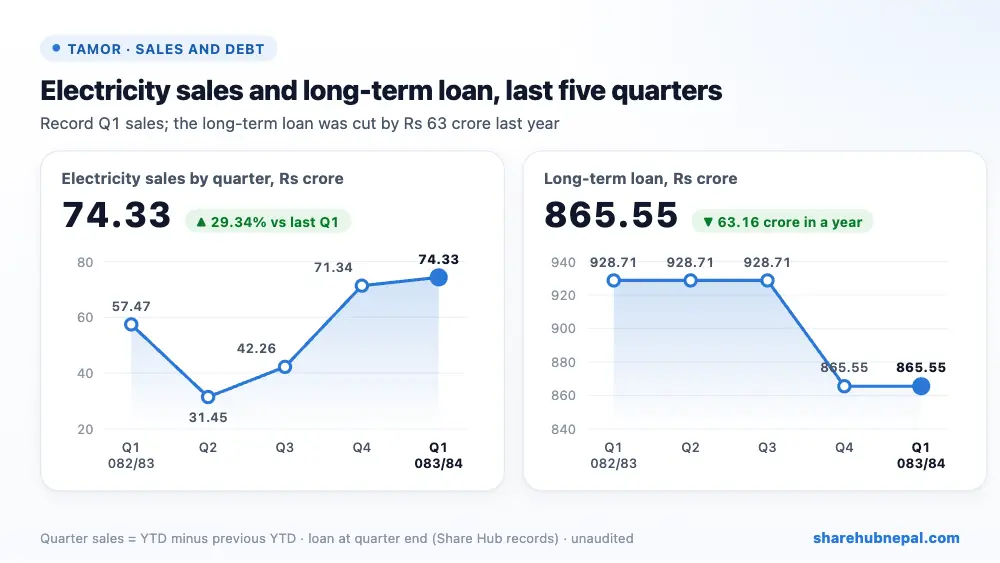
Current borrowings fell to Rs 43.32 crore from Rs 63.43 crore at Ashad end, while the long-term loan stayed at Rs 865.55 crore (Rs 928.71 crore a year ago). Total debt of Rs 908.87 crore is 2.00 times equity. Cash fell to Rs 7.01 crore from Rs 20.70 crore and other financial liabilities fell to Rs 27.02 crore from Rs 63.72 crore as payables were cleared. The current ratio improved to 1.80 from 1.16. Equity rose to Rs 4.54 arba and net worth per share to Rs 136.01.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (quarter) | Rs 12.89 |
| EPS (annualised) | Rs 51.56 |
| Net worth per share | Rs 136.01 |
| Market price (report) | Rs 574.90 |
| P/E on annualised EPS | 11.15x |
| P/B | 4.23x |
| Current ratio | 1.80 |
At Rs 574.90 the share trades at 11.15 times annualised Q1 EPS and 4.23 times net worth per share. The report's own P/E of 44.59 uses the quarter's EPS. Q1 is the best season for hydropower, so the full year will not earn four times this quarter: last year's full-year EPS was Rs 18.64, a P/E of about 30.84 at today's price.
Conclusion
Positives: profit up 104.59%, electricity sales up 29.34%, finance cost down 23.97%, short-term borrowing reduced, better liquidity (current ratio 1.80), and audited Ashad-end figures.
Watch: high debt (2.00 times equity), seasonality (a loss in Q2 last year), lower cash, a premium to net worth (4.23x), and dependence on river flow and NEA dispatch.
Middle Tamor had an excellent monsoon quarter, helped by more power sales and a lighter interest bill. The dry-season quarters will decide how much of this carries into the full-year result.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

