













United Modi Hydropower Ltd. – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
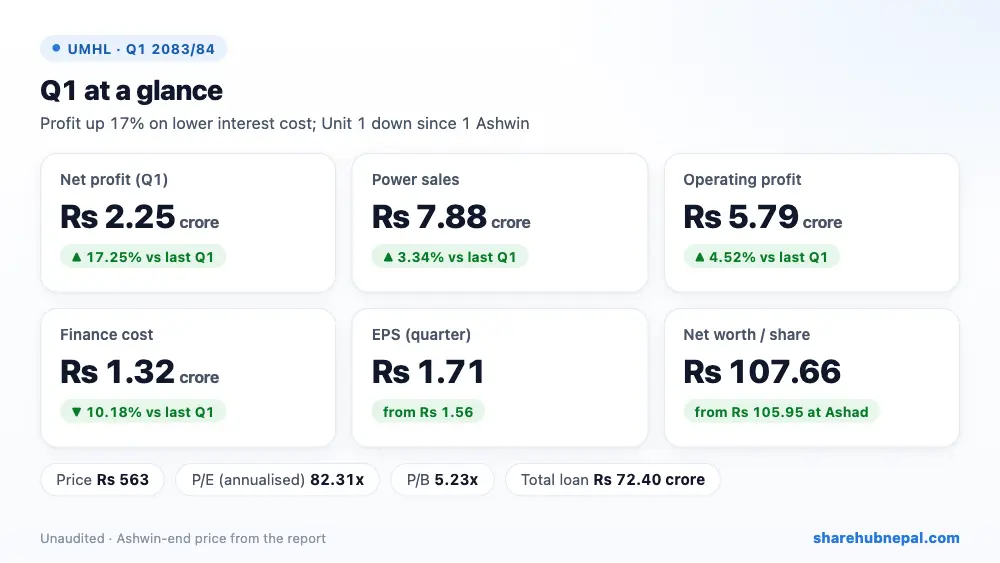
United Modi Hydropower earned Rs 2.25 crore in the first quarter of 2083/84, up 17.25% from Rs 1.92 crore a year ago. Power sales rose 3.34% to Rs 7.88 crore and finance cost fell 10.18% to Rs 1.32 crore, which more than covered higher staff and operating costs. Quarter EPS is Rs 1.71 (about Rs 6.84 annualised). The company also warned that Unit 1 has been out since the night of 1 Ashwin 2083 because of damage to a generator phase coil and a fault in the main PLC control, and this will cut power income until it is repaired.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Revenue from sales | Rs 78,809,000 | Rs 76,260,000 | +3.34% |
| Cost of sales | Rs 3,770,000 | Rs 4,990,000 | −24.45% |
| Other income | Rs 59,000 | Rs 80,000 | −26.25% |
| Operating profit | Rs 57,870,000 | Rs 55,365,000 | +4.52% |
| Finance cost | Rs 13,182,000 | Rs 14,676,000 | −10.18% |
| Income tax | Rs 5,622,000 | Rs 4,795,000 | +17.25% |
| Net profit | Rs 22,490,000 | Rs 19,181,000 | +17.25% |
| EPS (quarter) | 1.71 | 1.56 | – |
| Net worth per share | 107.66 | 109.24 | – |
1. Where the profit came from
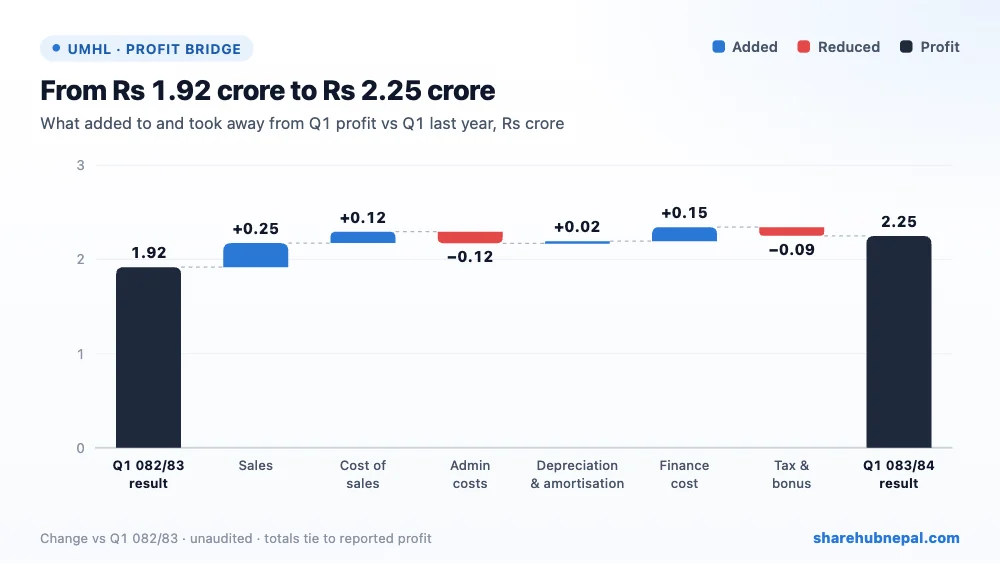
Higher sales added Rs 25.49 lakh, lower direct expenses Rs 12.20 lakh and lower finance cost Rs 14.94 lakh. Staff and other operating costs took away Rs 12.43 lakh and income tax plus staff bonus Rs 9.12 lakh more than last year. Net effect: profit up Rs 33.09 lakh.
2. Profit through the year
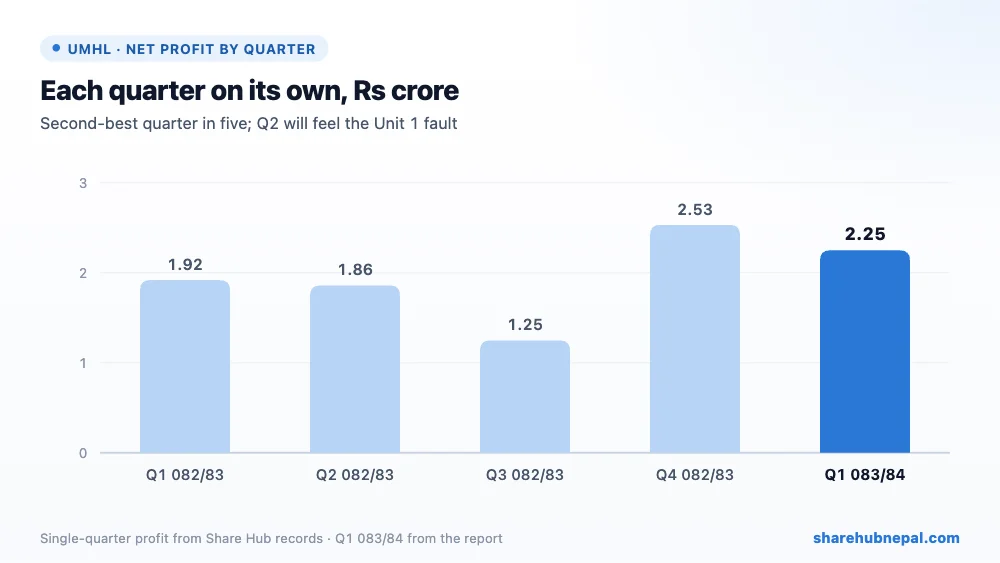
Profit by quarter (Share Hub records): Q1 082/83: Rs 1.92 crore, Q2 082/83: Rs 1.86 crore, Q3 082/83: Rs 1.25 crore, Q4 082/83: Rs 2.53 crore, Q1 083/84: Rs 2.25 crore. FY 2082/83 profit was Rs 7.56 crore (EPS Rs 5.74). This Q1 is close to last year's best quarter, but Q2 will depend on how fast Unit 1 is repaired.
3. Debt and balance sheet
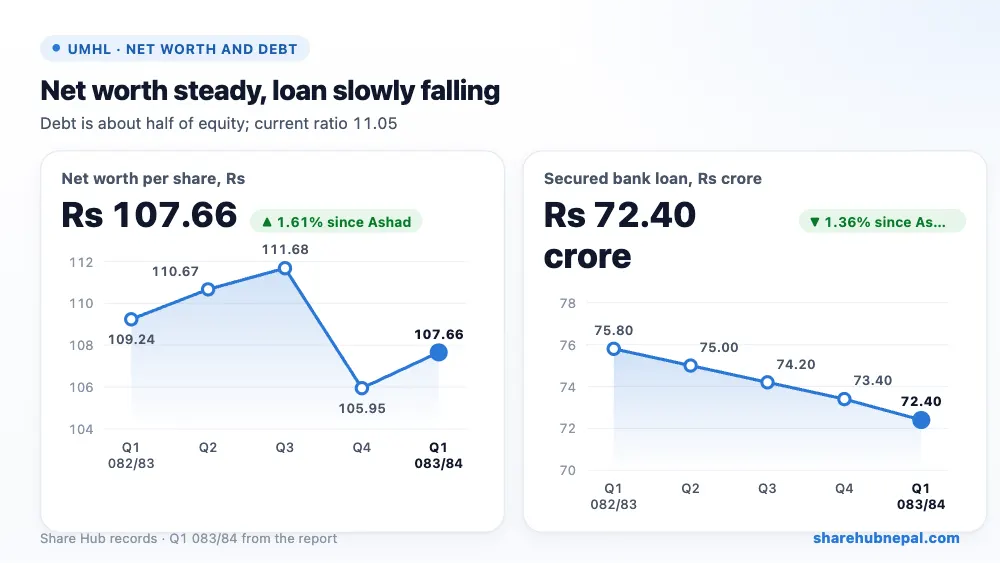
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Total assets | Rs 2,196,874,000 | Rs 2,210,594,000 | −0.62% |
| Total equity | Rs 1,417,500,000 | Rs 1,395,010,000 | +1.61% |
| Long-term borrowings | Rs 724,000,000 | Rs 734,000,000 | −1.36% |
| Cash and equivalents | Rs 74,011,000 | Rs 90,236,000 | −17.98% |
The balance sheet is sound. Equity rose by the quarter's profit to Rs 141.75 crore (Rs 107.66 per share). The secured bank loan fell to Rs 72.40 crore from Rs 73.40 crore, about half of equity. Current assets of Rs 24.66 crore are 11 times current liabilities, and cash and bank balance is Rs 7.40 crore (down from Rs 9.02 crore after the dividend payable of Rs 1.49 crore was cleared). The company also holds a long-term investment of Rs 68 crore.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised) | Rs 6.84 |
| Net worth per share | Rs 107.66 |
| Market price (Ashwin end) | Rs 563 |
| P/E (annualised) | 82.31x |
| P/B | 5.23x |
At the Ashwin-end price of Rs 563, the share trades at 82.31 times annualised EPS and 5.23 times net worth per share. Even on last year's full-year EPS of Rs 5.74 the P/E is about 98, so the price already assumes much better earnings than the plant has delivered.
Conclusion
Positives: profit up 17%, finance cost down 10%, loan falling, strong liquidity (current ratio 11).
Watch: Unit 1 out of service since 1 Ashwin 2083 (generator coil and PLC fault), staff and operating costs up 8%, high P/E.
A good Q1, but the Unit 1 breakdown is the key risk for Q2; watch the repair news before reading too much into this quarter.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

