













Butwal Power Company Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
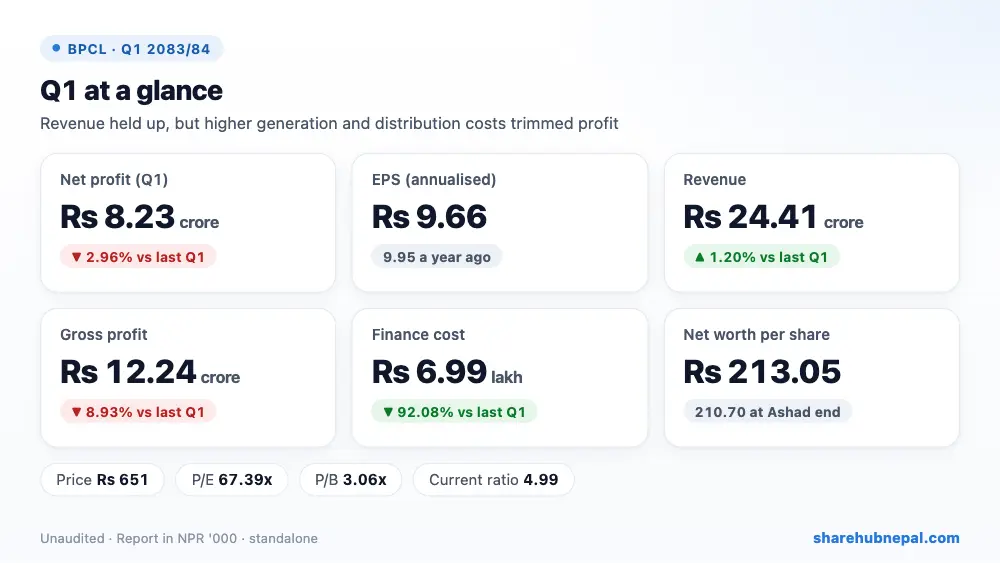
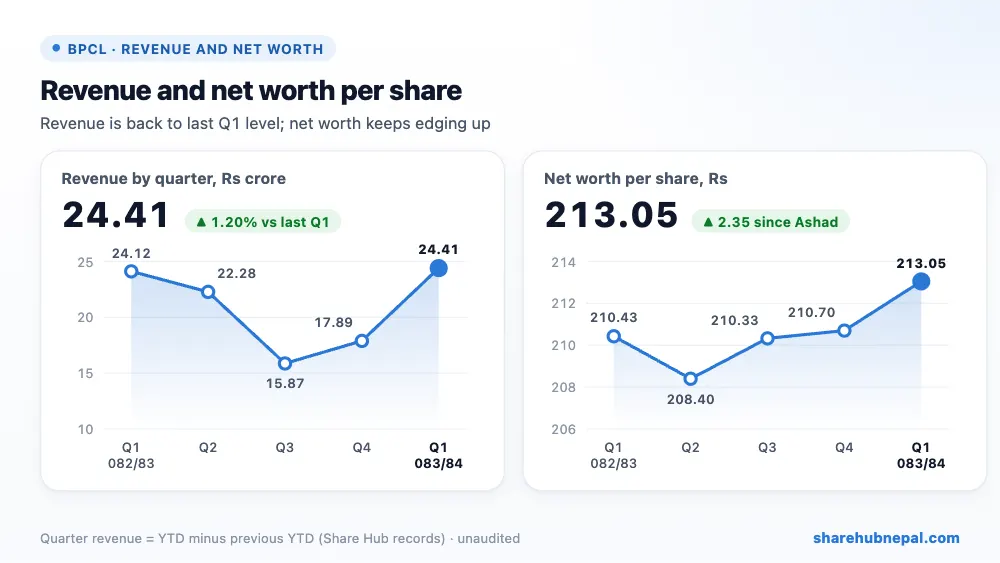
Butwal Power Company (BPC) earned a net profit of Rs 8.23 crore in the first quarter of 2083/84, down 2.96% from Rs 8.48 crore a year ago. Annualised EPS is Rs 9.66 (Rs 9.95 last year) and net worth per share rose to Rs 213.05.
Revenue from electricity and services grew only 1.20% to Rs 24.41 crore, while generation cost rose 15.17% and distribution cost 11.95%, so gross profit fell 8.94% to Rs 12.24 crore. Admin cost also rose 10.55%. The fall in profit was kept small because BPC has almost no loan now: finance cost dropped from Rs 88.31 lakh to Rs 6.99 lakh, and finance income nearly doubled on higher bank deposits.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Revenue (electricity and services) | Rs 244,110,000 | Rs 241,214,000 | +1.20% |
| Generation expenses | Rs 76,998,000 | Rs 66,858,000 | +15.17% |
| Distribution expenses | Rs 44,675,000 | Rs 39,906,000 | +11.95% |
| Gross profit | Rs 122,437,000 | Rs 134,450,000 | −8.93% |
| Other income (incl. grant amortisation) | Rs 13,767,000 | Rs 10,958,000 | +25.63% |
| Administrative and other operating expenses | Rs 33,604,000 | Rs 30,396,000 | +10.55% |
| Profit from operation | Rs 102,600,000 | Rs 115,012,000 | −10.79% |
| Finance costs | Rs 699,000 | Rs 8,831,000 | −92.08% |
| Income tax | Rs 20,040,000 | Rs 21,604,000 | −7.24% |
| Net profit | Rs 82,295,000 | Rs 84,802,000 | −2.96% |
| EPS (annualised) | 9.66 | 9.95 | – |
1. Where the profit came from
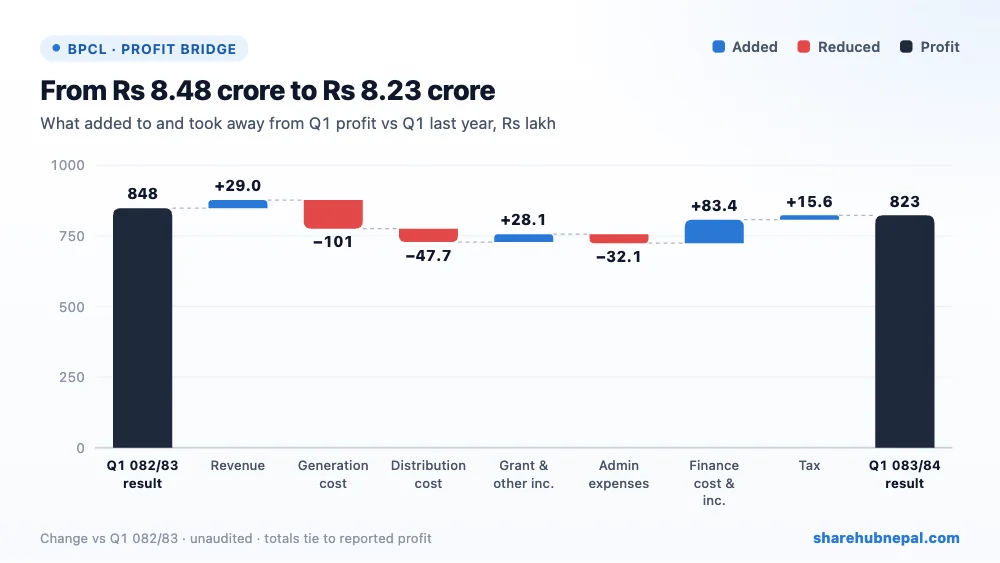
Compared with last year's Q1, higher generation cost took away Rs 1.01 crore, higher distribution cost Rs 47.69 lakh and higher admin cost Rs 32.08 lakh. Lower finance cost and higher finance income added back Rs 83.41 lakh, slightly higher revenue Rs 28.96 lakh, grant amortisation and other income Rs 28.09 lakh, and lower tax Rs 15.64 lakh. The net result is Rs 25.07 lakh less profit.
2. Profit through the year
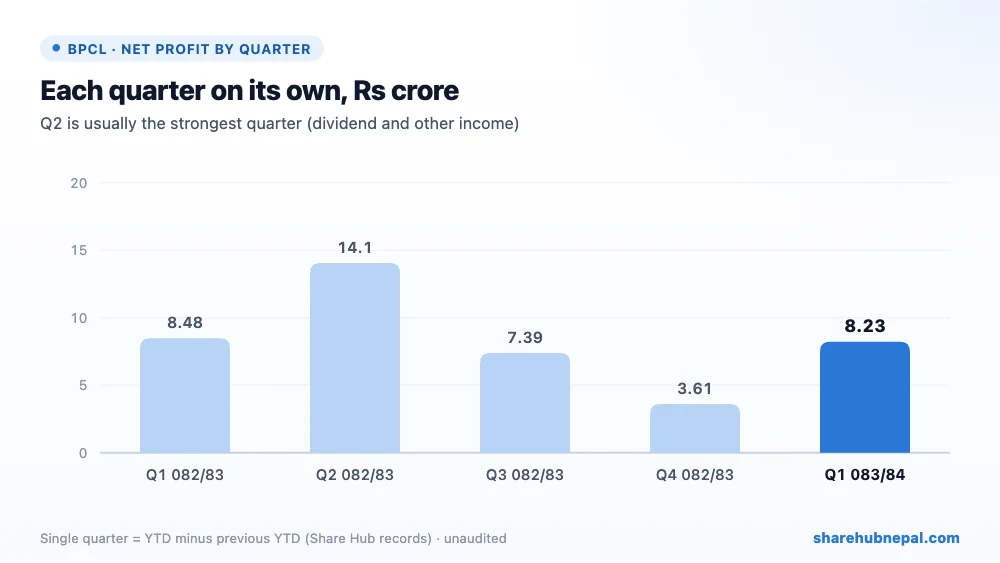
Based on Share Hub's records, single-quarter profit in 2082/83 was Rs 8.48 crore in Q1, Rs 14.06 crore in Q2 (when most of the other and dividend income came in), Rs 7.39 crore in Q3 and Rs 3.61 crore in Q4. FY 2082/83 profit was Rs 33.54 crore. This Q1 is close to last year's Q1, so the year has started at a similar pace. Quarterly revenue came back to Rs 24.41 crore from Rs 17.89 crore in Q4, as the monsoon months bring the most generation.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Property, plant and equipment | Rs 289,910,000 | Rs 295,727,000 | −1.97% |
| Intangible assets | Rs 1,678,083,000 | Rs 1,658,113,000 | +1.20% |
| Project work-in-progress | Rs 444,662,000 | Rs 430,628,000 | +3.26% |
| Long-term financial assets (investments) | Rs 4,706,058,000 | Rs 4,348,907,000 | +8.21% |
| Cash and cash equivalents | Rs 469,989,000 | Rs 731,224,000 | −35.73% |
| Current liabilities | Rs 163,868,000 | Rs 159,378,000 | +2.82% |
| Total equity | Rs 7,263,150,000 | Rs 7,188,627,000 | +1.04% |
BPC's balance sheet is strong. Equity is Rs 7.26 arba against total liabilities of only Rs 67.39 crore, and long-term borrowings are just Rs 3.09 crore. Most of the money is in long-term investments (Rs 4.71 arba, up Rs 35.72 crore in Q1, including Rs 36 crore advanced to Manang Marshyangdi Hydropower) and the plants' intangible and fixed assets. Cash fell from Rs 73.12 crore to Rs 47.00 crore as it went into these projects, but the current ratio is still 4.99.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised) | Rs 9.66 |
| Net worth per share | Rs 213.05 |
| Total assets per share | Rs 232.82 |
| Market price (Q1 close) | Rs 651 |
| P/E (on annualised EPS) | 67.39x |
| P/B | 3.06x |
| Current ratio | 4.99 |
| Return on assets (quarter, report) | 1.04% |
The Q1 closing price was Rs 651 (range Rs 625.50 to Rs 706.40). On annualised EPS of Rs 9.66 the P/E is about 67 times (the report's 270.12 uses the quarter EPS). The price is 3.06 times net worth per share. This is a high P/E for current profit; the market is pricing BPC's long-term pipeline — the 601 MW Marsyangdi Cascade, Nyadi's full evacuation and the Chino Khola project — more than this year's earnings.
Conclusion
Positives: almost no debt, finance cost nearly gone, rising interest income, current ratio 4.99, steady revenue, NEA's agreement to fully evacuate power from Nyadi now that the Upper Marsyangdi-A switching station is complete, and a large project pipeline.
Watch: generation and distribution costs growing faster than revenue, the financial health of the distribution business (the company names it as a key internal challenge), the large cash needs of the Marsyangdi Cascade, the ongoing talks with NEA on transferring 50% of Himal Power's project assets and a new PPA, and a P/E that already prices in future growth.
A steady but slightly weaker start: BPC's core business earns about the same as last year, costs are creeping up, and the debt-free balance sheet keeps profit stable. The bigger story is the new projects, which will need years of investment before they add to earnings.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

