













Dordi Khola Jal Bidyut Company Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
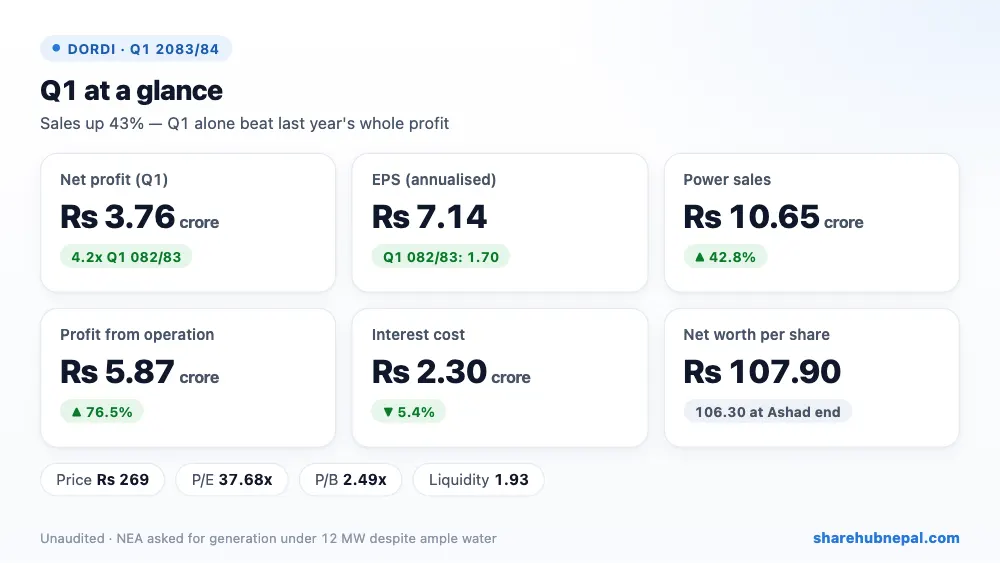
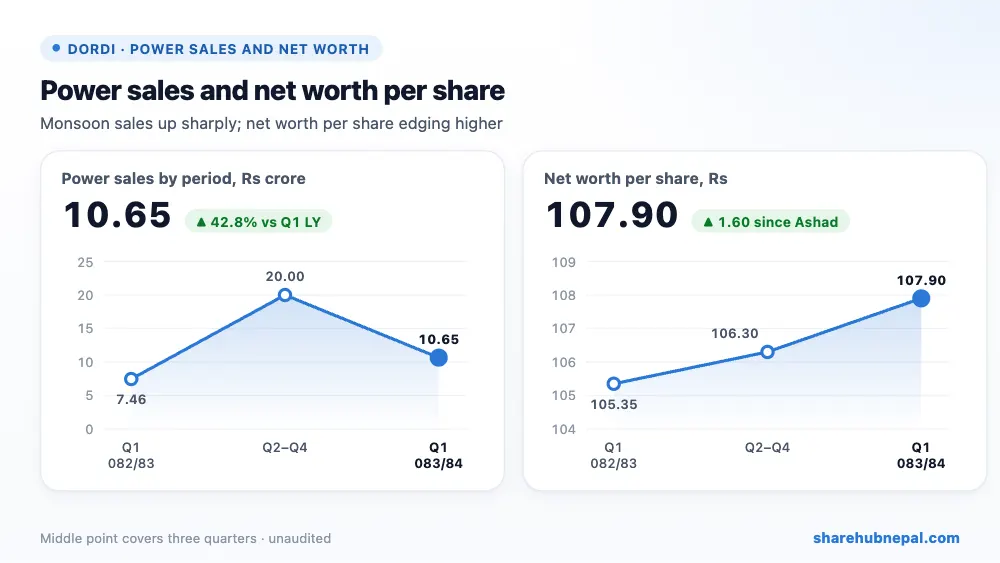
Dordi Khola Jal Bidyut earned a net profit of Rs 3.76 crore in the first quarter of 2083/84, 4.2 times the Rs 89.38 lakh of a year ago and more than its whole profit for 2082/83 (Rs 3.00 crore). Annualised EPS is Rs 7.14 (1.70 a year ago) and net worth per share is Rs 107.90.
Revenue rose 42.77% to Rs 10.65 crore, so profit from operation grew 76.52% to Rs 5.87 crore. Interest fell a little and a deferred tax credit of Rs 19.70 lakh also helped. The result could have been better: the company says NEA told it to generate less than 12 MW at times even though the river had plenty of water.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Revenue | Rs 106,505,866 | Rs 74,601,023 | +42.77% |
| Generation expenses | Rs 14,202,415 | Rs 8,573,074 | +65.66% |
| Depreciation | Rs 29,166,372 | Rs 28,885,495 | +0.97% |
| Other income | Rs 4,379,835 | Rs 5,459,187 | −19.77% |
| Administrative and other expenses | Rs 8,819,099 | Rs 9,348,295 | −5.66% |
| Profit from operation | Rs 58,697,814 | Rs 33,253,345 | +76.52% |
| Finance costs | Rs 23,038,503 | Rs 24,355,742 | −5.41% |
| Net profit | Rs 37,629,259 | Rs 8,937,894 | +321.01% |
1. Where the profit came from
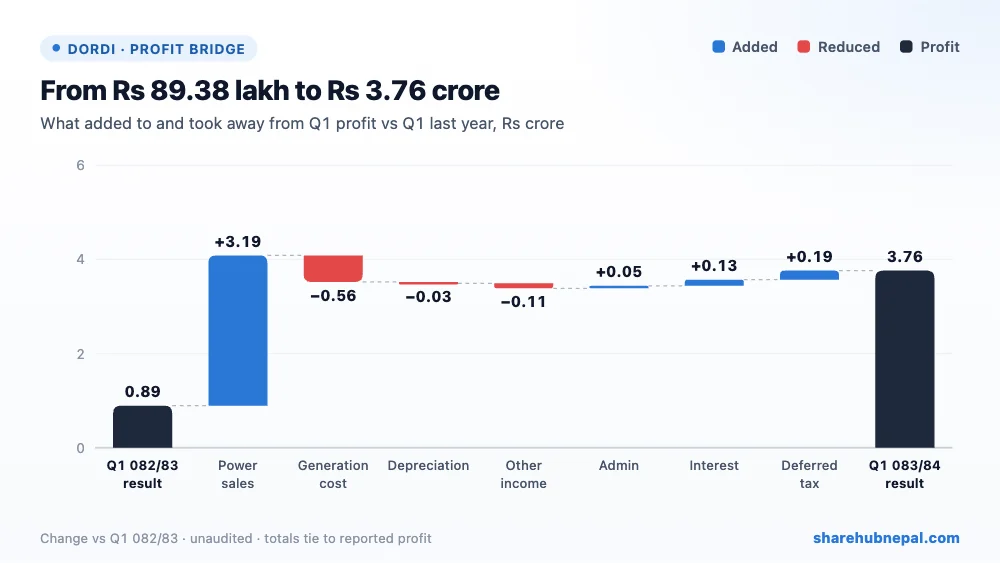
Against Q1 last year, higher power sales added Rs 3.19 crore, the deferred tax credit Rs 19.30 lakh, lower interest Rs 13.17 lakh and lower admin cost Rs 5.29 lakh. Higher generation cost took away Rs 56.29 lakh, lower other income Rs 10.79 lakh and higher depreciation Rs 2.81 lakh. Net: profit up Rs 2.87 crore.
2. Profit through the year
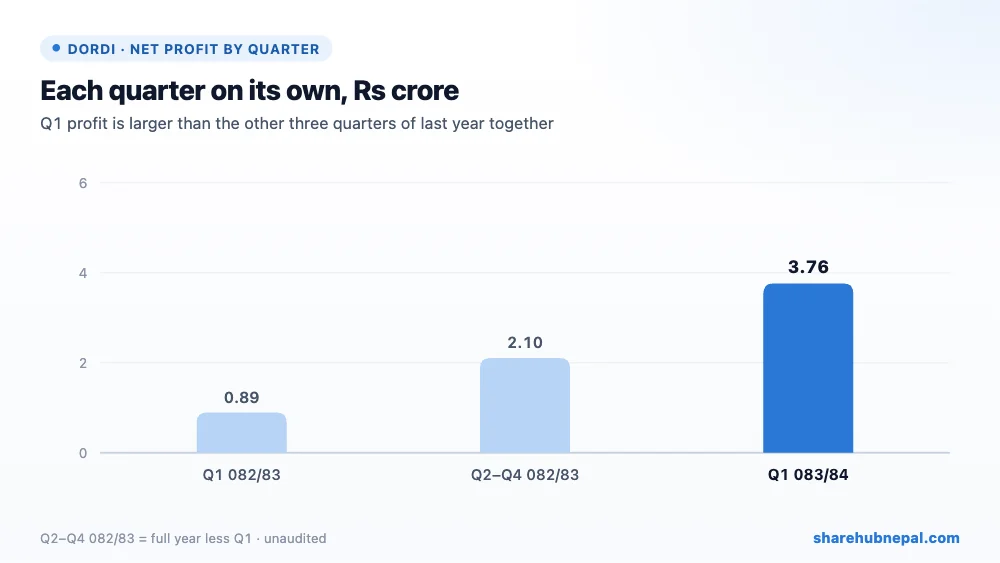
In 2082/83 DORDI earned Rs 89.38 lakh in Q1 and Rs 2.10 crore in the other three quarters together, for a full-year profit of Rs 3.00 crore (EPS 1.42). This Q1 is much stronger, but as a monsoon quarter it overstates the year; the annualised EPS of 7.14 should be read with care. The company enjoys a full income-tax holiday for its first ten years of operation and 50% for the next five.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Property, plant and equipment | Rs 2,574,918,536 | Rs 2,603,557,340 | −1.10% |
| Projects under development and investments | Rs 798,313,089 | Rs 795,739,589 | +0.32% |
| Trade receivables (NEA) | Rs 248,859,284 | Rs 223,031,323 | +11.58% |
| Cash and cash equivalents | Rs 60,632,682 | Rs 41,604,781 | +45.73% |
| Long-term borrowings | Rs 925,379,367 | Rs 944,396,568 | −2.01% |
| Short-term borrowings | Rs 97,538,960 | Rs 92,959,865 | +4.93% |
| Total equity | Rs 2,275,028,709 | Rs 2,241,320,260 | +1.50% |
Long-term borrowings are Rs 92.54 crore and short-term Rs 9.75 crore (about 0.45 times equity), plus Rs 98.33 crore of other financial liabilities. Liquidity is fine (ratio 1.93). NEA owed Rs 24.89 crore at Ashwin end. The company is studying two more projects: Myagdi Khola (A), 30 MW (generation licence received 9 Magh 2082), and Super Ingkhu Khola, 24.41 MW (licence in process). A right share of 1:0.28847474, approved by the ERC on 15 Baisakh 2083, is being filed at SEBON to repay long-term loans.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised, report) | Rs 7.14 |
| EPS (quarter, derived) | Rs 1.78 |
| Net worth per share | Rs 107.90 |
| Total assets per share | Rs 203.56 |
| Market price (Q1 close) | Rs 269 |
| P/E (report) | 37.68x |
| P/B | 2.49x |
| Liquidity ratio | 1.93 |
The Q1 closing price was Rs 269 (range Rs 232.10 to Rs 271). The P/E is 37.68 on the annualised Q1 EPS and the price is 2.49 times net worth per share. On last year's EPS of 1.42 the P/E would be very high, so the price assumes a much better year.
Conclusion
Positives: profit up 4.2 times, sales up 43%, lower interest, tax holiday, new project licences, and an approved right share to cut debt.
Watch: NEA's instructions to generate below capacity, weaker dry-season quarters, large other financial liabilities, the right share (more shares), and the small unexplained gap between profit and the rise in equity.
DORDI had a strong monsoon quarter. If NEA lets the plant run at full capacity and the right share cuts debt, the improvement can last beyond Q1.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

