













Union Hydropower Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
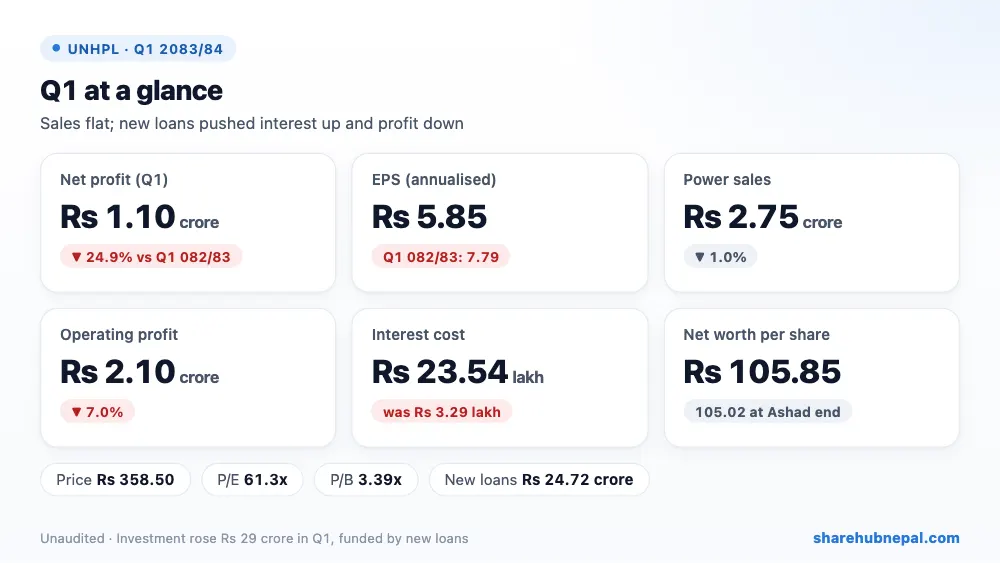
Union Hydropower (the report calls it Union Hydro Holding), which runs the Midim Khola (Karapu) plant, earned a net profit of Rs 1.10 crore in the first quarter of 2083/84, down 24.86% from Rs 1.46 crore a year ago. Annualised EPS is Rs 5.85 (7.79 a year ago) and net worth per share is Rs 105.85.
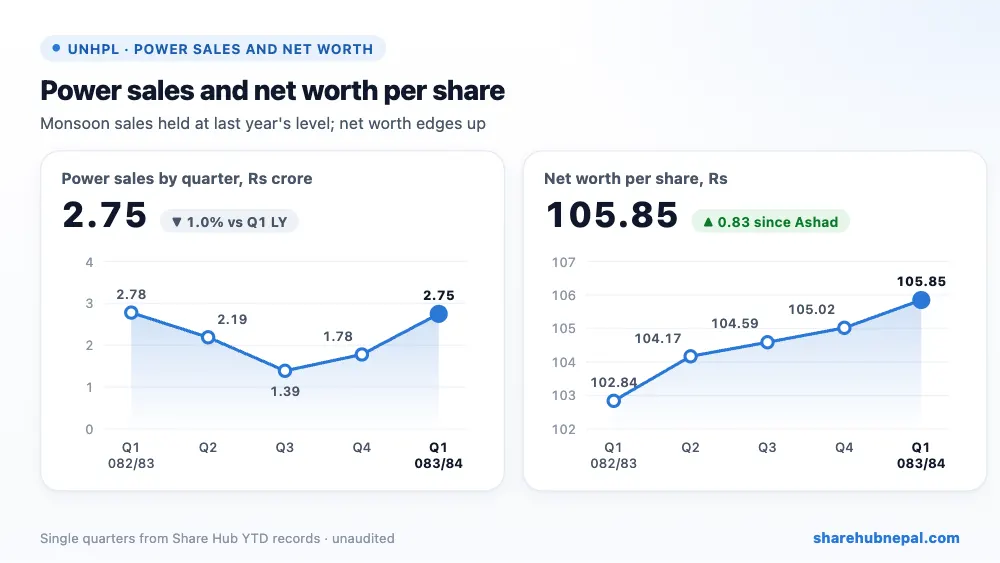
Power sales were almost the same as last year (Rs 2.75 crore vs Rs 2.78 crore); the company says generation matched last year, though interruptions on NEA's Damauli–Bhotetar 33 kV line keep hurting output. The fall in profit came from costs: interest rose from Rs 3.29 lakh to Rs 23.54 lakh after the company took new loans, and administrative expenses rose 27.45%.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Income from power sales | Rs 27,488,157 | Rs 27,751,907 | −0.95% |
| Royalty | Rs 624,897 | Rs 540,914 | +15.53% |
| Administrative expenses | Rs 5,877,599 | Rs 4,611,681 | +27.45% |
| Operating profit | Rs 21,006,941 | Rs 22,599,562 | −7.05% |
| Interest expenses | Rs 2,353,713 | Rs 329,094 | +615.21% |
| Depreciation | Rs 7,422,829 | Rs 7,369,026 | +0.73% |
| Net profit | Rs 10,973,096 | Rs 14,603,413 | −24.86% |
1. Where the profit came from
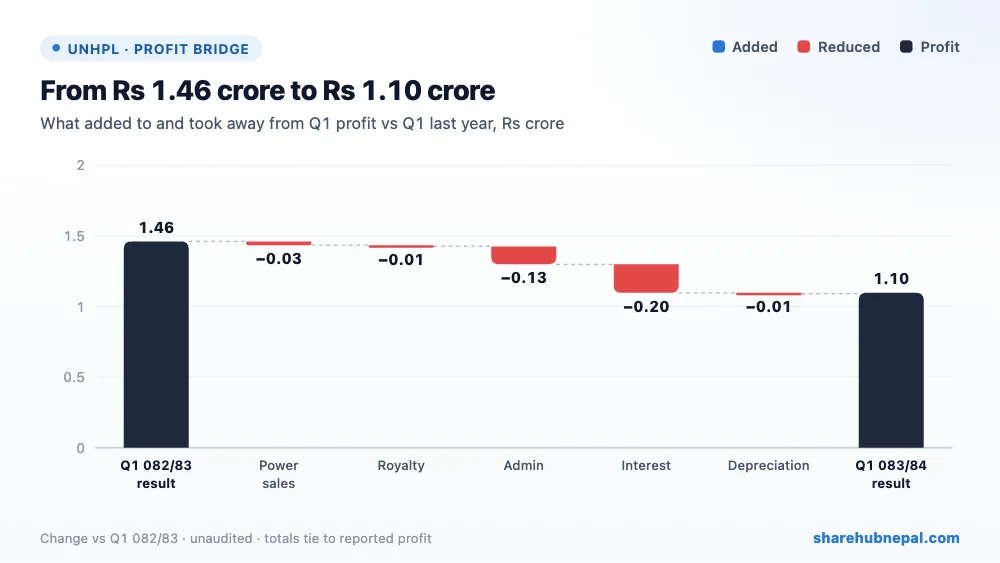
Against Q1 last year, higher interest took away Rs 20.25 lakh, higher administrative expenses Rs 12.66 lakh, lower power sales Rs 2.64 lakh and higher royalty Rs 0.84 lakh. Depreciation was almost unchanged. Together profit fell Rs 36.30 lakh.
2. Profit through the year
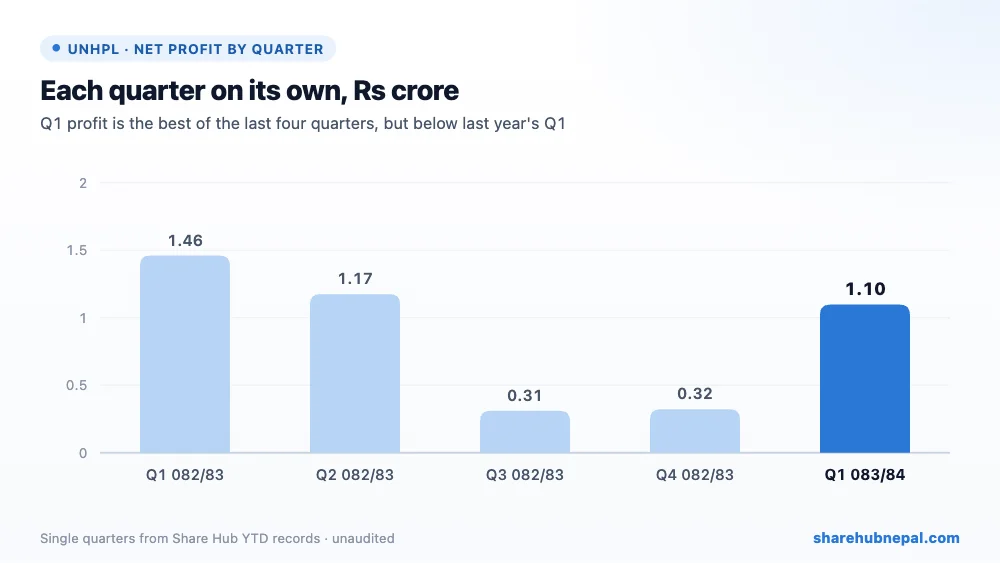
Last year the single-quarter profit fell from Rs 1.46 crore in Q1 to Rs 1.17 crore in Q2 and about Rs 31.05 lakh in each of Q3 and Q4, so the full-year profit was Rs 3.27 crore (EPS 4.36). This year's Q1 is again the strongest quarter. With interest now higher, the dry-season quarters may earn even less than last year, so the annualised EPS of 5.85 is likely to fall through the year.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Property, plant and equipment | Rs 596,963,699 | Rs 604,199,525 | −1.20% |
| Capital work in progress | Rs 72,354,559 | Rs 77,047,007 | −6.09% |
| Investment | Rs 292,103,700 | Rs 2,103,700 | +13785.24% |
| Cash and bank | Rs 288,121 | Rs 28,181,383 | −98.98% |
| Loan funds (long-term) | Rs 233,194,965 | Rs 0 | – |
| Short-term borrowing | Rs 14,053,537 | Rs 0 | – |
| Total equity | Rs 793,879,483 | Rs 787,619,343 | +0.79% |
The balance sheet changed a lot in one quarter. Investment rose from Rs 21.04 lakh to Rs 29.21 crore, paid for with new long-term loans of Rs 23.32 crore, short-term borrowing of Rs 1.41 crore and almost all of the cash (cash fell from Rs 2.82 crore to only Rs 2.88 lakh). The report does not say what the Rs 29 crore went into; the company is developing Lohdung Khola (28.9 MW) and Upper Tamor 'A' (60 MW), which have generation licences and are seeking power purchase agreements. Reserves also took a previous-year adjustment of Rs 47.13 lakh that is not explained. Debt is now 0.31 times equity.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised, report) | Rs 5.85 |
| EPS (quarter, derived) | Rs 1.46 |
| Net worth per share | Rs 105.85 |
| Total assets per share (report) | Rs 139.17 |
| Market price (Q1 close) | Rs 358.50 |
| P/E (report) | 61.28x |
| P/B | 3.39x |
| Debt to equity | 0.31x |
The Q1 closing price was Rs 358.50 (range Rs 337 to Rs 408.40). The P/E is 61.3 times on the annualised Q1 EPS and the price is 3.39 times net worth per share. On last year's full-year EPS of 4.36 the P/E would be about 82 times, which is expensive for a small plant whose profit is falling.
Conclusion
Positives: steady monsoon generation, no legal cases, net worth per share still rising, and two new projects (Lohdung Khola and Upper Tamor 'A') with generation licences.
Watch: what the new Rs 29 crore investment is and when it will earn, much higher interest from the new loans, almost no cash left, the unexplained Rs 47 lakh previous-year adjustment, NEA line interruptions, and the high P/E.
UNHPL's plant performed as usual, but the company is changing from a debt-free single-plant company into one that borrows to invest. Until the new investment starts earning, interest will keep pulling profit down.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

