













Green Ventures Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
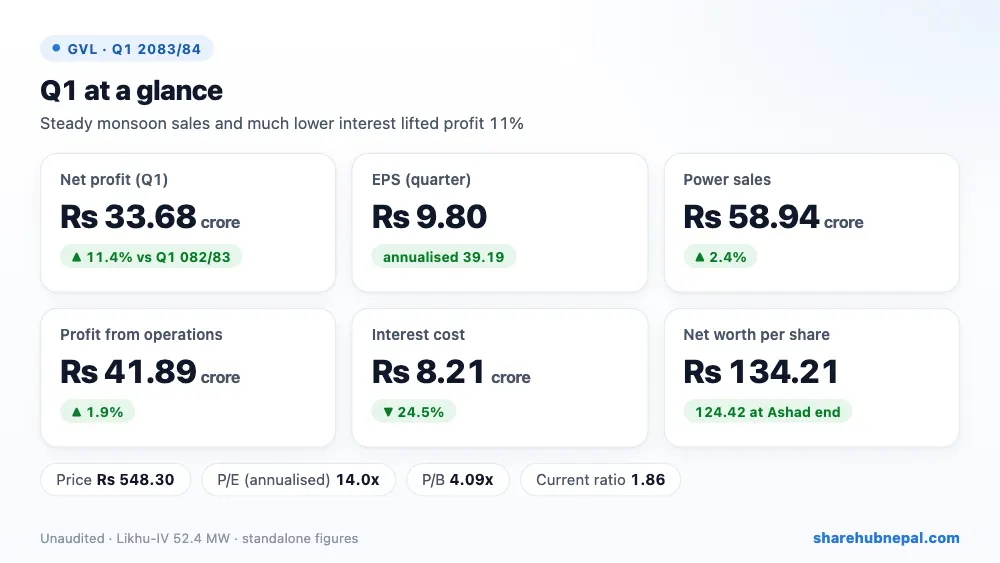
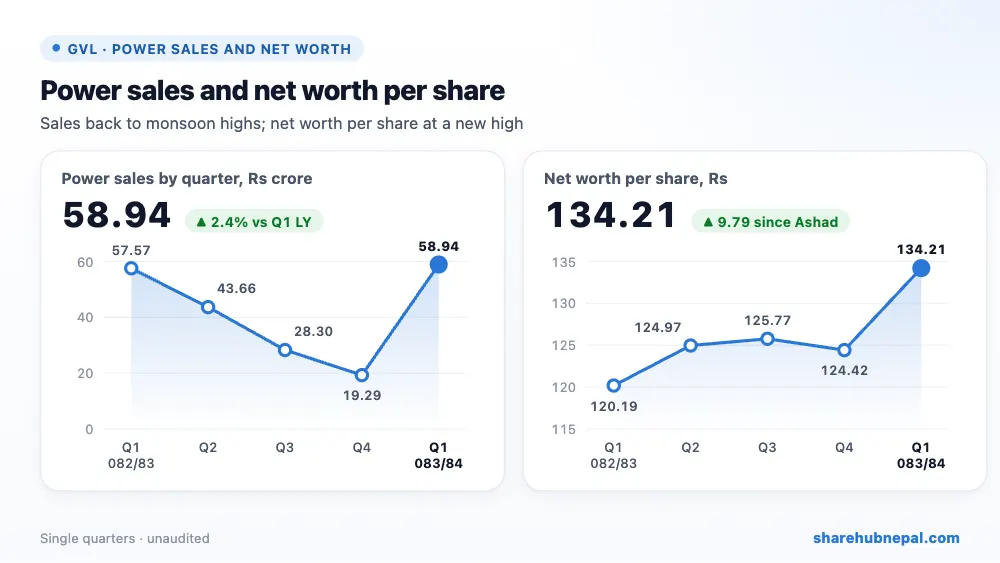
Green Ventures, owner of the 52.4 MW Likhu-IV plant, earned a net profit of Rs 33.68 crore in the first quarter of 2083/84, up 11.36% from Rs 30.24 crore a year ago. Quarter EPS is Rs 9.80 (about Rs 39.19 annualised) and net worth per share rose to Rs 134.21.
Electricity sales rose a little (2.37%) to Rs 58.94 crore. The bigger help came from interest: net finance cost fell 24.50% to Rs 8.21 crore as the company keeps paying down its loans. No staff bonus, CSR or tax was provided in Q1.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Revenue from operations | Rs 589,359,513 | Rs 575,731,549 | +2.37% |
| Generation expenses | Rs 163,459,722 | Rs 157,078,889 | +4.06% |
| Other income | Rs 1,317,775 | Rs 0 | – |
| Administrative expenses | Rs 8,328,321 | Rs 7,463,891 | +11.58% |
| Profit from operations | Rs 418,889,245 | Rs 411,188,769 | +1.87% |
| Net finance costs | Rs 82,124,106 | Rs 108,770,689 | −24.50% |
| Net profit | Rs 336,765,138 | Rs 302,418,080 | +11.36% |
1. Where the profit came from
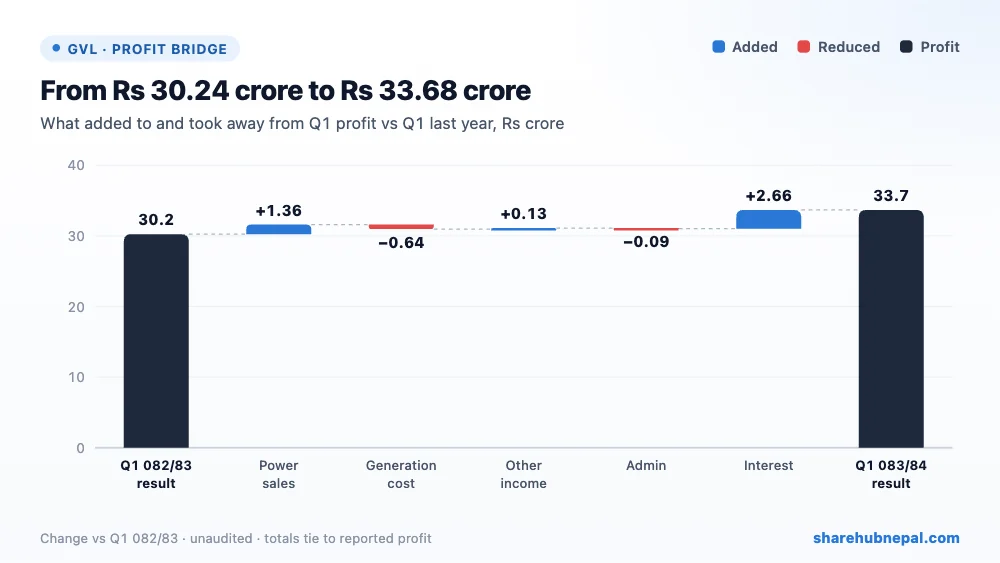
Against Q1 last year, lower interest added Rs 2.66 crore, higher power sales Rs 1.36 crore and other income Rs 13.18 lakh. Higher generation cost took away Rs 63.81 lakh and admin cost Rs 8.64 lakh. Net: profit up Rs 3.43 crore.
2. Profit through the year
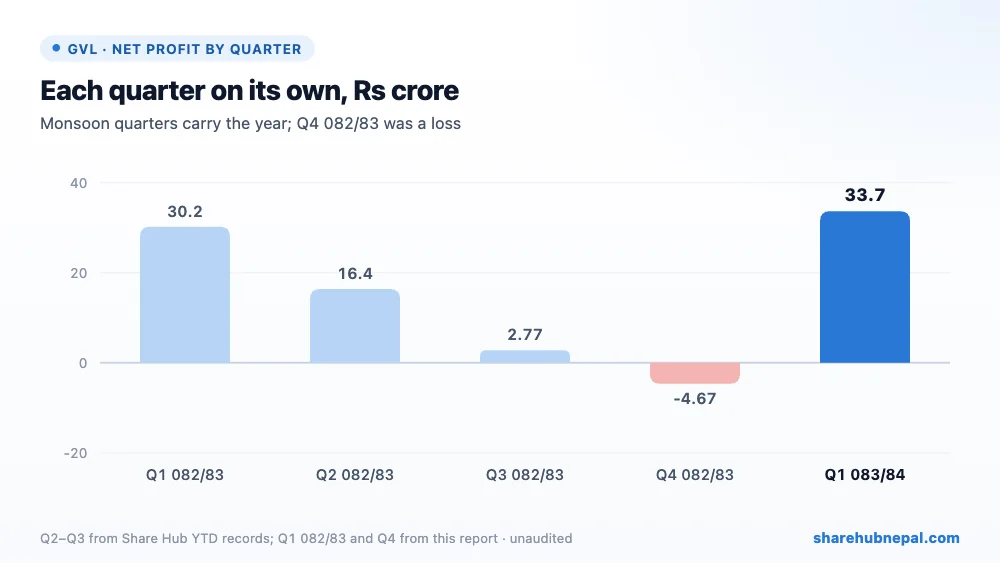
GVL's profit follows the river: last year it earned Rs 30.24 crore in Q1 and Rs 16.39 crore in Q2, then only Rs 2.77 crore in Q3 and a loss of Rs 4.67 crore in Q4 (year-end interest, bonus and CSR), for a full-year profit of Rs 44.77 crore (EPS 13.02). This Q1 is the best single quarter so far, but the annualised EPS of 39.19 will not hold through the dry season.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Intangible (project) assets | Rs 9,375,042,879 | Rs 9,483,974,876 | −1.15% |
| Investment (long-term) | Rs 241,753,533 | Rs 291,748,790 | −17.14% |
| Trade and other receivables | Rs 485,007,929 | Rs 363,312,690 | +33.50% |
| Cash and cash equivalents | Rs 528,708,486 | Rs 297,172,300 | +77.91% |
| Long-term loans | Rs 5,640,854,721 | Rs 5,811,129,721 | −2.93% |
| Short-term loans | Rs 662,050,000 | Rs 643,000,000 | +2.96% |
| Total equity | Rs 4,613,550,502 | Rs 4,276,780,621 | +7.87% |
Loans are large (Rs 5.64 arba long-term plus Rs 66.20 crore short-term, 1.37 times equity), but they are falling: long-term loans were Rs 6.33 arba a year ago. Cash rose to Rs 52.87 crore and NEA receivables to Rs 48.50 crore with the monsoon sales; the current ratio is 1.86. Long-term investment fell by Rs 5 crore to Rs 24.18 crore. Equity rose by exactly the quarter's comprehensive income.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (quarter, report) | Rs 9.80 |
| EPS (annualised, derived) | Rs 39.19 |
| Net worth per share | Rs 134.21 |
| Market price (Q1 close) | Rs 548.30 |
| P/E (report, quarter EPS) | 55.97x |
| P/E (annualised EPS) | 13.99x |
| P/B | 4.09x |
| Current ratio | 1.86 |
| Debt to equity | 1.37x |
The Q1 closing price was Rs 548.30 (range Rs 461 to Rs 554.20). The report's P/E of 55.97 uses the quarter EPS; on the annualised EPS it is 14.0 times, and on last year's EPS of 13.02 it is 42.1 times. The price is 4.09 times net worth per share.
Conclusion
Positives: higher profit, interest down 25%, loans falling, more cash, net worth per share at a new high, and no legal cases.
Watch: still-large loans, weaker dry-season quarters (Q4 082/83 was a loss), climate and landslide risk in the Likhu catchment, and year-end bonus, CSR and tax charges.
GVL had a solid monsoon quarter, helped mostly by lower interest. As loans keep falling, each year's profit should improve, but quarterly results will stay seasonal.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

