













Himalayan Distillery Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
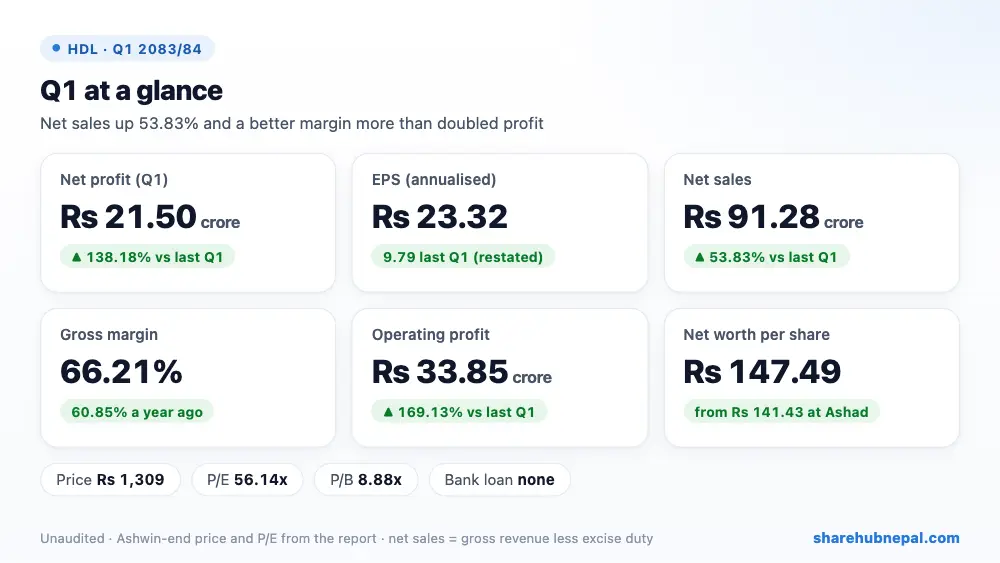
Summary
Himalayan Distillery earned a net profit of Rs 21.50 crore in the first quarter of FY 2083/84, up 138.18% from Rs 9.03 crore a year ago. Annualised EPS is Rs 23.32, against Rs 9.79 last year after adjusting for the bonus shares (Rs 11.75 before the adjustment).
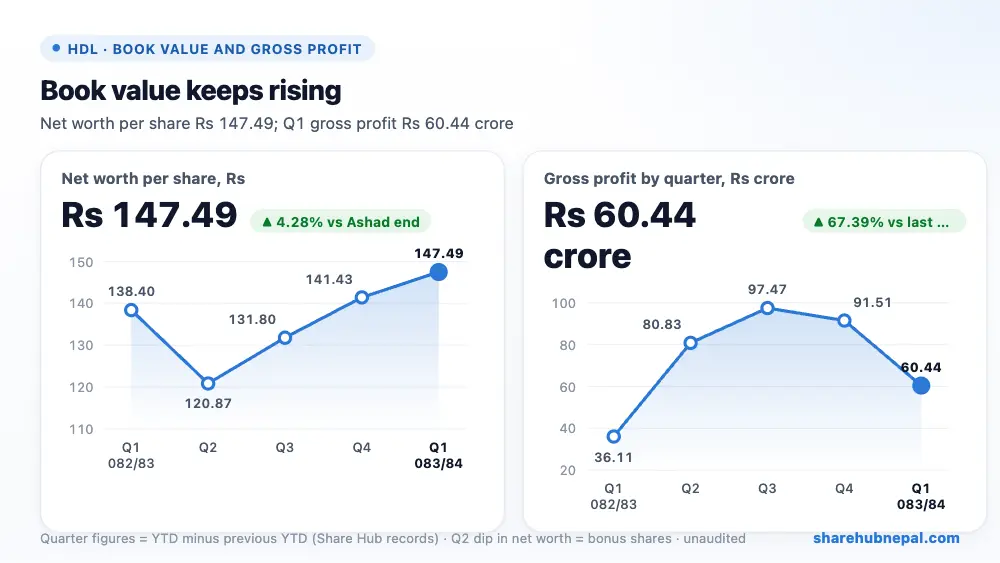
Gross revenue rose 63.87% to Rs 1.76 arba. After excise duty of Rs 85.00 crore, net sales were Rs 91.28 crore, up 53.83%. Cost of goods and manufacturing rose only 32.76%, so gross profit jumped 67.39% to Rs 60.44 crore and the gross margin improved to 66.21% from 60.85%. Selling and distribution cost fell 30.19%, and operating profit rose 169.13% to Rs 33.85 crore. Staff cost (+44.34%), admin cost (+97.18%) and tax (+260.08%) rose sharply, but could not stop the jump in profit.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Gross revenue | Rs 1,762,863,703 | Rs 1,075,788,930 | +63.87% |
| Excise duties | Rs 850,043,379 | Rs 482,399,910 | +76.21% |
| Net sales | Rs 912,820,324 | Rs 593,389,021 | +53.83% |
| Cost of goods and manufacturing | Rs 308,434,513 | Rs 232,322,897 | +32.76% |
| Gross profit | Rs 604,385,811 | Rs 361,066,124 | +67.39% |
| Employee expenses | Rs 116,822,341 | Rs 80,933,086 | +44.34% |
| Administration expenses | Rs 63,885,656 | Rs 32,399,743 | +97.18% |
| Selling and distribution | Rs 85,132,469 | Rs 121,941,463 | −30.19% |
| Operating profit | Rs 338,545,344 | Rs 125,791,831 | +169.13% |
| Non-operating income | Rs 13,343,731 | Rs 16,388,591 | −18.58% |
| Depreciation and amortisation | Rs 29,311,556 | Rs 21,781,049 | +34.57% |
| Income tax | Rs 106,385,889 | Rs 29,545,033 | +260.08% |
| Net profit | Rs 214,976,075 | Rs 90,258,164 | +138.18% |
| EPS (annualised) | 23.32 | 9.79 | – |
1. Where the profit came from
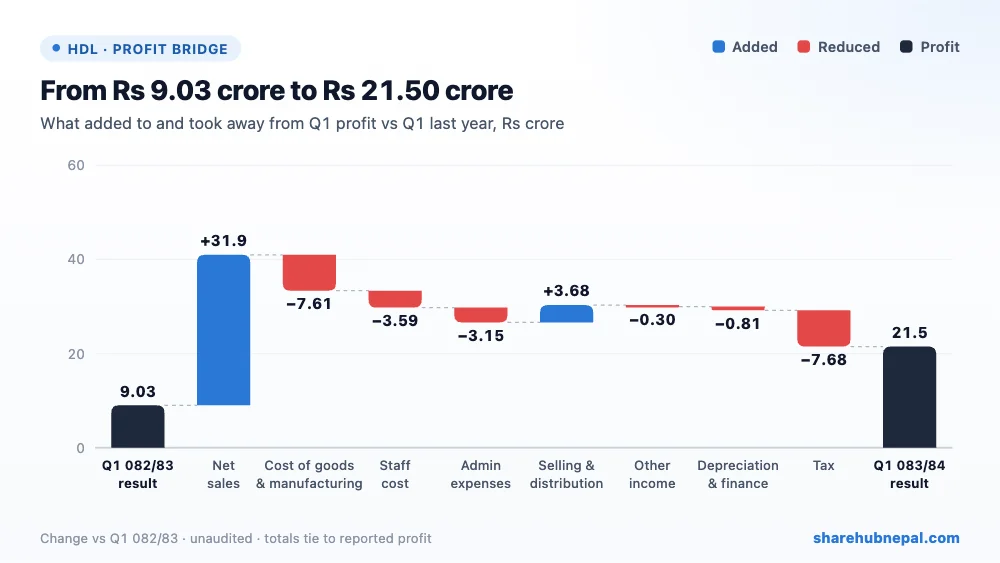
Compared with last year's Q1, higher net sales added Rs 31.94 crore and lower selling and distribution cost added Rs 3.68 crore. Against that, cost of goods and manufacturing took away Rs 7.61 crore, staff cost Rs 3.59 crore, admin cost Rs 3.15 crore, depreciation and finance cost Rs 81.50 lakh, lower other income Rs 30.45 lakh and higher tax Rs 7.68 crore. Net result: Rs 12.47 crore more profit. Tax took 33.10% of profit before tax, against 24.66% last year.
2. Profit through the year
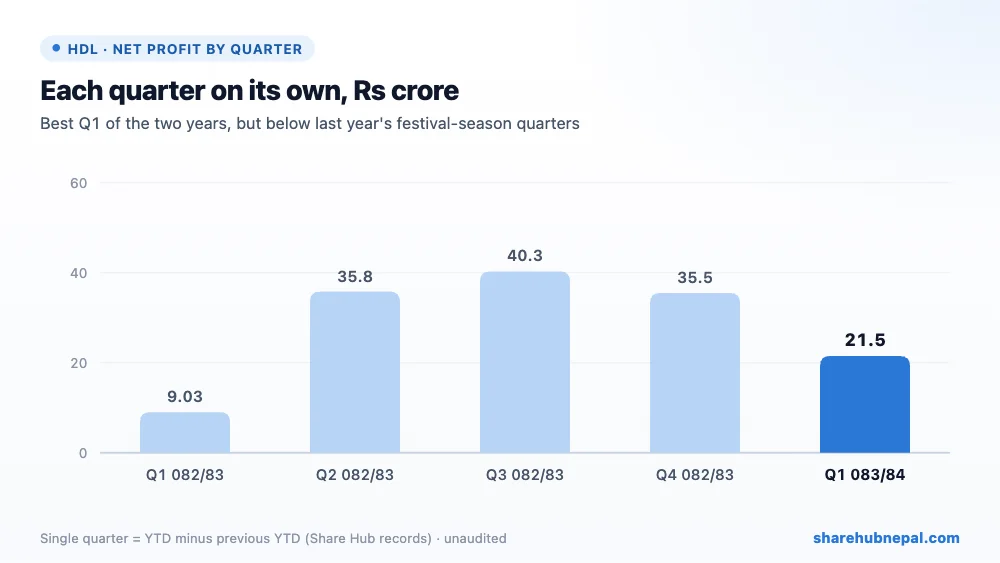
Based on Share Hub's records, single-quarter profit in 2082/83 was Rs 9.03 crore in Q1, Rs 35.81 crore in Q2, Rs 40.29 crore in Q3 and Rs 35.50 crore in Q4, for a full-year profit of Rs 1.21 arba (EPS Rs 32.71). Liquor demand peaks in the Dashain–Tihar festival season and in winter, so Q1 is usually the slowest quarter. This Q1 is more than double last year's, but part of the jump may be stock sent to distributors before Dashain (receivables rose 46.41%).
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Property, plant and equipment | Rs 1,079,754,546 | Rs 1,101,733,030 | −1.99% |
| Inventories | Rs 764,260,278 | Rs 717,818,598 | +6.47% |
| Trade receivables | Rs 1,421,869,130 | Rs 971,182,123 | +46.41% |
| Cash and cash equivalents | Rs 941,993,738 | Rs 1,179,270,222 | −20.12% |
| Other bank balances (deposits) | Rs 1,650,000,000 | Rs 1,450,000,000 | +13.79% |
| Current liabilities | Rs 773,590,435 | Rs 472,299,987 | +63.79% |
| Total equity | Rs 5,439,443,482 | Rs 5,215,905,516 | +4.29% |
The company has no bank loans. Cash and fixed deposits total Rs 2.59 arba (cash Rs 94.20 crore plus Rs 1.65 arba in other bank balances), and current assets are 6.36 times current liabilities. Trade receivables jumped 46.41% since Ashad end to Rs 1.42 arba, which is more than the quarter's net sales; the company itself names slow payment by distributors as a challenge. Inventories rose 6.47% to Rs 76.43 crore. Capital work in progress rose to Rs 4.47 crore as the company plans a new bottling hall of about 60,000 sq ft (contractor selection in the final stage) and a canning line. Equity rose to Rs 5.44 arba; reserves rose Rs 85.62 lakh more than the Q1 profit, which the report does not explain.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised, report) | Rs 23.32 |
| Net worth per share | Rs 147.49 |
| Total assets per share | Rs 170.68 |
| Market price (Ashwin end) | Rs 1,309 |
| P/E (report) | 56.14x |
| P/B | 8.88x |
| Liquidity ratio | 6.36 |
At the Ashwin-end price of Rs 1,309 the share trades at 56.14 times annualised EPS and 8.88 times net worth per share. On last year's full-year EPS of Rs 32.71 the P/E is about 40. The price already expects strong growth from the new brands (Shlok Premium XXX rum, the planned Shlok Single Malt Whisky and the Passion Cooler ready-to-drink coolers).
Conclusion
Positives: profit up 138.18%, net sales up 53.83%, a better gross margin (66.21%), lower selling cost, no bank debt, large cash and deposits (liquidity ratio 6.36), and new products — Shlok Premium XXX rum launched, single malt whisky approved, and 5% ready-to-drink coolers.
Watch: receivables up 46.41% to Rs 1.42 arba, admin cost nearly doubled, a higher effective tax rate (33.10%), long-running tax assessment disputes (FY 2067/68, 2072/73, 2074/75 and 2079/80), a labour-court case, the ban on liquor advertising, competition from cheap plastic-bottle liquor, and a P/B of 8.88.
A strong start to the year, driven by sales and margin rather than one-off income. Watch whether distributors pay on time, how the festival quarters turn out, and whether the new brands and the bottling-hall expansion keep sales growing.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

