













Menchhiyam Hydropower Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
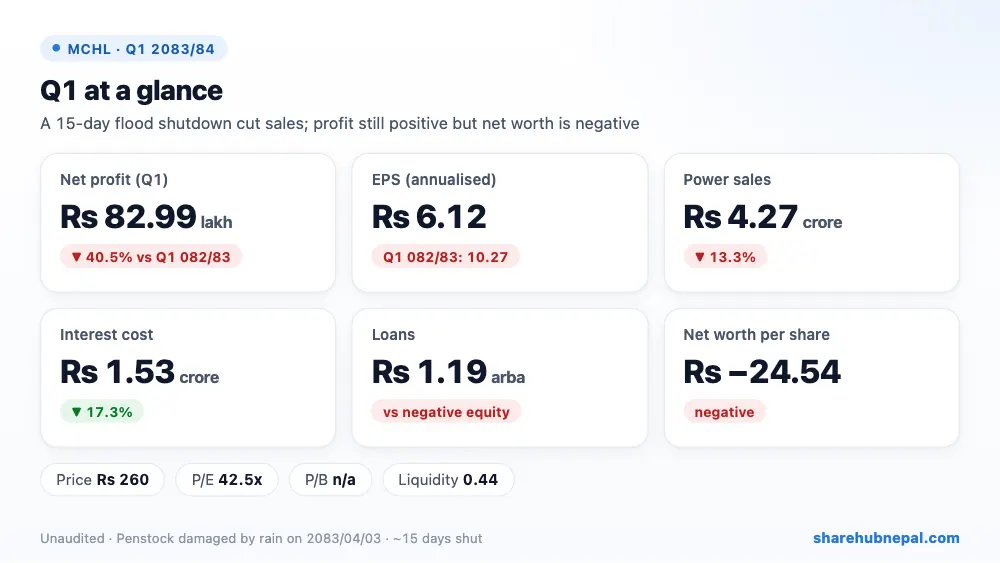
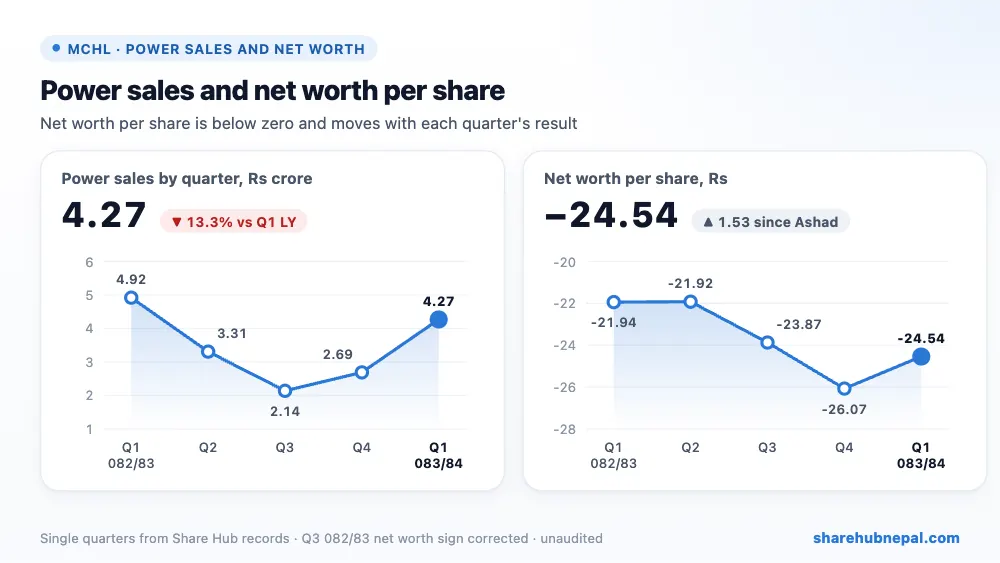
Menchhiyam Hydropower earned a net profit of Rs 82.99 lakh in the first quarter of 2083/84, down 40.45% from Rs 1.39 crore a year ago. Annualised EPS is Rs 6.12 (10.27 a year ago). The bigger concern is the balance sheet: accumulated losses of Rs 67.57 crore are larger than the share capital, so net worth per share is negative (Rs −24.54).
Heavy rain in Sankhuwasabha on 3 Shrawan 2083 fully damaged the plant's water-supply pipe (penstock), and generation stopped for about 15 days for repairs. Electricity sales fell 13.34% to Rs 4.27 crore and repair cost rose to Rs 20.19 lakh. Lower interest (Rs 1.53 crore) softened the fall.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Electricity sale to NEA | Rs 42,660,482 | Rs 49,229,818 | −13.34% |
| Cost of sales | Rs 1,191,250 | Rs 1,426,224 | −16.48% |
| Administrative expenses | Rs 3,114,918 | Rs 2,285,056 | +36.32% |
| Repair and maintenance | Rs 2,018,522 | Rs 30,965 | +6418.72% |
| Profit before interest, depreciation and tax | Rs 36,335,793 | Rs 45,487,573 | −20.12% |
| Financial expense | Rs 15,288,542 | Rs 18,489,916 | −17.31% |
| Depreciation and amortisation | Rs 12,747,980 | Rs 13,060,147 | −2.39% |
| Net profit | Rs 8,299,271 | Rs 13,937,510 | −40.45% |
1. Where the profit came from
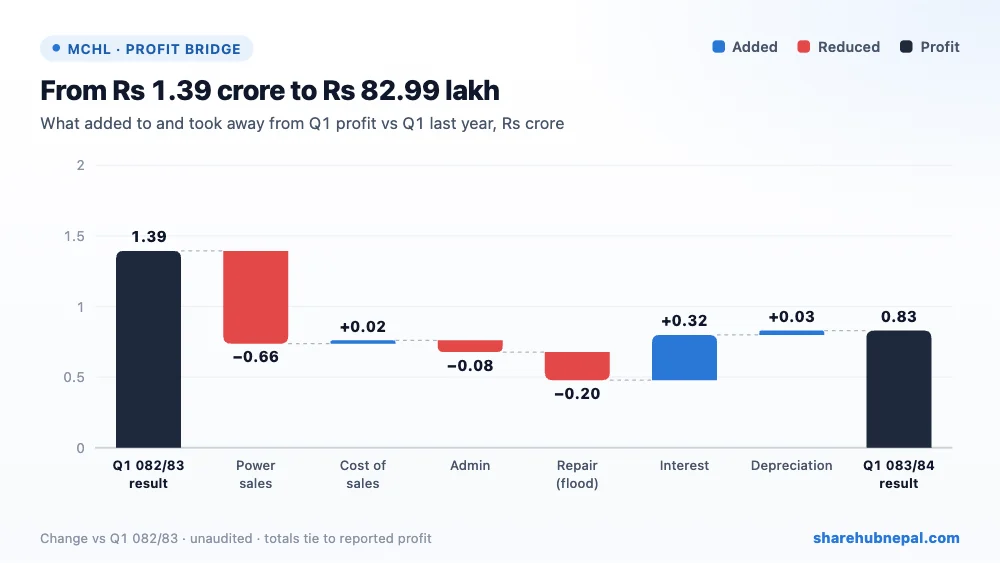
Against Q1 last year, lost power sales took away Rs 65.69 lakh, flood repairs Rs 19.88 lakh and higher admin cost Rs 8.30 lakh. Lower interest gave back Rs 32.01 lakh, and depreciation and cost of sales were a little lower. Net: profit down Rs 56.38 lakh.
2. Profit through the year
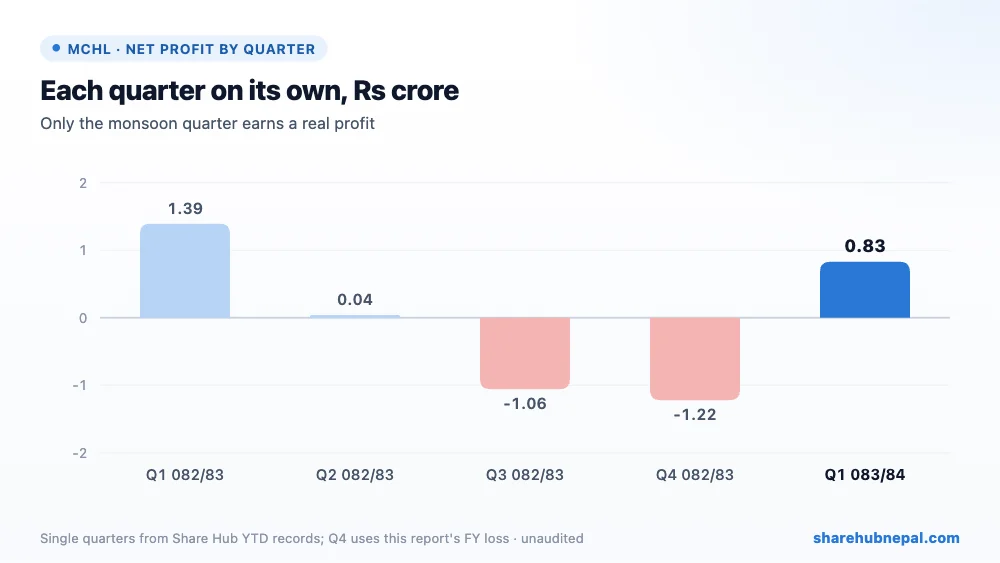
MCHL makes money only in the wet season. Last year Q1 earned Rs 1.39 crore, Q2 almost nothing, and Q3 and Q4 were losses of about Rs 1.06 crore and Rs 1.22 crore, so 2082/83 ended in a loss of Rs 84.33 lakh (per this report; Share Hub's Q4 record shows Rs 55.93 lakh). Expect this Q1 profit to be eaten up again in the dry season.
3. Debt and balance sheet
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Property, plant and equipment | Rs 1,204,963,894 | Rs 1,217,711,874 | −1.05% |
| Debtors and receivables | Rs 29,600,058 | Rs 21,367,901 | +38.53% |
| Cash and bank | Rs 3,159,998 | Rs 1,736,494 | +81.98% |
| Secured long-term loan | Rs 1,166,428,840 | Rs 1,171,196,122 | −0.41% |
| Sundry creditors and payables | Rs 207,605,191 | Rs 212,945,390 | −2.51% |
| Total equity (negative) | −Rs 133,143,229 | −Rs 141,442,500 | +5.87% |
The company owes Rs 1.17 arba in long-term loans plus Rs 1.90 crore short-term and Rs 20.76 crore to creditors, against negative equity of −Rs 13.31 crore. Current liabilities (Rs 29.27 crore) are far larger than current assets (Rs 12.10 crore); the liquidity ratio is 0.44. On the legal side, the Patan High Court decided on 15 Bhadra 2083 on appointing an arbitrator in the dispute between Rustako Nepal and the company; the certified copy and details are still awaited.
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised, report) | Rs 6.12 |
| EPS (quarter, derived) | Rs 1.53 |
| Net worth per share | Rs −24.54 |
| Total assets per share | Rs 244.38 |
| Market price (Q1 close) | Rs 260 |
| P/E (report) | 42.50x |
| Liquidity ratio | 0.44 |
The Q1 closing price was Rs 260 (range Rs 232 to Rs 306). The P/E is 42.5 on the annualised Q1 EPS, which is the best quarter of the year; on a full-year basis the company has been loss-making. With negative net worth, the share price has no book value support at all.
Conclusion
Positives: the plant is back after the flood repair, Q1 still made a profit, interest cost is falling, and loans are being repaid slowly.
Watch: negative net worth, weak liquidity (0.44), losses in the dry season, flood risk to the penstock, the arbitration with Rustako Nepal, and the gap between this report's FY 2082/83 loss and Share Hub's Q4 record.
MCHL remains a weak company: a small seasonal profit cannot yet repair years of accumulated losses. Investors should treat the Q1 EPS with care.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

