













Sun Nepal Life Insurance Company Limited – First Quarter Analysis, FY 2083/84
Unaudited results as on Ashwin end 2083, compared with the same quarter last year (Ashwin end 2082) and with Ashad end 2083.
Summary
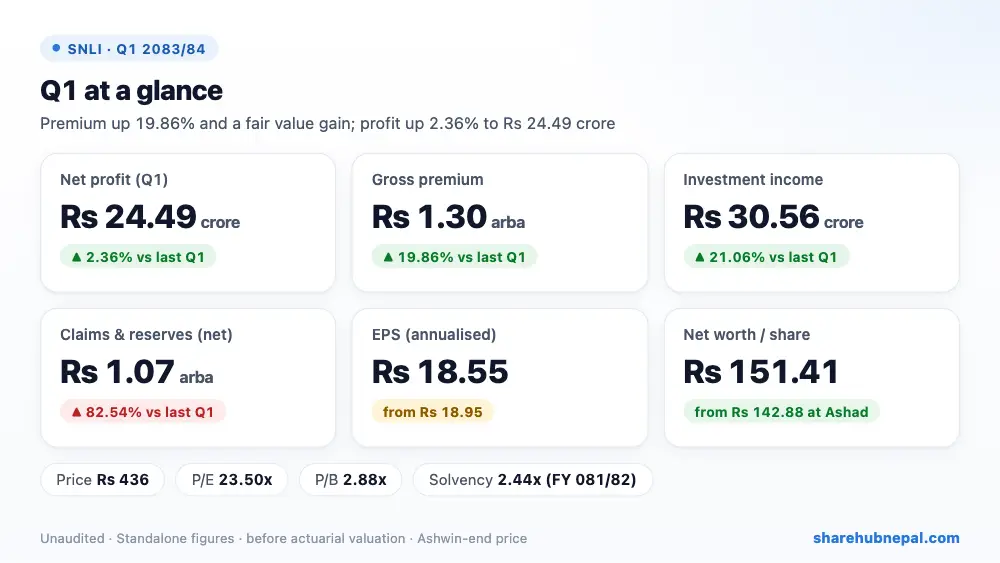
Sun Nepal Life earned Rs 24.49 crore in the first quarter of FY 2083/84 (standalone), up 2.36% from Rs 23.93 crore a year ago. Gross earned premium rose 19.86% to Rs 1.30 arba and investment income rose 21.06% to Rs 30.56 crore. A fair value gain of Rs 6.13 crore on investments replaced last year's Rs 27.68 crore loss, but net claims and the addition to policy reserves rose 82.54% to Rs 1.07 arba, and last year's Rs 6.70 crore tax credit did not repeat. Annualised EPS is Rs 18.55 and net worth per share Rs 151.41. These figures are before the actuarial valuation.
| Indicator | Q1 2083/84 | Q1 2082/83 | Change |
| Gross earned premium | Rs 1,298,679,336 | Rs 1,083,486,976 | +19.86% |
| Net earned premium | Rs 1,246,481,465 | Rs 1,041,496,192 | +19.68% |
| Income from investments and loans | Rs 305,577,398 | Rs 252,420,761 | +21.06% |
| Fair value gain/(loss) | Rs 61,254,091 | −Rs 276,796,580 | Turned to profit |
| Net benefits, claims and reserve change | Rs 1,074,365,238 | Rs 588,572,764 | +82.54% |
| Commission expenses | Rs 113,486,628 | Rs 91,331,017 | +24.26% |
| Employee benefits | Rs 122,071,015 | Rs 110,150,807 | +10.82% |
| Income tax (credit) | Rs 2,128,234 | −Rs 67,041,760 | Turned to profit |
| Net profit | Rs 244,923,996 | Rs 239,277,619 | +2.36% |
| EPS (annualised) | 18.55 | 18.95 | – |
| Net worth per share | 151.41 | 161.89 | – |
1. Where the profit came from
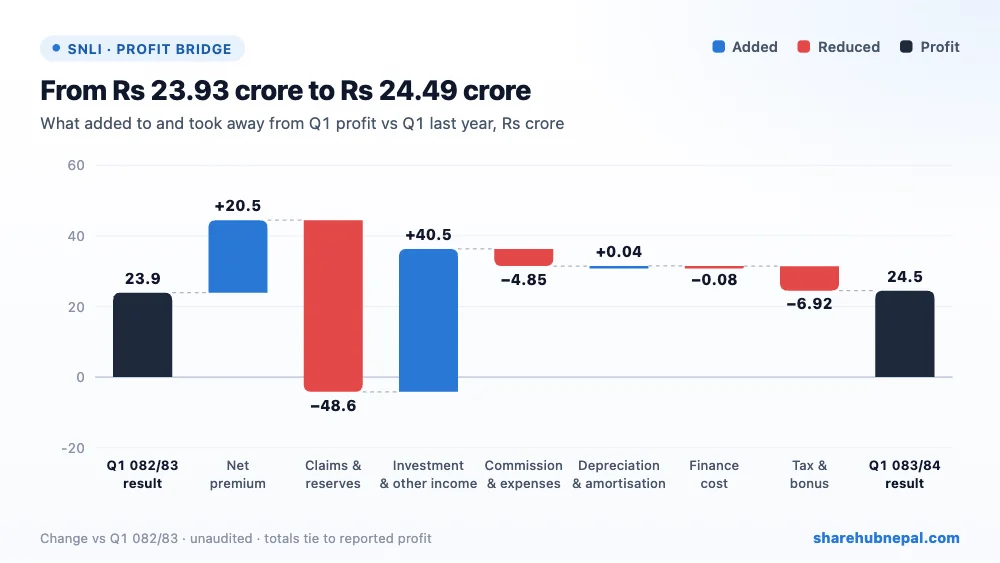
Net premium added Rs 20.50 crore and investment and other income Rs 40.45 crore (mostly the swing from a fair value loss to a gain), but claims and reserve change took Rs 48.58 crore more and commission and other expenses Rs 4.85 crore more. Profit before tax rose 43.44% to Rs 24.71 crore, yet after tax profit grew only 2.36% because last year had a Rs 6.70 crore tax credit.
2. Profit through the year
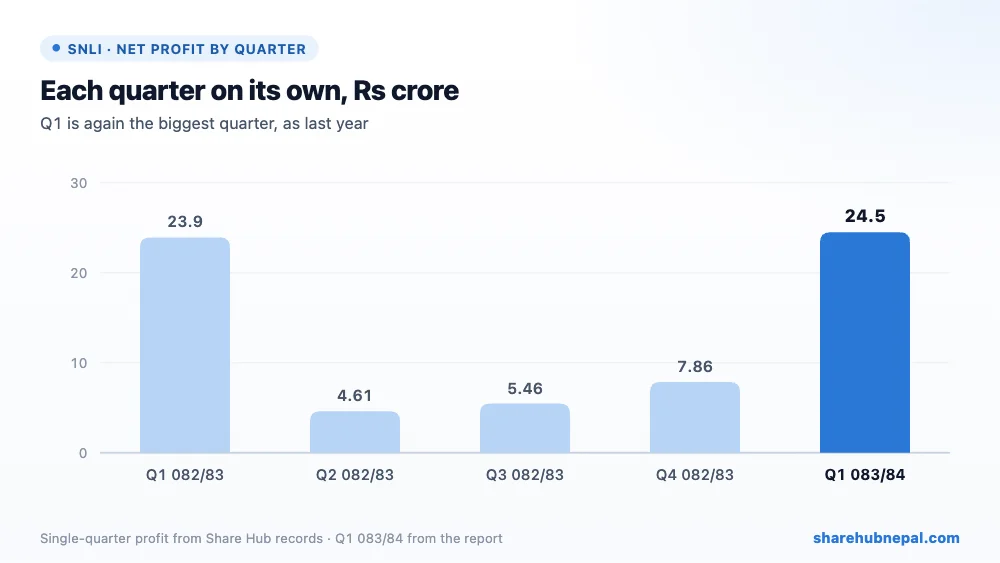
Profit by quarter (Share Hub records): Q1 082/83: Rs 23.93 crore, Q2 082/83: Rs 4.61 crore, Q3 082/83: Rs 5.46 crore, Q4 082/83: Rs 7.86 crore, Q1 083/84: Rs 24.49 crore. As last year, Q1 is the biggest quarter: single-quarter profit fell to Rs 4.61 crore to Rs 7.86 crore in Q2 to Q4 of 2082/83. FY 2082/83 profit was Rs 41.86 crore (EPS Rs 7.92).
3. Debt and balance sheet
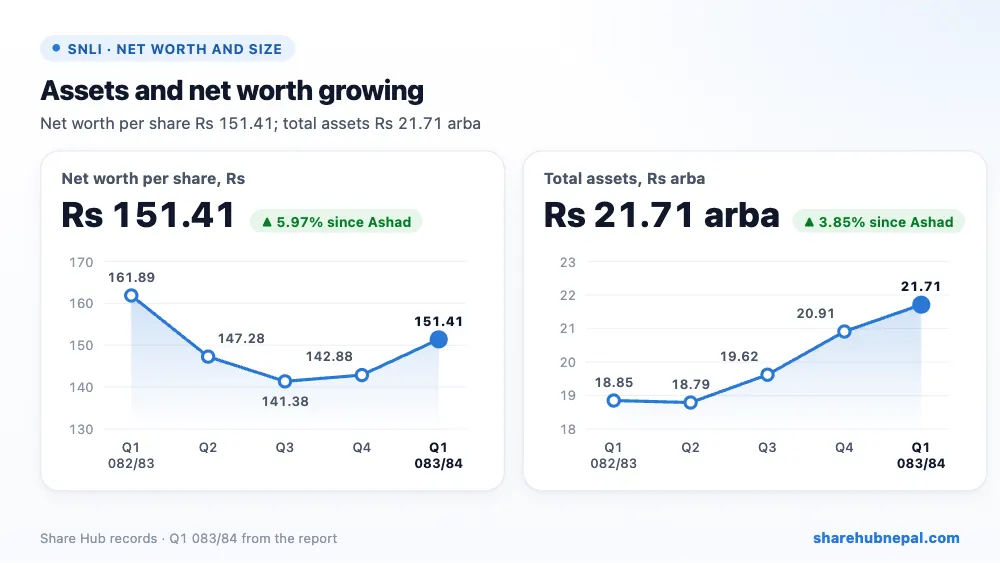
| Particulars | Ashwin 2083 | Ashad 2083 | Change |
| Total assets | Rs 21,711,508,963 | Rs 20,907,531,437 | +3.85% |
| Investments | Rs 18,275,692,349 | Rs 15,988,676,443 | +14.30% |
| Loans to policyholders | Rs 840,988,484 | Rs 808,330,906 | +4.04% |
| Gross insurance contract liabilities | Rs 13,370,033,739 | Rs 12,930,789,169 | +3.40% |
| Total equity | Rs 7,998,914,367 | Rs 7,547,836,309 | +5.98% |
| Cash and equivalents | Rs 394,045,252 | Rs 1,783,200,298 | −77.90% |
Total assets rose 3.85% since Ashad to Rs 21.71 arba, with investments up to Rs 18.28 arba as cash of Rs 1.78 arba was put to work (cash is now Rs 39.40 crore). Insurance contract liabilities rose to Rs 13.37 arba and the life insurance fund is Rs 13.32 arba. Equity rose to Rs 8.00 arba (Rs 151.41 per share), about Rs 21.7 crore more than the quarter's total comprehensive income, which the report does not explain. There are no borrowings, and the last reported solvency ratio is 2.44 times (FY 2081/82).
4. Per-share figures and valuation
| Indicator | Value |
| EPS (annualised) | Rs 18.55 |
| Net worth per share | Rs 151.41 |
| Market price (Ashwin end) | Rs 436 |
| P/E (annualised) | 23.50x |
| P/B | 2.88x |
At the Ashwin-end price of Rs 436, the share trades at 23.50 times annualised EPS and 2.88 times net worth per share. Q1 profit is usually the year's biggest and is before the actuarial valuation, so the annualised P/E looks cheaper than it is; on last year's full EPS of Rs 7.92 the P/E is about 55 times. The report prints P/E 22.73.
Conclusion
Positives: premium up 19.86%, investment income up 21.06%, fair value gain instead of loss, net worth per share up to Rs 151.41, no borrowings.
Watch: net claims and reserve build up 82.54%, profit before actuarial valuation, policies issued and first-year premium in the quarter look low against last year's full-year figures, the unexplained jump in equity, weak economy and tough competition named by management.
Premium and investment income are growing well, but most of the profit growth came from the fair value swing; watch claims and the year-end actuarial valuation.
Figures are from the company's unaudited Q1 report; quarter trends use Share Hub records. This is not investment advice.

